The Wall Street Wrap: October 19, 2026
US stocks rebounded on Monday as investors returned to technology after last week's AI-led rout, with the Nasdaq Composite up 1.11% and the S&P 500 up 0.41%, even as seven of 11 sectors fell and the 10-year Treasury yield rose to 5.14%. Homebuilder sentiment sank to its lowest since 2012, Apple set an October 28 launch event, and Anthropic committed 5% of its shares to a public benefit fund. Abroad, French bond yields jumped after weekend riots and Saudi Arabia postponed its flagship investor conference to 2027.
Chip and AI stocks rebound from last week's rout as the Nasdaq gains 1.1%, but seven of 11 sectors fall, homebuilder sentiment sinks to its lowest since 2012, and French unrest sends bond yields higher
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
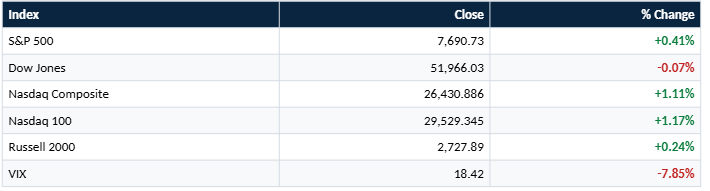
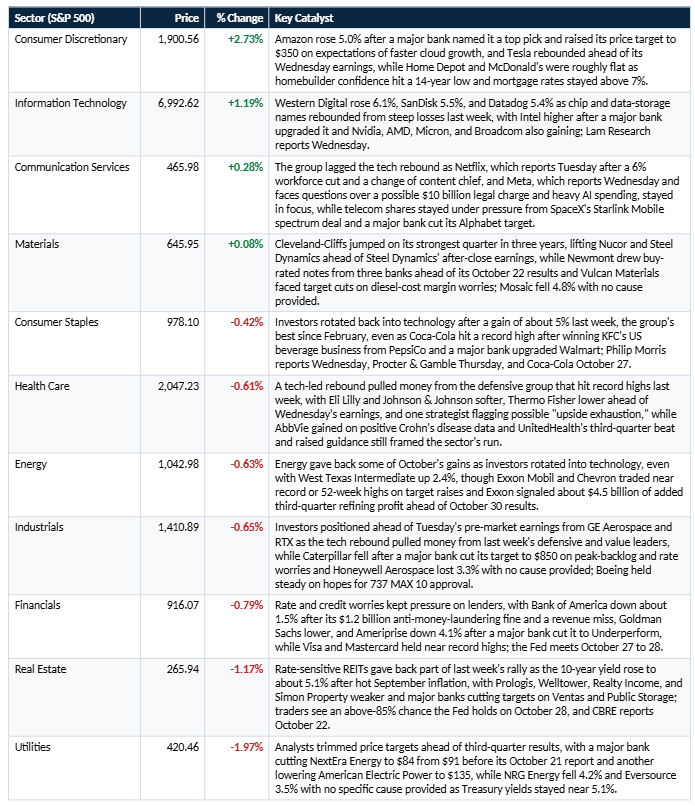
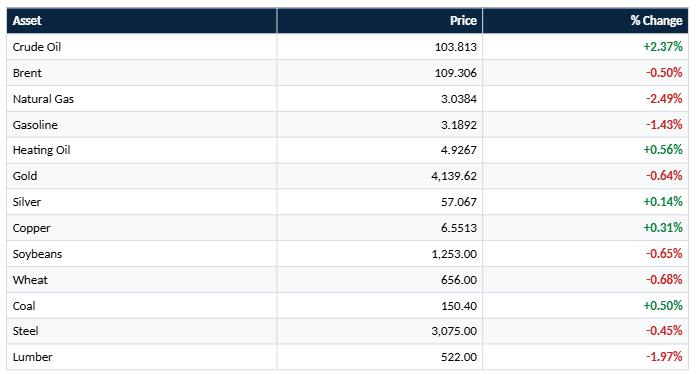
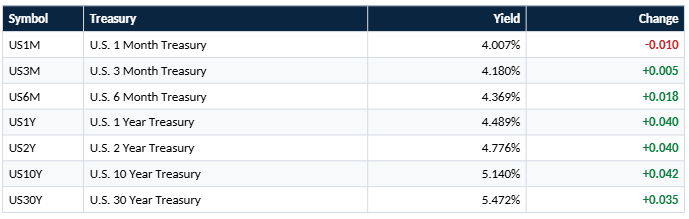
US stocks rose on Monday as investors moved back into technology after last week's AI-driven rout, with the Nasdaq Composite gaining 1.11% to 26,430.886 and the S&P 500 adding 0.41% to 7,690.73. The Nasdaq 100 rose 1.17% to 29,529.345 and the Russell 2000 gained 0.24% to 2,727.89, while the Dow Jones Industrial Average slipped 0.07% to 51,966.03 and the VIX fell 7.85% to 18.42. The advance was narrow: only four of the 11 S&P 500 sectors rose, led by consumer discretionary at 2.73% as Amazon jumped 4.98%, and information technology at 1.19%, while utilities fell 1.97% and real estate 1.17%. Homebuilder sentiment fell to its lowest since June 2012, and Saudi Arabia postponed its flagship investor conference to 2027 as Houthi attacks widened. The 10-year Treasury yield rose 4.2 basis points to 5.14%, West Texas Intermediate gained 2.37% to 103.813, Brent slipped 0.50% to 109.306, and gold fell 0.64% to 4,139.62.
ANALYTICAL VIEW
A bounce, not a broadening, defined the session. The Nasdaq Composite rose 1.11% and the S&P 500 0.41%, but the Dow slipped 0.07% and seven of the 11 sectors fell, as consumer discretionary, up 2.73% on Amazon's 4.98% jump, and information technology, up 1.19%, did most of the lifting. Money left the defensive groups that led last week, with utilities down 1.97%, real estate 1.17%, health care 0.61%, and consumer staples 0.42%, and it left energy, which fell 0.63% even as West Texas Intermediate rose. Data-storage names such as Western Digital and SanDisk gained more than 5%, but the rebound followed a punishing week in which the S&P 500 lost nearly 2%, the Nasdaq 4.5%, and the Philadelphia Semiconductor Index more than 11%.
Rates, not earnings, set the limits. The 10-year Treasury yield rose 4.2 basis points to 5.14% and the 30-year to 5.472%, keeping the cost of financing the AI build-out in focus after a hot September inflation reading. CoreWeave fell about 3% even after an upgrade, Oracle's five-year credit default swaps stood near 295 basis points, a level in line with high-yield credit, and financials fell 0.79% with the 10-year yield above 5.1%. Traders put the odds above 85% that the Federal Reserve holds rates at its October 27 to 28 meeting, while builders reported the weakest sentiment in more than 14 years as mortgage rates climbed.
What could change the picture: Whether SpaceX, Netflix, Meta, and Tesla results and Lam Research's report this week show AI spending paying off, and whether a 10-year yield holding above 5.1% revives worries about financing costs for heavily indebted AI companies.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Western Digital Corporation (NASDAQ:WDC): +6.087%
- Sandisk Corporation (NASDAQ:SNDK): +5.528%
- Datadog, Inc. (NASDAQ:DDOG): +5.362%
- Twilio Inc. (NYSE:TWLO): +5.287%
- Amazon.com, Inc. (NASDAQ:AMZN): +4.98%
Top 5 Decliners:
- The Mosaic Company (NYSE:MOS): -4.782%
- NRG Energy, Inc. (NYSE:NRG): -4.212%
- Ameriprise Financial, Inc. (NYSE:AMP): -4.072%
- Eversource Energy (NYSE:ES): -3.545%
- Honeywell Aerospace (NASDAQ:HONA): -3.332%
Note: Western Digital and SanDisk rose as data-storage and chip stocks rebounded from steep losses last week, Amazon gained after a major bank named it a top pick, and Ameriprise fell after a major bank cut it to Underperform; no specific cause was provided for the moves in Datadog, Twilio, Mosaic, NRG Energy, Eversource, or Honeywell Aerospace.
AFTER-HOURS MOVERS
Decliners:
- Karooooo Ltd. (NASDAQ:KARO), -6.88% after hours: Shares fell to $57.83 after fiscal second-quarter results showed revenue ahead of estimates but adjusted earnings slightly short in rand terms. Revenue was R1.64 billion against about R1.60 billion expected and adjusted earnings were R9.28 a share against about R9.55, while in US dollars earnings of $0.57 a share were in line and sales of $100.3 million beat the $97.7 million estimate. The company affirmed fiscal 2027 GAAP earnings guidance of $2.35 to $2.44 a share against a $2.41 consensus, and the sources do not confirm the cause of the decline. The stock had closed 2.85% higher at $62.10.
- Steel Dynamics, Inc. (NASDAQ:STLD), -6.48% after hours: Shares fell to $229.00 after third-quarter results that were mixed, with earnings of about $5.26 to $5.29 a share missing the roughly $5.48 consensus while revenue of $6.51 billion beat the $6.43 billion estimate. The report followed a strong session for domestic steel peers, with US steel prices at multi-year highs, and the miss came after below-consensus guidance a month ago, with investors also watching an aluminum ramp-up and compressed scrap spreads. The stock had closed 1.80% higher at $244.86.
- Crown Holdings, Inc. (NYSE:CCK), -3.59% after hours: Shares fell to $110.75 even though third-quarter adjusted earnings of $2.39 a share beat the $2.26 consensus, extending its beat streak to ten quarters, and revenue of $3.71 billion beat the roughly $3.46 billion expected. Management guided fourth-quarter adjusted earnings to $1.63 to $1.73 a share, below the roughly $1.80 estimate, and narrowed full-year guidance to $8.35 to $8.45 from $8.30 to $8.50 against an $8.41 consensus, and the softer fourth-quarter outlook appears to be weighing on the stock. The stock had closed 0.63% higher at $114.87.
- Western Alliance Bancorporation (NYSE:WAL), -1.81% after hours: Shares fell to $72.30 after third-quarter earnings of $2.45 a share edged past the $2.42 estimate, ending two straight quarters of misses, though no revenue figure was provided. Investors are watching credit quality, commercial real estate commentary, and deposit costs as regional banks stay under pressure, and no specific cause was confirmed for the decline. The stock had closed 1.18% lower at $73.63.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
AI-linked stocks rebound from last week's rout, though CoreWeave slips even after an upgrade. Chip and AI names bounced as the Nasdaq gained 1.1%, after the index fell 4.5% last week and the S&P 500 lost nearly 2%, its biggest weekly decline since late June. Intel rose about 2% after a major bank upgraded it, AMD and Micron gained about 1% and 2%, and information technology, which shed more than 6% last week, was the second-best sector. CoreWeave reversed earlier gains to fall about 3% even after a major bank raised it to buy, having lost more than 25% last week over concerns about its roughly $50 billion of debt, and hedge funds sold the largest share of technology on record, according to data from a major bank. One chief investment officer said investors would become "much more discriminating" about whether these companies can earn returns that justify their debt.
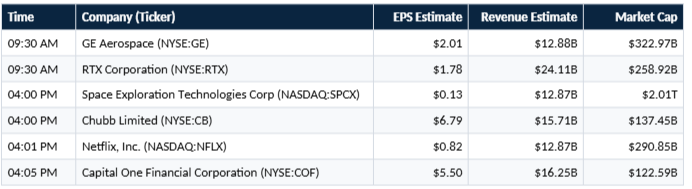
SpaceX reports Tuesday and Tesla on Wednesday as merger talk builds. SpaceX, which went public in June at $135 a share and closed Friday at $146.03, reports after the close on Tuesday, only its second results as a public company, with investors watching whether surging AI spending is turning into revenue after a second-quarter net loss of $541 million on revenue of $7.8 billion. Tesla is expected to report adjusted earnings of about 43 cents a share on revenue of about $27.88 billion, against 50 cents a year earlier, and said it will hold its annual meeting on December 3. A major bank has suggested a deal combining the companies could be announced before that meeting, with SpaceX the likelier acquirer, though neither company nor Elon Musk has committed to one, and in an all-stock deal it estimates Musk would hold about 37% of the equity and 56% of the votes.
Homebuilder sentiment sinks to its lowest since 2012 as mortgage rates climb. The National Association of Home Builders index fell three points to 29 in October, below the forecast of 31 and the lowest reading since June 2012, as the 30-year mortgage rate averaged 7.40% last week, its highest in nearly three years. The share of builders cutting prices rose to 43%, the highest of the 2020 to 2026 period, with an average cut of 6%, while buyer traffic fell five points to 18, its lowest since April 2012 outside the pandemic's onset. More than a third of builders reported immigration enforcement activity in their areas, causing delays, and builders also cited higher costs for loans, materials, diesel, and tariffs.
Anthropic commits 5% of its shares to a public benefit fund, and Musk says shares should go straight to the public. The fund, which needs shareholder approval, would be a wholly owned company that receives 5% of Anthropic's shares immediately and, at the board's discretion, another 2% for every 50% rise in the company's value above a baseline not yet disclosed, to support nonprofit donations, direct distributions, and efforts to address AI's effect on jobs. None of the equity would be used for lobbying or political giving, and with the founders' pledge to donate 80% of their equity and an employee matching program, roughly 20% of the shares would be dedicated to public purposes. Musk replied "I recommend giving the shares directly to the public" and pledged to give one SpaceX share to every child in America next year, worth about $10.5 billion at Friday's close, adding "This will be the first of many," though he gave no details on how it would work.
Apple sets an October 28 launch event in Los Angeles, with a touchscreen Mac laptop expected. Invitations went out on Monday for an event billed "Pro and tell," the company's third launch under chief executive John Ternus, who succeeded Tim Cook last month. One analyst expects new Macs "including a touchscreen notebook," a category Apple has long avoided, with its software chief arguing in 2018 that the ergonomics would fatigue users. Macs account for about 10% of revenue, the iMac has not been updated since October 2024, and Apple shares are up 26% this year.
Also today: JPMorgan said it has invested $5 billion in equity in companies critical to US economic and national security and has financed about $230 billion under its Security and Resiliency Initiative since launching it a year ago; Albertsons began a two-week trial in Delaware seeking more than $8 billion in damages from Kroger over their failed $24.6 billion merger; Nvidia won central-processor business from AI startup Modal, which will run Nvidia's Vera chips alongside Intel and AMD parts, with Nvidia expecting at least $20 billion of Vera sales this fiscal year; the Department of Homeland Security ordered DeepSeek products removed from civilian agency computer systems and barred their acquisition; Microsoft pulled out of a deal to anchor Nscale's Loughton data centre in England after power connection delays pushed supply into the 2030s; Netflix reports Tuesday after the close with revenue forecast to rise 11.8% to $12.87 billion, its slowest third-quarter growth in three years, as US user churn rose and viewing time per member fell; and the European Commission charged KKR with misleading regulators over its 22 billion euro Telecom Italia network deal, exposing it to a fine of up to 1% of annual worldwide turnover.
TOP STORIES: GLOBAL
Trump says he would meet Putin and Xi on Ukraine, and waives new Russia sanctions. The Wall Street Journal reported that Vladimir Putin proposed a three-way summit with Donald Trump and Xi Jinping without Volodymyr Zelenskyy, possibly at the Asia-Pacific Economic Cooperation summit in Shenzhen in November, and Trump, asked about a meeting, told reporters "Anything I can do to end the war, whether somebody's there or not." He said Zelenskyy "doesn't know what he's talking about" and that it is time for someone else to negotiate for Ukraine. On Friday he waived two parts of the Graham Act, which required duties of up to 500% on Russian goods and tariffs of up to 100% on top buyers of Russian oil such as China and India, two days before the deadline, while keeping earlier sanctions, and the administration says it will take up to 60 days to assess the economic impact. Russia fired 16 ballistic missiles and more than 200 drones at Ukraine overnight, leaving at least 550,000 households without power, according to Zelenskyy.
Saudi Arabia postpones its flagship investor conference to 2027 as Houthi attacks widen. The Future Investment Initiative, due in Riyadh from October 26 to 29, was postponed after a Houthi attack on King Khalid International Airport on October 10 killed at least 12 people and injured more than 300, with organizers promising new dates soon. The listed speakers included the heads of JPMorgan Chase, Goldman Sachs, Blackstone, BlackRock, and Citigroup, and the Houthis claimed new attacks on Monday on the airport, Abha airport, Aramco facilities at Yanbu, the Shaybah oilfield, and Saudi naval forces. Iran's military says it has a "new operational plan" if the US resumes strikes, and a tanker struck a mine in the Strait of Hormuz on Sunday, according to Iran's Revolutionary Guard, with Gulf crude flows falling to about 8.5 million barrels a day last week from more than 20 million the week before. West Texas Intermediate settled up 2.22% at $103.66 a barrel while Brent fell 0.28% to $109.55.
French bond yields climb toward multi-decade highs as weekend riots deepen budget worries. About 550,000 people marched on Saturday, including 110,000 in Paris, and the protests turned violent, with almost 2,400 arrests, looted shops, and the town hall in Limoges burned. The French 10-year yield jumped more than 10 basis points to just shy of its highest in decades, the premium over German bunds reached its widest since the euro-area debt crisis, and the CAC 40 fell about 1.7% in afternoon trading. The National Assembly votes Tuesday on the first part of a budget seeking 54 billion euros of savings, with debt at a record 3.6 trillion euros, or 119% of output, and a deficit near 5%, and one strategist said it looks like "either the bond markets riot, or the people riot, or both."
China's economy grows 4.5% as exports surge, and Asia-Pacific markets close mostly higher. Third-quarter growth beat the 4.4% forecast and the 4.3% of the second quarter, helped by a record monthly trade surplus of $133.5 billion, while September retail sales rose 1.1%, industrial output 5.5%, and urban investment fell 7.2% for the first nine months as property investment dropped 20.6%. South Korea's Kospi gained 1.76% to 5,768.01, the Kosdaq 1.78% to 808.89, and Australia's S&P/ASX 200 0.44% to 8,845.7, while Japan's Nikkei 225 lost 0.62% to 64,916.7, the Topix was flat at 4,067.48, and China's CSI 300 was little changed at 4,174.53. Producer prices in China rose 5% in September, the fastest in more than four years, while consumer inflation stayed below 1%.
MANAGEMENT & FED SPEAK
Sanae Takaichi, Prime Minister, Japan, on the weak yen and bond yields:
Takaichi told parliament she "clearly" denies that her policies are behind a weak yen or rising interest rates, arguing that a strong economy will build confidence in the currency. On bonds she said "We intend to appropriately control the amount of government bond issuance," as the yen trades near its weakest since 1986 and the 10-year Japanese government bond yield sits near 2.92%.
Marco Rubio, Secretary of State, United States, on the India trade deal and Ukraine:
Rubio said Washington is "very close" to a trade deal with India and that the talks were one factor in the decision to waive Russia sanctions, adding that "there's been talks of a meeting" among the leaders on Ukraine. He denied that the US had paused intelligence sharing with Ukraine, contradicting Zelenskyy, and is due in India on Tuesday.
Volodymyr Zelenskyy, President, Ukraine, on sanctions relief:
Zelenskyy warned that "Sanctions relief will continue," saying the diesel deal and the Graham Act waiver are "not the end of it," and that the decision "helps only the Russians." He told Bloomberg that "steps have been taken to convince Ukraine to capitulate," while saying he does not want to believe that is his partners' aim.
Emmanuel Macron, President, France, on the riots:
In a televised address Sunday, Macron said "Nothing justifies it, nothing explains it, nothing excuses it," and promised an uncompromising response. He stopped short of declaring a state of emergency but let prefects and mayors ban gatherings, refused his interior minister's resignation, and ordered a review of intelligence and police preparedness, before leaving for Kuwait on a Gulf tour as the prime minister announced local curfews.
CORPORATE ACTIONS & EARNINGS CALENDAR
Top Ex-Dividend Companies for Tuesday, October 20:
Upcoming Earnings (Tuesday, October 20):
Economic Calendar (Tuesday, October 20):
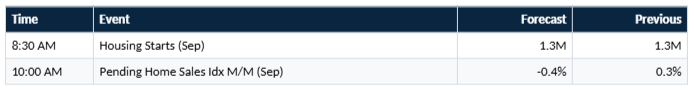
That's the wrap for today! Attention turns to Tuesday's housing starts and pending home sales data, results from SpaceX, Netflix, GE Aerospace, and RTX, France's budget vote, and whether the tech rebound holds with the 10-year Treasury yield near 5.14% and the Fed's October meeting a little more than a week away.
Related post