The Wall Street Wrap: October 23, 2026
US stocks closed lower on Friday as oil jumped and defensive sectors sold off, with the Dow falling 1.23% and the S&P 500 down 0.52%, while the Nasdaq Composite slipped 0.21% and energy hit a record high. AT&T and T-Mobile sank nearly 8% on SpaceX wireless carrier talks, American Express fell 3.7% on job cuts, and Brent settled at $116.72. After hours, FICO fell 6.81% while Hyperliquid Strategies and ORIC Pharmaceuticals rose. In Asia, markets ended the week mixed.
The Dow falls 1.2% as Brent settles at its highest since April and AT&T and T-Mobile sink on SpaceX's wireless plans, while energy hits a record and tech steadies
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
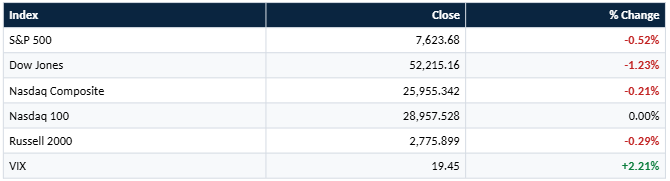
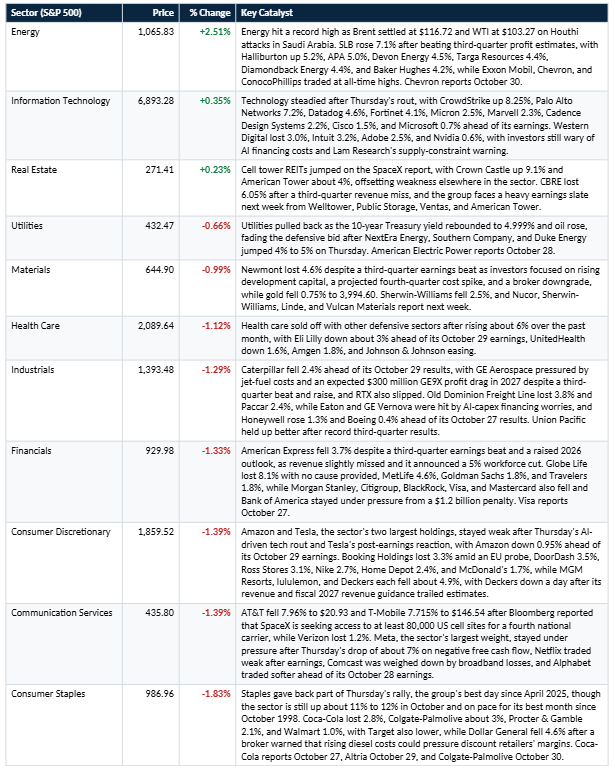
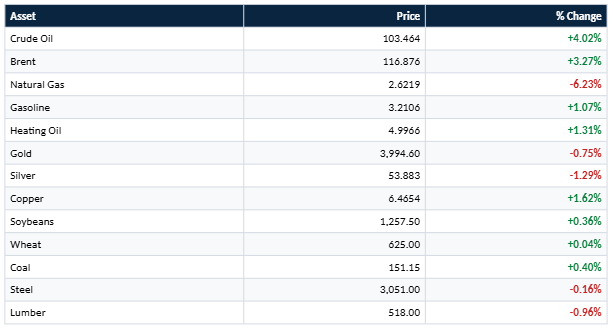
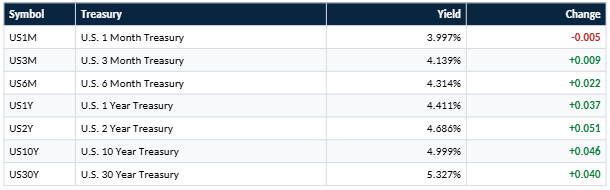
US stocks closed lower on Friday to end a turbulent week as oil jumped on renewed Middle East tensions and defensive stocks gave back Thursday's gains, even as technology steadied after its rout. The Dow Jones Industrial Average fell 1.23% to 52,215.16 and the S&P 500 lost 0.52% to 7,623.68, while the Nasdaq Composite slipped 0.21% to 25,955.342 and the Nasdaq 100 was little changed at 28,957.528. The Russell 2000 fell 0.29% to 2,775.899 and the VIX rose 2.21% to 19.45. Only three of the 11 S&P 500 sectors rose, led by energy at 2.51% to a record high, while consumer staples fell 1.83% and consumer discretionary and communication services each lost 1.39%. AT&T and T-Mobile fell 7.96% and 7.715% after a report that SpaceX is seeking cell sites for a fourth wireless carrier, American Express lost 3.675% on a 5% workforce cut, and SLB rose 7.084% after beating third-quarter estimates. University of Michigan consumer sentiment came in at 48, above the 46.3 forecast. The 10-year Treasury yield rose 4.6 basis points to 4.999%, crude oil rose 4.02% to 103.464, Brent gained 3.27% to 116.876, and gold fell 0.75% to 3,994.60.
ANALYTICAL VIEW
Thursday's defensive rotation reversed. Consumer staples fell 1.83% after the group's best day since April 2025, financials lost 1.33% and health care 1.12%, and the Dow suffered its worst session in two months, with only six of its 30 components rising. American Express lost 3.675%, Coca-Cola 2.759%, Nike 2.662%, Sherwin-Williams 2.48%, Caterpillar 2.422%, and Home Depot 2.411%, while Chevron gained 2.881%. Technology steadied after Thursday's AI-driven rout, with information technology up 0.35%, Micron gaining 2.459%, Marvell Technology 2.255%, and Microsoft 0.658%, though Western Digital fell 2.97% and CoreWeave 2.455%. A strategist at an asset manager said there is "still fallout from the questioning of the AI trade," and for the week the S&P 500 fell 0.5% and the Nasdaq 0.7%, while the Dow rose 0.4% for a third straight weekly gain.
Oil and rates set the tone. Brent settled at $116.72, its highest since April 29, and West Texas Intermediate closed at $103.27 after Houthi attacks across Saudi Arabia, including on energy infrastructure, and reports that the US and Israel may be drawing up plans for renewed attacks on Iran, which lifted energy to a record. The 10-year Treasury yield rose to 4.999%, back near 5% after dipping below it on Thursday, while the University of Michigan survey showed the one-year inflation outlook rising to 4.7%, and flash PMIs came in at 56 for manufacturing, above the 55.3 forecast, and 57.9 for services, just under the 58 forecast. Earnings growth remains strong, with S&P 500 companies on track to have increased third-quarter profit by more than 32%, according to LSEG, and the Fed is expected to hold at its policy decision on Wednesday while investors look for clues on a possible December hike.
What could change the picture: Whether Brent holds above $116 as Gulf supply fears build, whether results from Alphabet, Microsoft, and Amazon ease worries over AI spending, and whether the Fed's Wednesday decision and a 10-year yield near 5% shift expectations for a December hike.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Crown Castle Inc. (NYSE:CCI): +9.058%
- CrowdStrike Holdings, Inc. (NASDAQ:CRWD): +8.25%
- Palo Alto Networks, Inc. (NASDAQ:PANW): +7.221%
- SLB NV (NYSE:SLB): +7.084%
- Halliburton Company (NYSE:HAL): +5.212%
Top 5 Decliners:
- Bloom Energy Corporation (NYSE:BE): -11.237%
- Comfort Systems USA, Inc. (NYSE:FIX): -9.263%
- Globe Life Inc. (NYSE:GL): -8.087%
- AT&T Inc (NYSE:T): -7.96%
- T-Mobile US Inc (NASDAQ:TMUS): -7.715%
Note: Crown Castle rose after a report that SpaceX is in talks with cell tower operators, the same report that sent AT&T and T-Mobile lower, SLB beat third-quarter profit estimates, and Bloom Energy and Comfort Systems extended Thursday's losses after their results; no specific cause was provided for the moves in CrowdStrike, Palo Alto Networks, Halliburton, or Globe Life.
AFTER-HOURS MOVERS
Gainers:
- Hyperliquid Strategies Inc (NASDAQ:PURR), +2.05% after hours: Shares rose to $8.96 after the company said its board raised its stock repurchase program from $30 million to up to $100 million, with about $72 million still available under the existing authorization, and extended the program's end date from December 5, 2026 to October 31, 2027. The digital asset treasury company will report results for the quarter ended September 30 on a webcast on November 5. The stock had closed 1.15% higher at $8.78.
- ORIC Pharmaceuticals, Inc. (NASDAQ:ORIC), +1.44% after hours: Shares rose to $13.36 after the company presented first-line EGFR atypical non-small cell lung cancer data for enozertinib at the ESMO oncology meeting, showing an 84% confirmed systemic response rate, a 70% intracranial response rate, and an 88% six-month landmark progression-free survival rate in 26 patients. The company also announced plans to start the global Phase 3 Redwood-1 trial in the first half of 2027. The stock had closed 3.37% lower at $13.17.
Decliners:
- Fair Isaac Corporation (NYSE:FICO), -6.81% after hours: Shares fell to $759.75 after the company said it will hold its wholesale mortgage price for the FICO Score at $10 through its tri-merge resellers for lenders and brokers enrolled in its Preferred Program, flat from a year earlier, for a bundle of the Classic FICO Score and the FICO Score 10T. The sources do not confirm the cause of the decline. The stock had closed 0.97% lower at $815.31.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
AT&T and T-Mobile sink nearly 8% on a report that SpaceX wants cell sites for a fourth wireless carrier. Bloomberg News reported late Thursday that SpaceX is in talks to access at least 80,000 US cell sites to build a wireless network from scratch. AT&T closed down 7.96% at $20.93, T-Mobile fell 7.715% to $146.54, and Verizon lost 1.2%, while SpaceX rose 1.893% to $147.49. Crown Castle jumped 9.058% to $85.97 after the report identified it as one of the tower companies in the talks, and American Tower rose about 4%. The report follows SpaceX's purchase of low-band spectrum weeks ago, which sent AT&T and Verizon shares to their worst one-day falls in more than two decades, and analysts at a major broker said the competitive impact may still be years away but that anticipation alone is likely to remain an overhang on sector sentiment.
American Express falls 3.675% as it cuts 5% of its workforce to "prepare for AI." The company is eliminating about 5% of its global workforce, which stood at almost 77,000 at the end of 2025, and taking a $336 million restructuring charge. Adjusted earnings of $4.68 a share beat the $4.48 estimate and revenue rose 9% to $20.06 billion, slightly below the $20.12 billion forecast, and the company raised its full-year earnings guidance to $18.30 to $18.60 a share on an unadjusted basis, from $17.30 to $17.90, helped by proceeds from the sale of its stake in Global Business Travel Group. The stock closed at $313.22, and Barclays confirmed Thursday that it plans to trim 5,000 jobs, also about 5% of its staff.
Energy stocks hit records as oil climbs, while uranium and clean energy funds slide to 52-week lows. The S&P 500 energy sector rose 2.51% to a record high, with Exxon Mobil, Chevron, and ConocoPhillips all trading at all-time highs and SLB up 7.084% after beating third-quarter profit estimates. By contrast, the Global X Uranium ETF and Sprott Uranium Miners ETF fell to their lowest levels since June 2025, while the Invesco Solar ETF and Invesco WilderHill Clean Energy ETF hit lows not seen since September and August last year. Centrus Energy, Oklo, NuScale Power, Energy Fuels, and BWX Technologies also touched 52-week lows, and the US oil and gas rig count held at 603 for a second straight week, according to Baker Hughes.
Consumer sentiment holds near a record low as inflation expectations edge higher. The University of Michigan's final October reading was 48, down 0.1 point from September and above the 46.3 forecast, and 10.4% lower than a year ago. Current conditions fell 8.3% on the month while the expectations measure rose 5.4%, and the one-year inflation outlook rose to 4.7% and the five-year to 3.5%, each up 0.1 percentage point. Flash PMI readings were firm, with manufacturing at 56 against the 55.3 forecast and 57 previously, and services at 57.9 against the 58 forecast and 58.7 previously.
Discount retailers fall as diesel costs pressure margins. Dollar General closed 4.615% lower at $132.69 after analysts at a major broker warned that rising diesel prices could weigh on profits through the second half of the year and into 2027. Third-quarter diesel prices are up about 60% from a year ago, and the analysts estimate the average hit to operating margin will widen to about 27 basis points from 18 basis points in the second quarter, with a drag on earnings per share of 6.2%. They called Dollar Tree the most exposed, with a hit of about $25 million, or 50 basis points of margin, to third-quarter profit, and Dollar Tree traded about 5% lower and Five Below and TJX more than 1% lower in midday trading.
Also today: President Donald Trump signed a proclamation removing some Canadian goods from the 50% tariffs imposed under Section 338 but replacing them with valves, carpets, waste products, and other items, effective October 30; Trump also signed an executive order, "Decreasing Housing Costs for the American People," directing the Federal Housing Finance Agency to pilot a program that proactively cancels mortgage insurance on eligible future loans and to make permanent a pilot that waives the lender's title insurance policy, with 30-year mortgage rates at 7.32%, according to Freddie Mac; cybersecurity teams worldwide are racing to patch flaws in the PHP programming language, discovered using advanced AI models, in what some are calling "Black October," with nearly 70% of websites using PHP by some estimates; TikTok's US entity is looking to secure multiple gigawatts of computing capacity, with one source saying it wants four gigawatts by the early 2030s, while Oracle remains its primary cloud provider; and a major bank said Oracle's fiscal 2027 financing framework includes about $20 billion of equity issuance that has already been executed, $20 billion to $25 billion of customer prepayments, and about $20 billion of debt expected in the second half of the fiscal year.
TOP STORIES: GLOBAL
Brent settles at $116.72, its highest since April 29, as Houthi attacks in Saudi Arabia stoke supply fears. Brent futures rose $3.55, or 3.14%, and West Texas Intermediate gained $3.80, or 3.8%, to $103.27, leaving Brent up 6% on the week and WTI up 2.3%. Saudi Aramco ordered the evacuation of its Dhahran headquarters on Thursday as fighting between Saudi Arabia and the Houthis intensified, and the United Arab Emirates reported an oil spill from a tanker off Umm Al Quwain. The US Energy Department authorized an emergency exchange of up to 400,000 barrels of crude from the Strategic Petroleum Reserve, already at its lowest level since 1982, to address a supply disruption at Phillips 66's Lake Charles refinery.
Asia-Pacific markets end the week mixed. South Korea's Kospi added 0.3% to 5,550.3, while the tech-heavy Kosdaq declined 1.62% to 751.69. Japan's Nikkei 225 lost 0.34% to 62,693.16 and the Topix declined 0.79% to 3,965.81, while Australia's S&P/ASX 200 was flat at 8,795.2. China's CSI 300 rose 1.71% to 4,105.33 but closed lower for the week for an 11th straight time. Japan's core inflation in September rose to 2.1% from 1.7% in August, its highest this year and in line with forecasts, while the "core-core" measure preferred by the Bank of Japan was 2.4%.
UK retail sales fall 0.4% in September, more than expected. The drop compared with a 0.1% decline forecast in a Reuters poll and partly reversed August's 0.7% rise, though retail volumes rose 0.7% in the third quarter from the previous three months, the Office for National Statistics said. The data put consumer spending in focus ahead of the government's October 28 budget, and UK GDP rose 0.1% in August.
Qatar agrees to buy US natural gas from Cheniere as the Iran war reshapes energy markets. QatarEnergy agreed Thursday to buy 4 million metric tons of liquefied natural gas a year from Cheniere Energy through 2054, with the price indexed to Henry Hub plus a fixed fee and deliveries expected to begin in the 2030s. Qatar's shipments have collapsed since Iran bombed its Ras Laffan facility in March, which took out about 17% of its LNG export capacity and will take about three years to repair, and it has declared force majeure every month since. Shares of Cheniere and Venture Global have gained 26% and 40% since the war began, and Venture Global is reported to be in advanced talks to supply Qatar with 3 million metric tons annually, according to unnamed sources.
MANAGEMENT & FED SPEAK
Christophe Le Caillec, Chief Financial Officer, American Express, on the restructuring:
Le Caillec said in an interview that the cuts are meant to make the company "leaner, more agile, and also to prepare for AI." He added, "You don't want to automate processes that are not optimally structured," saying the company is reducing layers and increasing spans of control.
Stephen Squeri, Chairman and Chief Executive Officer, American Express, on AI agents:
Squeri told analysts the charge was meant to improve efficiency and speed up innovation. On AI agents, he said the company is "not going to let assistants run rogue through our system," and will only allow agents approved through API or MCP channels.
Will Lansing, Chief Executive Officer, FICO, on mortgage score pricing:
Lansing said holding the price at $10 ensures lenders have "access to the trusted and predictive tools they need to assess risk with confidence." The price covers both the Classic FICO Score and the FICO Score 10T for lenders in the Preferred Program.
Donald Trump, President, United States, on Iran and Starlink:
Trump said the US could end the war with Iran quickly but that perhaps Washington should allow the conflict to gradually wind down. He also told reporters at the White House that he would call on Elon Musk to lift the Starlink restrictions in Ukraine.
Jack Fusco, Chief Executive Officer, Cheniere Energy, on the Qatar deal:
Fusco said in a statement, "We look forward to reliably supplying QatarEnergy from both Sabine Pass and Corpus Christi" into the second half of the century. The deal covers 4 million metric tons of LNG a year through 2054.
CORPORATE ACTIONS & EARNINGS CALENDAR
Top Ex-Dividend Companies for Monday, October 26:
Earnings Reported After the Close (Friday, October 23):
No after-close earnings data was provided for this edition.
Upcoming Earnings (Monday, October 26):
Economic Calendar (Monday, October 26):
No economic events are scheduled for Monday.
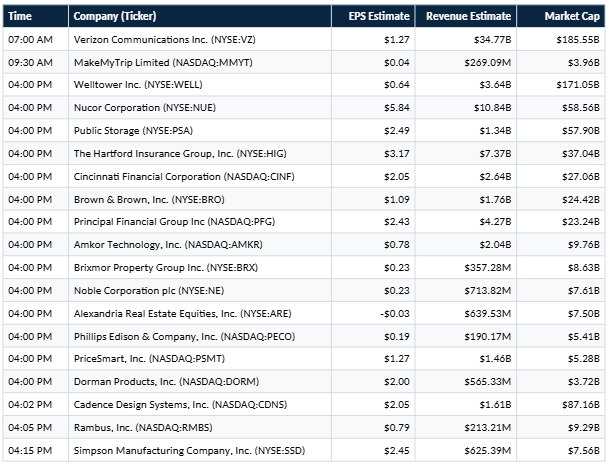
That's the wrap for today! Attention turns to Monday's earnings from Verizon, Welltower, and Cadence Design Systems, how FICO, Hyperliquid Strategies, and ORIC Pharmaceuticals trade at the open, whether Brent holds above $116, and a week that brings results from Alphabet, Microsoft, and Amazon and the Fed's decision on Wednesday.