Wall Street Wrap: Pre-Market, October 23, 2026
U.S. stock futures slip on Friday after the Nasdaq's worst day since June, as telecom stocks fall and tower owners Crown Castle and American Tower soar on a report that SpaceX is building a fourth wireless carrier, while Brent crude hits a five-month high.
Futures slip after the Nasdaq's worst day since June, telecoms fall and tower owners soar on a wireless-carrier report, and Brent hits a five-month high
Wall Street looks set for a lower open on Friday as investors remain uneasy after Thursday's sharp tech sell-off, with oil above $100 and telecom stocks sliding on a report that SpaceX (NASDAQ:SPCX) is moving toward becoming a fourth nationwide wireless carrier.
Futures Snapshot
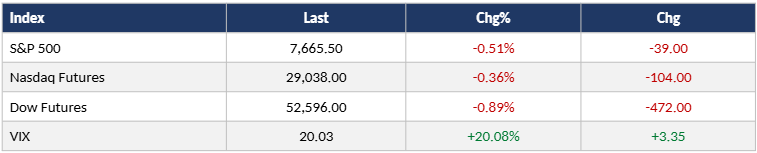
Futures were lower early Friday, with the Dow leading the declines and the VIX jumping as investors braced for more volatility.
What's Driving the Open
Wall Street is coming off its worst session in months. The Nasdaq Composite fell 2.6% on Thursday, its sharpest one-day drop since June 5, and the S&P 500 fell 1.2% while the Dow ended flat, as Meta Platforms (NASDAQ:META) slumped 7%, its largest drop since July, after saying it would issue a new class of shares to help fund its AI spending, and Tesla (NASDAQ:TSLA) fell 3% to 4% on its results. Chip stocks bore the brunt, with the Philadelphia Semiconductor Index down 6.7%, Nvidia (NASDAQ:NVDA) down 4.4%, Advanced Micro Devices (NASDAQ:AMD) down 8.1%, Lam Research (NASDAQ:LRCX) down 12% and Micron Technology (NASDAQ:MU) down 6.3%. CoreWeave (NASDAQ:CRWV) dropped 10%, extending its monthly decline to 36%. Chip stocks are bouncing slightly this morning, with Micron and AMD up about 1% in early trading, and Goldman Sachs' prime brokerage team said hedge funds had their worst day since the pandemic. Ed Yardeni of Yardeni Research described the AI trade as a bubble, but said "taking some air out of the AI bubble is a good thing."
Oil is the other driver. Brent crude touched $114.72, its highest since May 4, as Houthi attacks on Saudi infrastructure and Aramco's evacuation of its Dhahran headquarters revive supply fears, and U.S. oil is back above $100. Treasury yields are edging up after Thursday's plunge, which was the 10-year's biggest one-day drop in about 3.5 years. Big Tech earnings from Microsoft (NASDAQ:MSFT), Alphabet (NASDAQ:GOOGL) and Amazon (NASDAQ:AMZN) come next week, alongside the Fed's Oct. 27-28 meeting.
What could change the picture: A further escalation in the Gulf would push oil higher and weigh on equities, a rebound in chip and AI-linked stocks would ease pressure on the Nasdaq, and weak guidance from next week's megacap earnings would revive worries about AI spending.
Overnight Markets
In Asia, markets closed mixed. South Korea's Kospi added 0.3% to 5,550.3 after SK Hynix reversed early losses to close 4.4% higher on its decision to halt a review of a U.S. IPO for its Solidigm subsidiary, while the tech-heavy Kosdaq fell 1.62% to 751.69. Japan's Nikkei 225 lost 0.34% to 62,693.16 and the Topix declined 0.79% to 3,965.81, while Australia's S&P/ASX 200 was flat at 8,795.2. China's CSI 300 rose 1.71% to 4,105.33 but still closed lower for the week for an 11th straight time. European markets steadied after Thursday's sell-off.
Pre-Market Movers
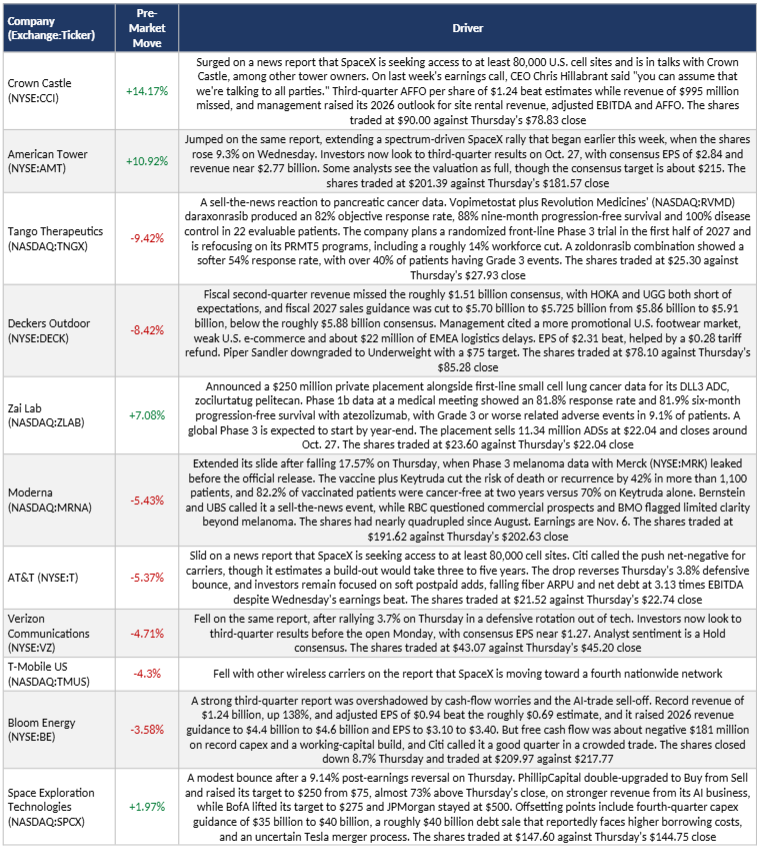
Earnings Before the Bell
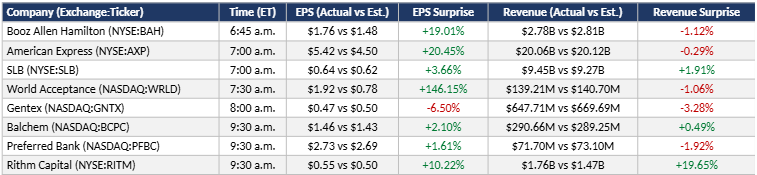
First Citizens BancShares (NASDAQ:FCNCA) is also due this morning, with consensus EPS of $46.18 and revenue of $2.26 billion.
Rates, FX & Crypto
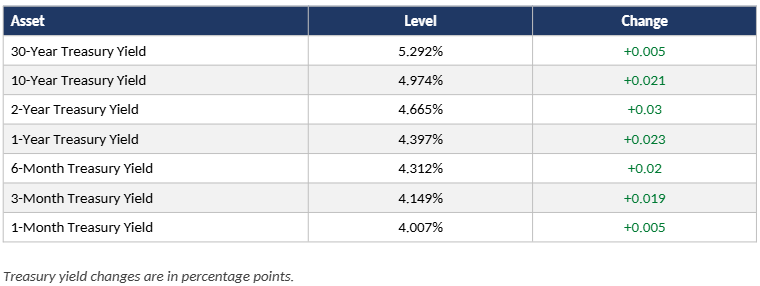
Yields are edging higher after Thursday's sharp drop, when the 10-year fell about 16 to 19 basis points as investors sought safety, and credit spreads widened to their widest since May 2025. Markets are pricing about an 80% chance of a Fed rate hike by December, with the central bank meeting Oct. 27-28 and the European Central Bank and Bank of Japan following. The euro slipped as French debt stress weighed. Bitcoin is up 0.43% to about $81,663 after dipping to roughly $80,989 overnight, having fallen from $84,800 on Wednesday as the tech sell-off triggered more than $400 million of leveraged long liquidations. It remains inside its $80,000 to $87,000 range, and spot bitcoin ETFs saw $636 million of outflows on Thursday. Crypto-linked stocks, including Strategy (NASDAQ:MSTR), Mara Holdings (NASDAQ:MARA), Coinbase (NASDAQ:COIN) and Robinhood (NASDAQ:HOOD), fell sharply Thursday.
Commodities
Oil is climbing toward multi-month highs. Brent crude touched $114.72, its highest since May 4, and U.S. West Texas Intermediate is about $101.33, up 1.9%, with Brent on track for a third straight weekly gain of about 4.2%. Saudi Aramco ordered the evacuation of its Dhahran headquarters as fighting intensified with Yemen-based Houthis, who have pushed toward the Bab el-Mandeb chokepoint, and reports that the U.S. and Israel are drawing up plans for renewed strikes on Iran are adding to supply fears. UBS analyst Giovanni Staunovo said the market is concerned a worst-case escalation could trigger renewed supply disruptions. In Libya, a pipeline valve shutdown has cut output at two oilfields, while the first Russian diesel cargo bound for the U.S. since a surprise Moscow-Washington agreement is heading to New York.
Key Levels & Catalysts Today
Economic data
- The Fed meets Oct. 27-28, followed by the European Central Bank and Bank of Japan, with markets pricing about an 80% chance of a hike by December.
- Japan's core inflation rose to 2.1% in September, the highest this year, raising the odds of another Bank of Japan rate hike.
Corporate
- Earnings before the bell are listed in the table above, including American Express, SLB and First Citizens BancShares.
- Full Phase 3 melanoma data for Moderna and Merck are due Saturday at a medical meeting in Madrid.
- Verizon reports before the open Monday, American Tower reports Oct. 27, and Microsoft, Alphabet and Amazon report next week.
Top Stories
Hedge funds suffer their worst day since the pandemic. All three major strategies tracked by Goldman Sachs lost more than 1% on Oct. 22, a first since the COVID era, as the tech sell-off forced deleveraging in crowded AI-linked trades. Fundamental long-short funds are down 3.8% in October but still up 8.8% this year, while tech-focused and Asia-focused funds are down roughly 10% and 9% this month. Meta's plan to issue a new class of shares to raise funds was one catalyst for the sell-off.
SK Hynix scraps its Solidigm IPO plans. The South Korean chipmaker halted a review of a U.S. listing for its Solidigm subsidiary, citing capital-market conditions, after South Korean regulators said the dual listing could violate local rules. The company had sought to raise about $15 billion and says it will explore other ways to fund a new U.S. fab. Its shares closed 4.4% higher after falling as much as 3%, and analysts said the decision removes a governance worry. SK Hynix reports earnings next week.
Trump invokes the Defense Production Act for oil. In a presidential memo, Trump determined that petroleum production, refining and related activities are essential to national defense, opening the door to U.S. funding for oil projects, pipelines and storage of liquid fuels. The memo said financing, permitting and infrastructure constraints stop the U.S. from providing enough of these services in a timely manner, and it named no specific projects. Crude and diesel prices have surged since the U.S. and Israel attacked Iran in late February, a political risk for Republicans ahead of the Nov. 3 elections.
Japan's core inflation hits its highest level this year. Core inflation, which strips out fresh food, rose to 2.1% in September from 1.7% in August, while the "core-core" measure favored by the Bank of Japan, which also excludes energy, was 2.4%. Weak-yen import costs and indirect energy effects are driving prices, and the central bank raised rates to a three-decade high of 1.25% in September. An economist at Capital Economics expects another hike in December, and the yen strengthened to 156.15 against the dollar.
Apple's first foldable iPhone goes on sale. The iPhone Duo, priced at about $2,000, hit stores around the world on Friday, with sales rationed at two per customer and fewer of the overnight queues that marked past launches. Apple (NASDAQ:AAPL) is the first big test for new CEO John Ternus, and IDC expects it to take 44% of the foldable market's value in 2026 on 31% of units. Early reviews praise the design and hinge but note camera compromises, including no telephoto lens.
Eyes on whether chip and AI-linked stocks stabilize, on oil as Gulf tensions escalate, and on next week's Fed meeting and megacap earnings.
Related post