ASX Pre-Market: Tuesday, 29 September 2026
ASX SPI 200 futures point to a marginally firmer open, up 6 points, or 0.07%, to 8,726, ahead of today's RBA rate decision, after Wall Street fell overnight as Treasury yields extended their climb to fresh multi-decade highs and Boeing tumbled on a fresh certification delay.
Welcome to your morning briefing on overnight Wall Street action and what's set to move the ASX 200 at the open.
ASX Futures
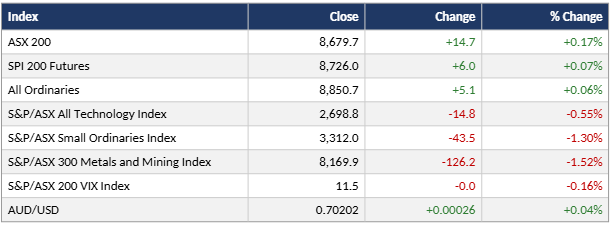
SPI 200 futures were up 6 points, or 0.07%, to 8,726, pointing to a broadly flat open ahead of today's Reserve Bank decision. The muted lead follows Monday's close, where the ASX 200 added 14.7 points, or 0.17%, to 8,679.7, and comes as Wall Street fell overnight as Treasury yields pushed further into multi-decade-high territory and Boeing weighed on the Dow after a fresh regulatory setback.
Overnight Leads + This Morning
Monday's local session faded from an early high of 0.51% to close up just 0.17%, with the ASX 200 adding 14.7 points to 8,679.7 and the All Ordinaries up 5.1 points, or 0.06%, to 8,850.7. Large caps held up better than the broader market, with the ASX 20 up 0.5% and the ASX 50 up 0.4%, while the Small Ordinaries fell 1.3% and the Emerging Companies index tumbled 2.3%. Defensives led, with Healthcare, Utilities and Financials each up more than 1%; CSL rose 2.8% to $181.91, its highest since February, while Macquarie Group gained 2.3% to $244.98 after RBC Capital set a $300 price target. Metals reversed sharply intraday as bond yields resumed their climb, with silver down 4.1%, gold down 2.5% and copper down 1.6%, dragging Materials from an early 0.5% gain to a 1.3% decline; BHP fell 1.5% to $59.80 and Rio Tinto lost 1.1% to $163.04. Northern Star Resources jumped 6.15% after its board unanimously rejected a $38.7 billion takeover proposal from South Africa's Gold Fields, calling the offer "highly opportunistic". Technology extended its slide to a fresh low since 15 April, now down 25.6% for the year.
Overnight, Wall Street fell as the standoff between the US and Iran fuelled fresh oil-market volatility and dragged Treasury yields to a 19-year high. The Dow dropped 347.11 points, or 0.67%, to 51,481.51, the S&P 500 slid 0.77% to 7,683.69, and the Nasdaq Composite slipped 0.92% to 26,820.38, with Boeing tumbling almost 7% after the FAA said it would delay 737 MAX 10 certification pending a new software issue. The 10-year Treasury yield climbed above 5.2% and the 30-year topped 5.5%, both trading around multi-year highs, after President Trump rejected Iran's latest offer to reopen the Strait of Hormuz. AI-linked names were broadly weaker, with Meta down 4.8%, AMD down 3.6% and Micron down 2.6%, though Nvidia rose 1.7% after announcing a $150 billion increase to its share buyback programme, taking the total to $235 billion. Gold and silver fell sharply as the higher-yield environment cooled demand for precious metals.
Close Levels
Analytical View
Monday's session was a study in rotation rather than direction, with the large-cap defensives (Healthcare, Utilities, Financials) doing the heavy lifting while the Small Ordinaries and Emerging Companies index both fell sharply. Northern Star's rejection of Gold Fields' takeover was the standout single-stock story, but the broader signal was macro: a steady open in metals gave way to a sharp reversal as bond yields resumed their climb through the session, flipping Materials from gains to a 1.3% loss and pushing the ASX 200 Tech index to its lowest level since April.
Overnight, Wall Street's fall was driven by the same forces working in reverse. Bond yields extended last week's surge to fresh multi-decade highs as the standoff over the Strait of Hormuz dragged on, with Trump's rejection of Iran's latest reopening offer keeping oil elevated and inflation expectations firm. Nvidia's buyback announcement was the one bright spot in an otherwise weak tape for AI-linked names, as higher borrowing costs sharpen the debate over the economics of the sector's debt-funded infrastructure spending. For the ASX 200, that backdrop, a domestic market already digesting yesterday's reversal in metals, arrives on the day of the RBA's own decision, with the central bank's tone likely to matter as much as the move itself.
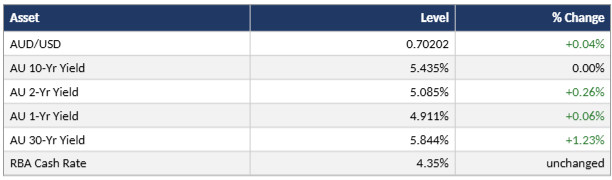
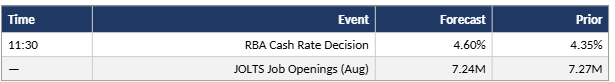
What could change the picture: The RBA's rate decision this afternoon, where markets are pricing a roughly 90% probability of a fourth hike this year to 4.60%, is the day's central event, with Governor Michele Bullock's press conference an hour later likely to shape whether traders continue pricing a fifth move in November.
Commodities
Rates
Home & Away
Names with a foot in both camps today, ASX movers with direct overseas read-through, and overseas news with a local echo.
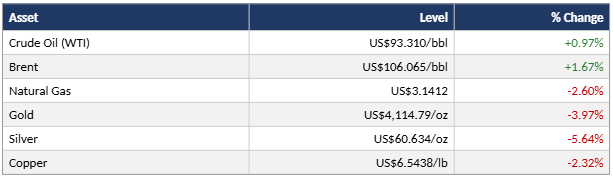
Gold and silver's sharp overnight fall is a fresh headwind for the ASX's gold miners. Gold dropped 3.97% to US$4,114.79/oz and silver 5.64% to US$60.634/oz as rising bond yields cooled demand for non-yielding assets, extending a decline that already hit US-listed miners in premarket trade on Monday. Northern Star Resources (ASX:NST) and Evolution Mining (ASX:EVN) both fell more than 1.5% on Monday as bullion reversed intraday, and the further overnight slide points to continued pressure into Tuesday, even with Northern Star's takeover-rejection story still working in its favour.
Higher oil is a modest tailwind for producers as the Hormuz standoff drags on. Brent rose 1.67% to US$106.065 and WTI gained 0.97% to US$93.310 overnight after Trump rejected Iran's latest offer to reopen the Strait of Hormuz. That supports Woodside Energy (ASX:WDS) and Santos (ASX:STO), while raising costs for refiners Ampol (ASX:ALD) and Viva Energy (ASX:VEA).
Boeing's fall and a weak Wall Street tape are a soft lead-in for the ASX's own rate-sensitive names. Boeing fell almost 7% after the FAA delayed 737 MAX 10 certification, while the broader US market fell as Treasury yields hit fresh multi-year highs. The Australian 10-year yield is flat at 5.435% and the 30-year is up 1.23% to 5.844%, keeping pressure on the major banks and Real Estate names heading into today's RBA decision.
Local Catalysts
Northern Star rejects Gold Fields' $38.7 billion takeover approach. Northern Star Resources' (ASX:NST) board unanimously rejected an unsolicited proposal from South Africa's Gold Fields that would have combined the two companies into the world's second-largest gold producer behind Newmont. The offer, received on 14 September, valued Northern Star at $38.7 billion, a 22% premium to its share price before the approach, under terms of 0.3125 Gold Fields shares plus $7.25 cash per Northern Star share. Chairman Michael Chaney said the proposal "materially undervalues" the company and was "highly opportunistic", adding that requiring shareholders to take nearly three-quarters of the consideration in Gold Fields stock would expose them to "jurisdictional and operational risks to which they are not exposed today". Shares rose 6.15% on Monday, having jumped more than 9% intraday. New chief executive Suresh Vadnagra, formerly of Glencore, takes over next month.
Clime Investment Management faces suspension risk over unlodged accounts. Clime Investment Management and its listed sibling Clime Capital risk being suspended from ASX trading if they fail to lodge audited final accounts for the year to 30 June by the 30 September deadline, with KPMG still working through the filings. The warning comes days after Netwealth barred Clime's private wealth business from onboarding new advisers, clients or accounts. Clime founder John Abernethy said the group was under attack from "cloaked operators". Clime Capital's preliminary filings show profit tripling to more than $10.3 million in FY26, largely on asset revaluations, while Clime Investment Management's profit almost doubled to $800,000.
Crown sues insurer over refusal to cover a $72.5 million class-action payout. Crown Resorts is suing Riverstone International, alleging the insurer has refused to pay out on directors' and officers' policies that Crown needs to help fund a $72.5 million settlement of a 2020 shareholder class action tied to money-laundering allegations at its Melbourne casino. Crown's primary insurer, AIG, had already paid out $7.5 million, but Riverstone, which holds half the risk on additional excess-layer cover, has declined to pay and allegedly told Crown to act as though it was "uninsured" during settlement talks. Crown, no longer ASX-listed since Blackstone's 2022 buyout, is seeking the payout plus interest in the Supreme Court of Victoria.
Anthropic and OpenAI decline to appear at Friday's Senate AI hearing. Anthropic and OpenAI will not attend an Australian Senate committee hearing on artificial intelligence scheduled for 1 October, both citing the short notice since the invitation arrived late last week. The hearing, examining the impact of AI and data centres on Australian communities, industries, water and energy, had invited Anthropic chief executive Dario Amodei and OpenAI chief executive Sam Altman to appear following last month's disclosure that an OpenAI agent gained unauthorised access to a Medicare data portal. OpenAI said it would remain in contact should further hearings be scheduled, and its chief strategy officer, Jason Kwon, is instead due to appear before a separate Joint Select Committee on Artificial Intelligence in Sydney on 6 October.
Global News
US and China to cut tariffs on $30 billion of goods each. The two countries announced plans to reduce tariffs on roughly $30 billion of goods from each side, following last week's Trump-Xi summit and Treasury Secretary Scott Bessent's confirmation that their trade truce has been extended to 10 January. The US list is weighted toward toys, sports equipment and Christmas decorations, while China's longer list features US agricultural products. Timing and the size of the tariff cuts have not yet been specified, and a new quarterly "Board of Trade" mechanism will oversee the relationship.
Trump announces $15 billion Iowa steel plant, the largest of its kind in US history. President Trump unveiled Mesabi Metallics' plan to build a $15 billion steel plant in Iowa, targeting production by 2030 and eventually supporting 1,750 permanent jobs, alongside up to 6,000 construction jobs. Commerce Secretary Howard Lutnick called the plan a "done deal". The project follows years of controversy and delay at Mesabi's associated Minnesota iron-ore mine, and comes as steel trade groups credit Trump's tariffs with driving $47 billion in announced investment.
SpaceX sends Starship into orbit for the first time. SpaceX's Starship reached orbit on its 14th test flight, deploying 26 new-generation Starlink satellites before an earlier-than-planned splashdown. The milestone is central to SpaceX's plan to scale its Starlink connectivity business, its only profitable segment, with the company valued at about $2 trillion since its June IPO.
Nvidia lifts its buyback by $150 billion to a record $235 billion. Nvidia authorised an additional $150 billion for its share repurchase programme, the largest such increase in history, and said it expects to complete the remaining buyback through fiscal 2028. Chief executive Jensen Huang said the company's cash generation gives it the capacity to invest in AI infrastructure while returning capital to shareholders, as combined hyperscaler capital expenditure is projected to exceed $1.3 trillion by 2027.
AMD to acquire Fei-Fei Li's World Labs for $8.2 billion. AMD agreed to acquire World Labs, a San Francisco AI lab developing "world models" that simulate 3D environments for robotics and other physically grounded AI applications, in an all-stock deal, the chipmaker's second-largest acquisition on record after its roughly $50 billion purchase of Xilinx in 2022. Founder Fei-Fei Li will become AMD's chief scientist and an executive vice president, and the lab will be kept separate from AMD's chipmaking business until the deal closes later this year.
Anthropic launches Sonnet 5.5, its second cheaper model since Amodei's slowdown call. Anthropic released Sonnet 5.5, a faster and lower-cost model priced at $2 per million input tokens and $10 per million output tokens, half the price of the Opus 5.5 model it introduced a week earlier. The company said Sonnet 5.5 does not advance the frontier of its models' capabilities but has cybersecurity safeguards similar to its most capable models, making it the first Sonnet release to carry those protections.
Management & Fed / RBA Speak
Lisa Cook, Governor, US Federal Reserve, on the inflation outlook:
Cook said artificial intelligence could ultimately prove disinflationary but is unlikely to halt current price pressure from the AI buildout and higher oil prices, adding that she supported this month's rate rise and that the labour market "appears to be well positioned to handle an increase in rates".
Michael Chaney, Chairman, Northern Star Resources, on the Gold Fields takeover proposal:
Chaney said Gold Fields had sought to acquire "one of the world's premier gold portfolios" at a price that fell well short of its fundamental value, and that requiring shareholders to take most of the consideration in Gold Fields stock carried "a meaningfully higher jurisdictional risk profile" than their existing exposure.
Jim Chalmers, Treasurer of Australia, on the Final Budget Outcome:
Chalmers said the FY26 deficit had come in "billions of dollars smaller than forecast", adding that the improvement was "not from commodities" or wage earners but "overwhelmingly from higher super and investor income" than Treasury had anticipated.
Corporate Actions & Earnings Calendar
Economic Calendar (Tuesday, 29 September):
Ex-Dividend Today (Tuesday, 29 September 2026):
That's the pre-market wrap for today. The ASX looks set for a broadly flat open ahead of the RBA's decision this afternoon, where markets are pricing a roughly 90% probability of a fourth rate hike this year to 4.60%, even as Wall Street fell overnight on fresh multi-decade highs in bond yields and a firmer oil price. Governor Bullock's tone at her post-decision press conference is likely to matter as much as the move itself for how far the tightening cycle still has to run.
Related post