CoreWeave (NASDAQ:CRWV): The cloud that refused to burst
CoreWeave’s blowout Q3 earnings and its pivot away from unsecured debt have calmed bond-market fears, but the relief hinges on an AI-compute shortage that won’t last forever.
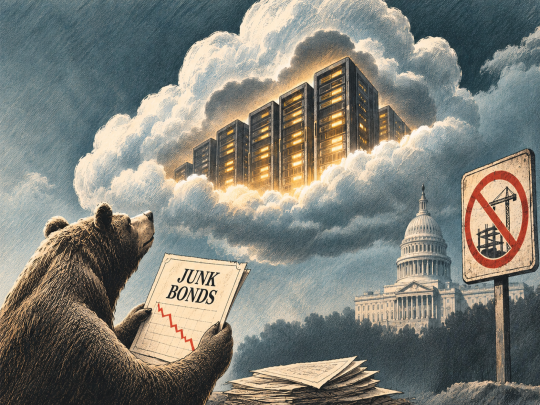
A blowout quarter and a pointed snub of the junk-bond market have silenced CoreWeave's doubters, for now. The reprieve rests on a shortage that will not last forever.
A month ago CoreWeave (NASDAQ:CRWV) was the name traders reached for when they wanted to short the artificial-intelligence boom. Credit-default swaps on the firm's debt, which pay out if it fails to honour its obligations, had blown past 11%, a level normally reserved for companies circling the drain. Its high-yield bonds were sinking, its shares had shed 25% in a month, and a Democratic sweep of America's midterm elections had put data centres, the firm's entire reason for being, squarely in the political crosshairs. The phrase doing the rounds on Wall Street was "doom cycle": costlier debt begets a weaker share price begets still costlier debt.
On November 10th the company delivered its rebuttal. Third-quarter revenue of $3.7bn rose 168% year on year and more than $1bn above the previous quarter, beating the top of the firm's own guidance. The market's verdict was swift. By Wednesday afternoon, the shares were up around 23% at just over $60, against a prior close of $48.73, on roughly three times their usual volume. Relief rippled through the whole ecosystem of "neoclouds", the specialist renters of AI computing power: Nebius (NASDAQ:NBIS) rose 19%, Applied Digital (NASDAQ:APLD) 9% and IREN (NASDAQ:IREN) 8%, putting the group on course to add more than $25bn in market value in a day. Nvidia (NASDAQ:NVDA), CoreWeave’s chip supplier and backer, climbed more than 4% after dropping nearly 10% at the start of the week on worries over its chief executive’s future. The Nasdaq gained 1.9%.
The numbers behind the bounce were striking. Adjusted operating income of $379m beat the top of the guided range ($200m to $260m) by about 46%. The adjusted operating margin has marched from roughly 1% in the first quarter to 5% in the second and above 10% in the third, hitting double digits a quarter ahead of plan. Adjusted EBITDA of $2.3bn, up 169% year on year, carried a 62% margin, the firm's best in five quarters; operating cash flow reached $2bn. The backlog of contracted revenue swelled to $132.5bn, up 138%, with more than half attached to contracts on which delivery begins by the end of this year. Guidance rose across the board: full-year revenue of $13bn to $13.3bn, adjusted operating income of $1.275bn to $1.375bn (26% higher at the midpoint), and an exit run-rate of $20bn to $21bn in annualised revenue.
Par for the course
Yet the quarter's most consequential disclosures concerned not the income statement but the balance-sheet arithmetic that had so alarmed creditors. CoreWeave's model is to borrow vast sums against long-term customer contracts, buy Nvidia's chips, and let contracted cash flows retire the debt before the hardware ages into obsolescence. Total borrowings now approach $47bn, and quarterly interest expense has reached $846m, up from $310m a year ago. That is why the firm still lost $709m in the quarter, six times its loss a year earlier, and why adjusted net profit is not expected until the first half of 2028.
The firm's answer was to redraw the map of its own debt. Michael Intrator, its co-founder and chief executive, told analysts that CoreWeave will not fund itself in the unsecured bond market at current yields, nor does it need to. That market, where investors lend against the parent company's general credit, is where the panic lived. The secured market, where lenders advance money against specific customer contracts, never flinched: those loans have traded around par throughout the storm, a point Mr Intrator pressed in a CNBC interview on Wednesday, arguing that the volatility in the firm's unsecured paper says little about the facilities that actually finance its build-out. The weighted average cost of debt ended the quarter at 7.9%, down 250 basis points year on year, and more than $4bn has already been repaid, including nearly half of the two most expensive facilities.
Customers, meanwhile, are increasingly doing the lenders' job. CoreWeave has collected prepayments on 70% of deals struck this year, in some cases for 100% of contract value upfront, and expects roughly $9bn in prepayments and deposits over the next three months alone. More than $3bn of that relates to re-contracting old infrastructure that is already fully paid off, cash that arrives with no debt service attached. Add $6.5bn of cash, restricted cash and marketable securities (of which about $4.1bn is unrestricted cash), nearly $5bn of undrawn loan capacity, and a new secured facility due within weeks that rating agencies have signalled will be high investment-grade, priced at an expected yield of 7% to 7.5% while funding over 90% of the associated capital spending, and the picture looks rather less apocalyptic. The firm expects to raise less than $5bn at the parent level through 2027, with EBITDA less interest set to more than double next year.
Scarcity value
Demand is the opposite of the problem bears predicted. "We are largely sold out through 2027," Mr Intrator told analysts, adding that qualified demand runs at ten times the firm's remaining 2027 capacity and that 2028 interest is already several multiples of capacity not yet formally offered for sale. Scarcity is feeding pricing power. The firm raised prices by about 25% in July, added another 10% later in the quarter, and reports further increases since. Long-term contracts now fetch $20m to $25m per megawatt per year; short-term capacity clears above $40m, with payback periods as short as six to eighteen months. Even previous-generation chips repriced 30% to 50% quarter on quarter, above their original contract rates.
The sleeper asset is the old fleet. Some 130,000 GPUs come off contract in 2027 and another 170,000 in 2028, all on kit fully amortised under the original loans. At today's prices those renewals represent nearly $4bn of annualised revenue in 2027, rising towards $10bn with 2028, requiring no new capital spending and sitting entirely outside the reported backlog. Management's framing of the cycle is conveniently symmetrical, but not obviously wrong:
"If the industry builds quickly, we grow with it. If supply is delayed, our installed paid-off fleet becomes more valuable," Mr Intrator said on the call.
A regulatory squeeze on new construction, in other words, would make existing compute scarcer and dearer, to the benefit of whoever already owns it outright.
Politics supplied the quarter's theatre. Voters approved restrictions on data centres in 40 of 41 ballot measures across ten states on November 3rd, and the incoming Democratic governors of Texas, Ohio and Georgia all favour some limits on new construction. J.P. Morgan Asset Management reckons projects from 2028 onwards are most exposed. Mr Intrator was unmoved, telling analysts the firm anticipates no impact from the "seismic regulatory shift" because the vast majority of its Texan power is online or fully permitted and under construction, categories the governor-elect, Gina Hinojosa, has indicated may proceed. The hedge is geography: of 4.6 gigawatts of contracted power, more than 1.3GW now sits abroad, across Canada, Europe, India and Indonesia. Shareholders got a gesture too. Mr Intrator told that he has shelved the trading plan under which he had sold 8.26m shares at an average of $96.14, some $794m in all, a sore point for investors nursing an 18% year-to-date loss even after the rally.
The bears' intermission
Scepticism has retreated rather than surrendered. Analysts at Bernstein called it about the best quarter anyone could have asked for, then warned that CoreWeave will be among the first and hardest hit when the shortage of AI computing capacity eases, since everything from $40m-per-megawatt pricing to the renewal windfall depends on scarcity persisting. Jim Chanos, a short-seller, still points to weak returns on capital. The macro backdrop is unhelpful: October's inflation print of 0.4% month on month has markets assigning roughly 90% odds to another Federal Reserve rate rise in December, no small matter for a firm guiding to $1.05bn to $1.15bn of interest expense next quarter and $37bn to $39bn of capital spending this year, implying growth of about 155%. SoftBank's $3.7bn writedown on data-centre equipment, disclosed the same day, was a timely reminder that even deep pockets can mistime this cycle.
What changed this week is narrower than the share price suggests, but real. CoreWeave showed it can fund its entire contracted backlog without touching a hostile unsecured market, that the lenders closest to its cash flows never lost faith, and that customers want its product badly enough to pay years in advance. The doom cycle required the secured market to crack next; it did not. The firm has, in effect, converted a solvency question into a cyclical one. When the compute shortage finally ends, the bears will get another hearing. Until then, the most heavily shorted balance-sheet in AI has bought itself something scarcer than GPUs: time.