The Wall Street Wrap: October 13, 2026
US stocks ended little changed on Tuesday as big bank earnings gave a mixed read, Johnson & Johnson dragged the Dow, and a Kospi plunge hit memory chips. Energy led the sectors, Bank of America took a $1.2 billion penalty, and inflation data arrives Wednesday.
Stocks end flat as big banks give a mixed read and Johnson & Johnson drags the Dow, South Korea's Kospi plunges more than 5%, and Bank of America takes a $1.2 billion penalty
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
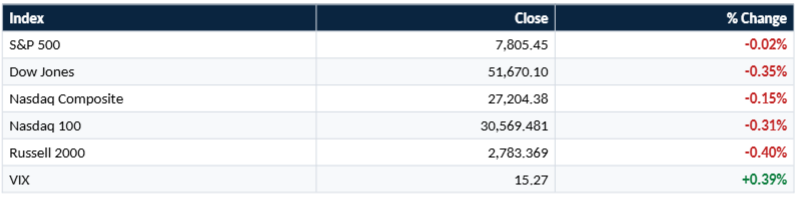
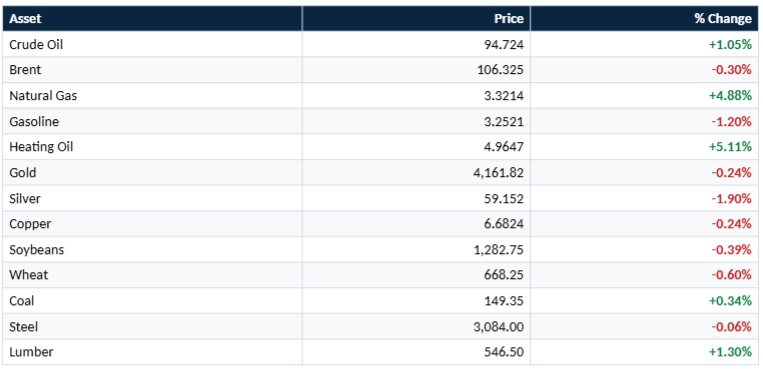
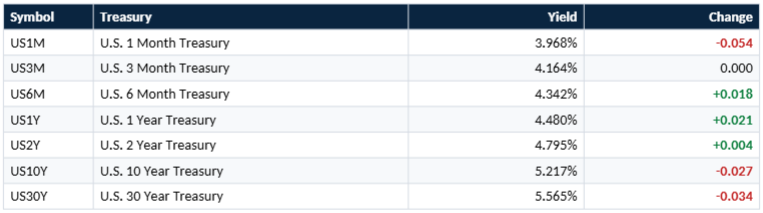
US stocks ended little changed on Tuesday as the first big bank results of the season gave a mixed read and a steep selloff in South Korea weighed on memory chipmakers. The S&P 500 slipped 0.02% to 7,805.45 and the Nasdaq Composite fell 0.15% to 27,204.38, while the Dow Jones Industrial Average lost 0.35% to 51,670.10 after trading more than 460 points higher at its peak, as Johnson & Johnson fell 5.73%. The Nasdaq 100 dropped 0.31% to 30,569.481, the Russell 2000 lost 0.40% to 2,783.369, and the VIX rose 0.39% to 15.27. JPMorgan Chase missed estimates but raised its income guidance, Wells Fargo fell about 3%, Goldman Sachs beat on a surge in equities trading, and Citigroup dropped 5.6%. The 10-year Treasury yield eased 2.7 basis points to 5.217% as the bond market reopened, while West Texas Intermediate settled at $94.14 and Brent at $105.69. Energy, communication services, and utilities led the sectors, while health care fell the most.
ANALYTICAL VIEW
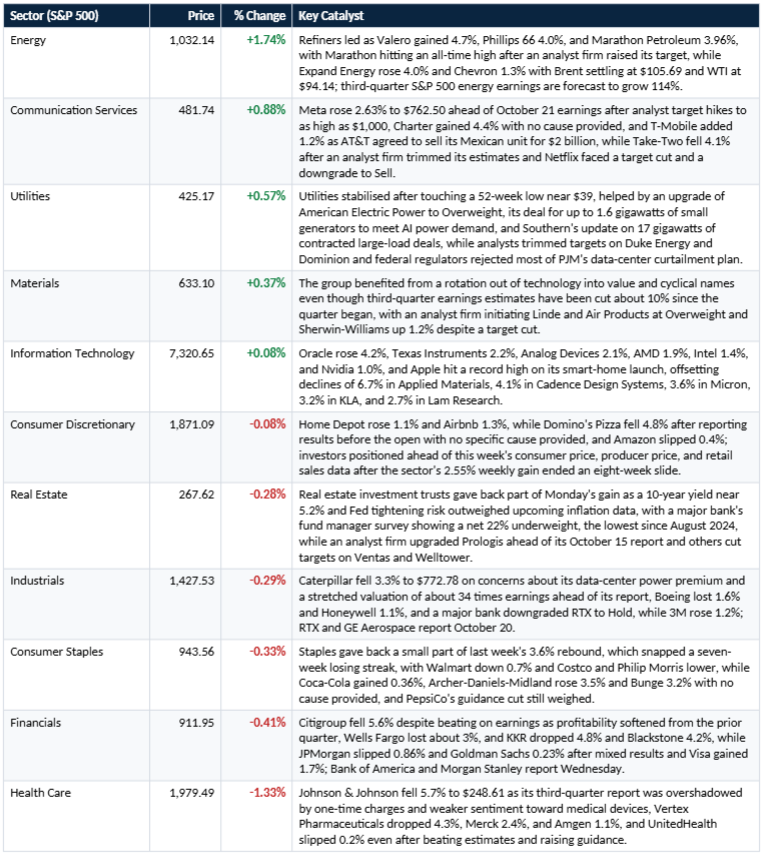
Another flat index close hid wide differences below the surface. Energy rose 1.74% as refiners surged, with Valero up 4.7%, Phillips 66 up 4.0%, and Marathon Petroleum up 3.96%, while communication services rose 0.88% and utilities 0.57%. Health care fell 1.33% as Johnson & Johnson dropped 5.7%, Vertex Pharmaceuticals 4.3%, and Merck 2.4%, and financials lost 0.41% as Citigroup fell 5.6%, KKR 4.8%, and Blackstone 4.2%. Technology edged up 0.08% because gains in Oracle at 4.2%, AMD at 1.9%, Intel at 1.4%, and Nvidia at 1.0% offset a 6.7% slide in Applied Materials, the worst performer in the S&P 500, and a 3.6% fall in Micron.
Rates and the Fed stayed in focus. The 10-year Treasury yield held near multi-decade highs at 5.217%, and two Fed presidents said on Tuesday that another rate hike is likely this year, after the central bank lifted its policy rate to a range of 3.75% to 4.00% last month. Consumer prices are due Wednesday, with the annual rate forecast to rise to 3.7% from 3.4%, and the International Monetary Fund nudged its 2026 global growth forecast up to 3.1% while warning that a sharp pullback in AI investment is the biggest downside risk. Analysts expect third-quarter S&P 500 profits to have grown by nearly 30%, though one chief investment officer noted that high expectations are a risk for banks and other companies this earnings season.
What could change the picture: Whether Wednesday's inflation report, forecast at 3.7%, and Bank of America's results after its $1.2 billion penalty confirm a Fed on a hiking path, and whether the Gulf conflict, now reaching Saudi Aramco's headquarters, keeps Brent above $105.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- CDW Corporation (NASDAQ:CDW): +5.711%
- Valero Energy Corporation (NYSE:VLO): +4.693%
- Charter Communications, Inc. (NASDAQ:CHTR): +4.362%
- Oracle Corporation (NYSE:ORCL): +4.229%
- Expand Energy Corporation (NASDAQ:EXE): +4.009%
Top 5 Decliners:
- Applied Materials, Inc. (NASDAQ:AMAT): -6.691%
- Johnson & Johnson (NYSE:JNJ): -5.733%
- Citigroup Inc. (NYSE:C): -5.602%
- Flex Ltd. (NASDAQ:FLEX): -5.425%
- Domino's Pizza, Inc. (NYSE:DPZ): -4.76%
Note: Valero and Expand Energy rose with oil and gas prices elevated, while Johnson & Johnson fell on one-time charges in its quarterly report and Citigroup on softer profitability; no specific cause was provided for the moves in CDW, Charter, Oracle, Applied Materials, Flex, or Domino's.
AFTER-HOURS MOVERS
Gainers:
- Brookdale Senior Living Inc. (NYSE:BKD), +4.64% after hours: Shares rose to $10.59 after the company completed the $157 million purchase of 17 communities and signed a definitive agreement to buy 30 leased communities from Welltower for $290 million. The deals are expected to cut 2027 cash rent by about $17.8 million and lift the owned share of consolidated units to nearly 80%, and the 30-community purchase is expected to close in the fourth quarter, funded with cash and non-recourse mortgage debt. The stock had closed 1.17% lower at $10.12.
- Generate Biomedicines, Inc. (NASDAQ:GENB), +4.45% after hours: Shares rose to $12.80 after the company announced a multi-target AI collaboration with Zealand Pharma on obesity and metabolic disease, with $30 million upfront and up to $35 million in early preclinical milestones for two programs. Total milestones could reach nearly $1.2 billion, plus tiered royalties and an option for a third program, with Generate leading research and Zealand taking over development and commercialization. The stock had closed 11.45% lower at $12.26, with no news tied to that drop in the sources.
- AZZ Inc. (NYSE:AZZ), +2.22% after hours: Shares rose to $140.20 after fiscal second-quarter results beat estimates and management raised full-year guidance, with adjusted earnings per share guidance lifted to $7.00 to $7.30 from $6.75 to $7.15 and revenue guidance to $1.825 billion to $1.875 billion. The company also completed its Seattle Galvanizing acquisition and bought back $20 million of stock, and it holds its earnings call Wednesday. The stock had closed 0.44% lower at $137.16.
Decliners:
- Bank of America Corporation (NYSE:BAC), -2.62% after hours: Shares fell to $52.55 on the penalty news detailed above, a day before the bank reports results before the open on Wednesday. The stock had closed 1.14% lower at $53.96.
- GitLab Inc. (NASDAQ:GTLB), -2.00% after hours: Shares fell to $50.91 with no company-specific news provided, extending a regular-session reversal in which the stock hit a fresh 52-week high of $57.89 before closing 7.25% lower at $51.95 on heavy volume. The decline followed a gain of roughly 184% over the past six months.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Big banks open earnings season with a mixed read as JPMorgan misses and Goldman Sachs beats. JPMorgan reported third-quarter earnings and revenue below estimates, though net interest income rose 13% and it raised its 2026 guidance for that measure, and its shares fell 0.9%. Goldman Sachs earned $17.01 a share against a consensus of $13.02 on a 72% jump in equities trading, yet its shares slipped 0.2%, while Wells Fargo lost about 3% on mixed results and Citigroup fell 5.6% despite beating on earnings. Investment banking fees held up at all four lenders, with JPMorgan's up 14% and Goldman Sachs' up 21% from a year earlier, but all four were lower than in the second quarter, and one chief investment officer said high expectations are a risk across the board this season.
Bank of America is hit with more than $1.2 billion in federal penalties a day before it reports earnings. The Treasury's financial crimes unit and the Office of the Comptroller of the Currency said the bank failed for years to report more than $5 billion in suspicious transactions and to fix long-running anti-money-laundering problems, including more than $1 billion tied to national security and other high-priority risks. The penalty is the third-largest in Treasury history, and the comptroller's share of $750 million is the largest the office has ever levied; the bank admitted it willfully violated the Bank Secrecy Act. Bank of America said it has invested billions in compliance and is far along in remediation, and the charge of about $0.17 per share, which is not tax-deductible, will be booked in third-quarter results due before the open Wednesday.
Chip stocks slide again on AI financing worries, and Anthropic is set to disclose its finances to investors. Applied Materials fell 6.7% and Micron 3.6% as memory shares sold off after South Korea's Kospi dropped more than 5% to its lowest level since July 31 on valuation concerns and growing competition from China, where CXMT plans to release a more powerful chip by year-end, while SK hynix lost 3%, Western Digital 1.6%, and the Nasdaq 100 fell 0.31%. The selloff extended worries about the durability of AI financing after Monday's warnings from chip chiefs that capital could be the industry's biggest constraint. Anthropic plans to disclose third-quarter financials for the first time at a meeting with institutional investors on Wednesday, according to two people familiar with the matter, as it prepares for what could be the largest initial public offering in history, with a listing reported for November.
AT&T agrees to sell its Mexican unit for $2 billion in cash. The buyer is a consortium owned equally by Grupo Televisa and Fintech Holdings, and the deal is expected to close in the first quarter of 2027, pending Mexican regulatory approvals. The unit, Mexico's second-largest mobile operator, had about 24.7 million subscribers as of December 2025 and reported 85.4 billion pesos of revenue for 2025. AT&T's chief executive said the company believes "the AI future will run on converged networks with dense fiber assets," as it sharpens its focus on domestic fiber and 5G.
Apple unveils a smart-home hub that makes Siri more personal, and its shares hit a record. The HomeView device draws on a personal search index stored on the user's iPhone, runs its own operating system on an A18 chip, and stores no private data on the hub itself, with Apple saying none of the data is used for marketing. It can recognise up to six voices and faces in a shared household and switch to each person's own information, a test of Apple's AI strategy as it tries to close the gap with Amazon and Google. The device reflects chief executive John Ternus' vision of the iPhone as an "intelligent personal hub."
Also today: Google released its Gemini 4 Argon model to developers and businesses worldwide, with launch pricing of $2 per million input tokens and $10 per million output tokens that doubles after November 30; OpenAI said a "sophisticated recording device" was hidden in one of its offices, that an employee was fired and arrested on October 9, and that it has no indication model weights, source code, or customer data were accessed; CVS Health agreed to pay $315 million to resolve Justice Department allegations that it unlawfully filled medically unnecessary opioid prescriptions, without admitting wrongdoing; US existing home sales rose 1.5% in September to a seasonally adjusted annual rate of 3.99 million, above the 3.95 million forecast, as the median price hit a record $417,500 for a September and the 30-year mortgage rate averaged 7.40% last week; short interest in JetBlue climbed to 30.5% of its float and in Alaska Air to 10.8% as fuel costs stay high; and a Wells Fargo survey showed a record-low share of real estate agents describing their market as friendly to sellers.
TOP STORIES: GLOBAL
Loud booms are heard near Saudi Aramco's headquarters as the Houthi war with Saudi Arabia escalates. Six sources said explosions were heard late Tuesday near the state oil company's headquarters in Dhahran, and one source with direct knowledge said the building was struck and on fire, though it was unclear whether by a direct hit or falling debris, with an evacuation order issued and no official comment from Aramco. The Saudi-led coalition said fragments of an intercepted missile fell on a residential area, as the Houthis have fired ballistic missiles and drones at key Saudi sites for a week, including four strikes on Riyadh's airport, one of which killed 13 people on Saturday. Earlier, Brent settled at $105.69, down 0.9%, and WTI at $94.14, up 0.43%, as investors weighed more Russian diesel, which one major bank estimated would lower wholesale diesel prices by only $1 to $2 a barrel for an extra 800,000 metric tons.
The IMF lifts its 2026 growth forecast to 3.1% but warns of risks from an AI correction and the Middle East war. The fund now sees global growth of 3.1% this year, up from 3.0% in July, and 3.4% in 2027, which assumes the Strait of Hormuz reopens by March, while a prolonged war that kept oil above $130 through the first quarter of 2027 would cut next year's growth by half a percentage point. A steep fall in AI investment could cut global output by 1.1% by 2028, including 1.8% in the US, though not enough to cause a global recession, and the fund's managing director likened the world economy to standing on one leg, the AI leg. The reports also urged governments to curb elevated debt, as rising bond yields eat into budgets.
Asia-Pacific markets fall as South Korea's Kospi plunges more than 5%. South Korea's Kospi dropped 5.46% and Japan's Nikkei 225 fell 1.82% to 67,777.52, while mainland China's CSI 300 closed 0.29% lower at 4,275.68 and Hong Kong's Hang Seng was down nearly 1% in its last hour of trade. Australia's S&P/ASX 200 was flat at 8,783.90.
European luxury's market value has fallen by about $350 billion this year. The top 10 European luxury groups have lost that much since January, with LVMH down more than 40%, and Monday's third-quarter sales miss from LVMH dented sector shares again on Tuesday. The combined market value of the four biggest luxury houses has nearly halved since around 2024, with Richemont, more focused on watches and jewellery, bucking the trend, while weakness in China remains the main concern and Hermes and Kering report third-quarter sales next week.
MANAGEMENT & FED SPEAK
Susan Collins, President, Federal Reserve Bank of Boston, on the rate outlook:
Collins said she backed last month's rate hike and expects it will be appropriate to "raise rates a bit further before the end of the year," though her view on timing will depend on how incoming data shape the outlook and the balance of risks. She called the most likely path one of healthy growth and a labor market near full employment, but said pressure from AI infrastructure investment, tariffs, and war-driven energy costs could complicate the return of inflation to 2%.
John Williams, President, Federal Reserve Bank of New York, on further rate hikes:
Williams said he still sees room for "one more rate hike" in 2026 but no reason at this time to expect more in 2027, while saying the economy is "not an economy that is overheating overall." He added that near-term price pressures reflect high energy prices tied to the Middle East war and tech investment, and that he expects inflation to come down quite a bit next year.
David Solomon, Chief Executive, Goldman Sachs, on succession and AI financing:
Solomon said "there is no succession transition or timeline underway at Goldman Sachs," pushing back on reports of a planned handover to the bank's president. He also warned that rising financing needs for AI infrastructure could pressure rates and affect "the returns and the viability of certain projects," adding that not every project will be received well.
Jamie Dimon, Chief Executive, JPMorgan Chase, on AI agents:
Dimon said the bank will not let outside AI agents operate inside the company because it is "too risky for clients and for JPMorgan," and that the bank is building tools to defend against misuse. "You don't want rogue agents," he said, adding that there could be thousands of them.
Charles Scharf, Chief Executive, Wells Fargo, on AI and consumer credit:
Scharf called the AI investment cycle "a complicated macroeconomic force in its own right," noting that demand for chips, networking, and power equipment continues to surge alongside risks from the leverage used to finance the build-out. He said the bank's underwriting recognizes that consumer credit conditions will weaken at some point, but "we do not see signs of this yet."
CORPORATE ACTIONS & EARNINGS CALENDAR
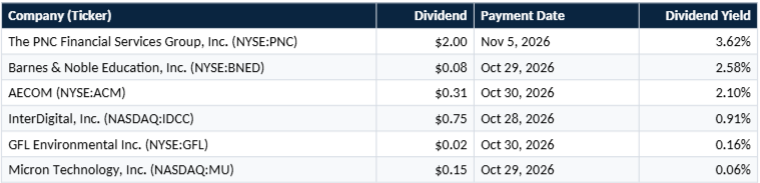
Top Ex-Dividend Companies for Wednesday, October 14:
Earnings Reported After the Close (Tuesday, October 13):

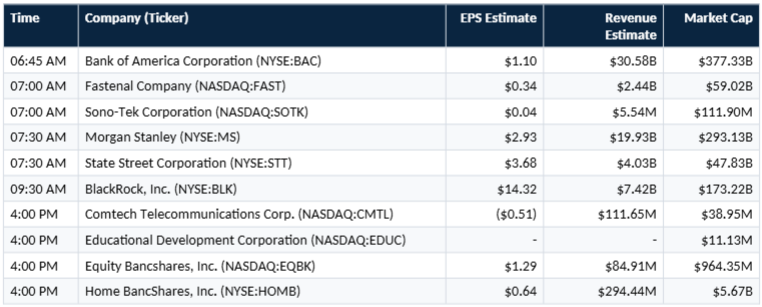
Upcoming Earnings (Wednesday, October 14):
Economic Calendar (Wednesday, October 14):
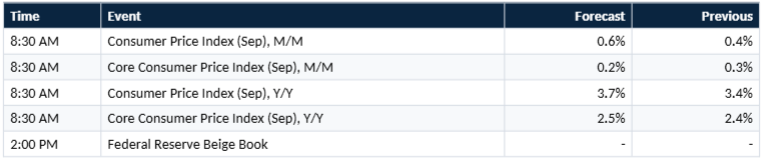
That's the wrap for today! Attention turns to Wednesday's September consumer price report, forecast at 3.7%, results from Bank of America, Morgan Stanley, and BlackRock, the Federal Reserve's Beige Book, and Anthropic's investor meeting, as investors test whether stocks can hold near record highs with the 10-year Treasury yield above 5.2% and Brent above $105.