The Wall Street Wrap: October 7, 2026
US stocks slipped on Wednesday as the 10-year Treasury yield touched 5.365%, its highest since April 2002, and Fed minutes showed most officials expect another rate hike by year-end without a timeline. The S&P 500 fell 0.22% and the Dow dropped 0.66%, while the average 30-year mortgage rate jumped to 7.49%. Wolfspeed surged after hours on a conditional $1.5 billion loan commitment, and India's central bank raised rates for the first time in nearly four years.
Stocks slip as the 10-year yield touches its highest level since 2002 and Fed minutes point to another hike; Wolfspeed jumps after hours on a conditional $1.5 billion loan commitment
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
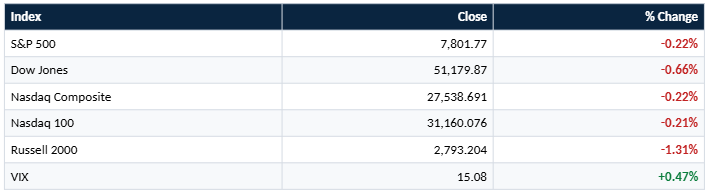
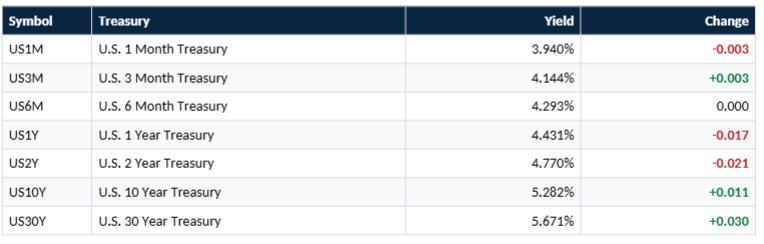
US stocks fell on Wednesday as pressure in the bond market pushed Treasury yields to levels not seen in more than two decades, and as minutes from the Federal Reserve's September meeting showed most officials expect another rate hike by year-end without saying when. The S&P 500 lost 0.22% to 7,801.77, the Dow Jones Industrial Average shed 341.41 points, or 0.66%, to 51,179.87, the Nasdaq Composite slipped 0.22% to 27,538.691, and the Nasdaq 100 eased 0.21% to 31,160.076. Small caps fared worst, with the Russell 2000 down 1.31%. The 10-year Treasury yield reached 5.365%, its highest since April 2002, before retreating after a $39 billion auction to settle near 5.28%. Health care was the only sector with a meaningful gain, while industrials, materials, and real estate fell the hardest.
ANALYTICAL VIEW
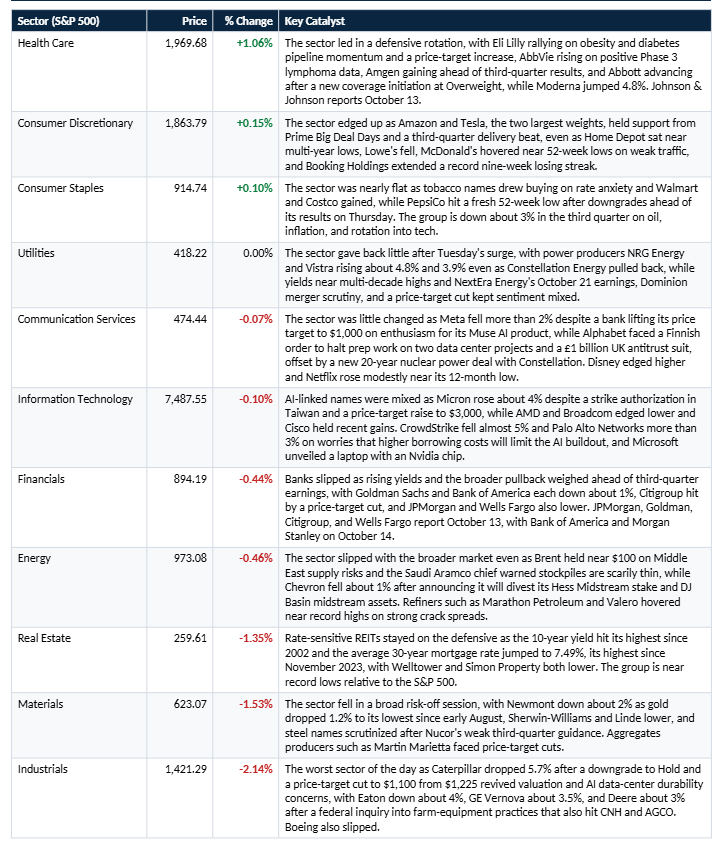
The headline index losses were modest, but the market underneath was more strained than they suggest. Seven of the 11 S&P 500 sectors fell, with industrials down 2.14%, materials down 1.53%, and real estate down 1.35%, while the Russell 2000 dropped 1.31% against a 0.21% decline in the Nasdaq 100. That split reflects where higher borrowing costs bite hardest: the 10-year yield has climbed about 60 basis points since the end of July while US crude has gained roughly 20% over the same stretch, and Wednesday's touch of 5.365% on the 10-year and 5.732% on the 30-year, both the highest since 2002, pressured banks, software, and rate-sensitive groups. One research head said the margin for error on earnings has narrowed at these yield levels, though profits could still carry the market higher and inflation expectations look well anchored.
The Fed minutes did little to settle the near-term debate. They confirmed that most participants see another increase as likely by year-end and that 16 of 18 forecasters expect one, yet they gave no timing, and markets still largely expect the central bank to hold when it meets October 28. Inflation worries are nonetheless building: a New York Fed survey showed year-ahead consumer inflation expectations rising to 3.9%, the highest since May 2023, the five-year breakeven rate sits near its highest of the year at 2.35%, and fed funds futures imply a policy rate of about 5.58% in five years, against a current target of 3.75% to 4%. Wednesday's strong 10-year auction, with dealers taking far less than usual and indirect bidders taking far more, helped stocks pare their losses, but it still cleared at the highest yield since 2000.
What could change the picture: Whether Thursday's $22 billion 30-year bond sale and Treasury buyback calm the long end after the 10-year's brush with 5.365%, and whether Fed speakers say anything about when the hike the minutes describe could come.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- NRG Energy, Inc. (NYSE:NRG): +4.836%
- Moderna, Inc. (NASDAQ:MRNA): +4.812%
- Micron Technology, Inc. (NASDAQ:MU): +4.059%
- Vistra Corp. (NYSE:VST): +3.875%
- Everpure, Inc. (NYSE:P): +3.709%
Top 5 Decliners:
- Strategy Inc (NASDAQ:MSTR): -6.794%
- Skydance Corporation (NYSE:SKYD): -6.716%
- Caterpillar Inc. (NYSE:CAT): -5.746%
- Nebius Group N.V. (NASDAQ:NBIS): -5.091%
- EMCOR Group, Inc. (NYSE:EME): -4.834%
Note: Power producers NRG Energy and Vistra, along with Moderna and Micron, led the gainers, while Caterpillar fell on a downgrade and price-target cut; no specific cause was provided for the drops in Strategy, Skydance, Nebius, or EMCOR.
AFTER-HOURS MOVERS
Gainers:
- Wolfspeed, Inc. (NYSE:WOLF), +27.99% after hours: Shares jumped to $40.15 after the silicon carbide chipmaker said it received a conditional loan commitment letter from the US Department of War's Office of Strategic Capital for up to $1.5 billion. The stock had closed 1.45% lower at $31.37.
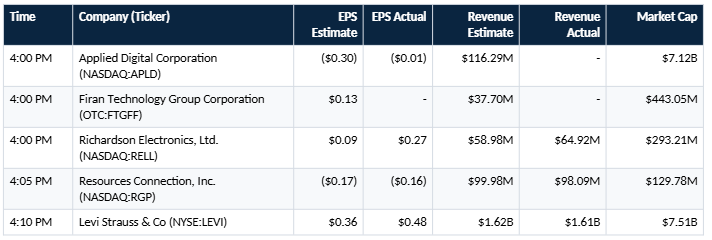
- Applied Digital Corporation (NASDAQ:APLD), +2.81% after hours: Shares rose to $24.48 after the data center operator reported an adjusted fiscal first-quarter loss of about $0.01 per share, far narrower than the loss of about $0.30 analysts expected. The company also announced its first international deal, up to 1 gigawatt of capacity in Finland, though no customer has been signed. The stock had closed 6.04% lower at $23.81.
Decliners:
- Resources Connection, Inc. (NASDAQ:RGP), -9.89% after hours: Shares fell to $3.37 after the consulting firm reported fiscal first-quarter revenue of $98.1 million, down from $120.2 million a year earlier and about 1.9% below the $99.98 million estimate. The GAAP net loss widened to $8.0 million, or $0.23 per share, from $2.4 million, or $0.07, and the adjusted loss of $0.16 per share compared with adjusted earnings of $0.03 a year ago, though it was slightly narrower than the $0.17 loss expected. On-Demand Talent revenue fell 13.2% to $38.6 million and Consulting revenue dropped 25.8% to $32.4 million, adjusted EBITDA was a loss of $3.6 million against a gain of $3.1 million, and the company ended the quarter with $61.2 million in cash after using $18.9 million in operations. The stock had closed 1.36% higher at $3.74.
- Levi Strauss & Co. (NYSE:LEVI), -1.29% after hours: Shares slipped to $19.26 after the denim maker reported adjusted third-quarter earnings of $0.48 per share against $0.36 expected, a figure that included a $0.16 benefit from tariff refunds, on revenue of $1.61 billion versus $1.62 billion expected. It raised its full-year adjusted earnings outlook to a range of $1.54 to $1.56 from $1.46 to $1.52, but lowered net revenue growth guidance to 7%, the bottom of its prior 7% to 7.5% range. Direct-to-consumer revenue rose 2% and wholesale rose 6%, and the company also disclosed a $100 million accelerated share repurchase. The stock had closed 4.97% lower at $19.51.
COMMODITIES & RATES
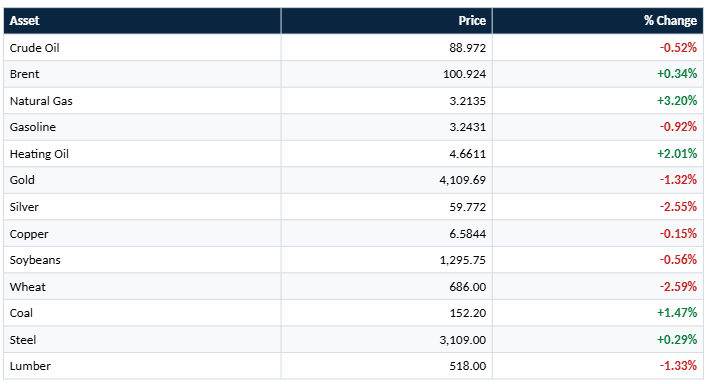
Note: EU Gas and Iron Ore CNY figures were provided but remain outside the standing commodities table per convention; available on request.
US TREASURY YIELDS
TOP STORIES: US
Fed minutes show most officials expect another rate hike by year-end, but give no hint of when. Most participants judged that a further increase would likely be appropriate by the end of the year, and 16 of the 18 officials who submitted forecasts penciled one in, though they stressed that each meeting would be decided on incoming data. The September 16 hike to a range of 3.75% to 4% was unanimous, and a few participants argued for planning for market stress even as Treasury markets were functioning smoothly. Staff also noted that part of the surge in yields may reflect uncertainty over the Treasury's buyback program. The next meetings are October 28 and December 9, and a New York Fed survey released the same day showed consumers' year-ahead inflation expectations rising to 3.9%, the highest since May 2023.
The 10-year Treasury yield touches its highest level since 2002 before a strong auction pulls it back. The 10-year reached 5.365% and the 30-year 5.732%, its highest since May 2002, before the Treasury's $39 billion 10-year auction drew indirect bidders for 80.3% of the sale against a 10-auction average of 72.4%, with dealers taking just 2.5% against a 9.4% average. The sale still cleared at 5.3%, the highest auction yield since 2000, and selling spread abroad, with the French 10-year up 12 basis points to 4.876% and the UK 10-year gilt up 7 basis points to 5.447%. The Treasury sells $22 billion of 30-year bonds on Thursday and will run a buyback of at least $4 billion in the 20-to-30-year range, double the usual size.
The average 30-year mortgage rate jumps 19 basis points to 7.49%, the highest since November 2023. The Mortgage Bankers Association said the rate rose in the week ended October 2, while mortgage applications fell 4.2% and overall volumes sit at their lowest since February 2025, down nearly 50% since January. Borrowing costs have climbed about 1.4 percentage points since the US and Israel began striking Iran in late February, tracking the rise in the 10-year yield. A poll found that the cost of living is the top issue for voters ahead of the November 3 elections, with President Trump's approval rating at a record low of 32%.
Microsoft unveils the Surface Laptop Ultra, a $2,599 machine built around an Nvidia AI chip. The 15-inch laptop is available to preorder now and ships October 16, with up to 128 gigabytes of unified memory and up to one petaflop of computing power, as Microsoft pushes to run more AI workloads on local devices rather than in the cloud. Microsoft also said Meta will bring a version of its Muse AI agent to Windows, and it is updating the Windows 11 setup experience to help users get started with open-source AI agent software.
Also today: SpaceX is in talks to raise $40 billion to buy Nvidia chips, made up of about $10 billion in bank loans and $30 billion in investment-grade debt, with Apollo expected to lead and PIMCO in discussions; gold fell to about $4,137 after touching a low of $4,091.2, its weakest since August 3, with gold miners on pace for their worst day since September 28 and silver hitting a low of $59.23; Anthropic launched Claude Haiku 5.5, its third model in the Claude 5.5 family in a month, priced at $0.10 per million input tokens and $0.50 per million output tokens for shorter prompts; and Richardson Electronics reported fiscal results with earnings of $0.27 per share against $0.09 expected, on revenue of $64.92 million versus $58.98 million.
TOP STORIES: GLOBAL
India's central bank raises rates for the first time in nearly four years and signals more to come. The Reserve Bank of India lifted its repo rate by 25 basis points to 5.5% in a unanimous vote and shifted its stance from neutral to "calibrated tightening," which the governor described as a milder form of tightening that depends on data. It raised its inflation forecast to 5.2% from 5% and its growth forecast by 40 basis points to 7.1%, with August consumer inflation at 4.82%, above the 4% target for a third straight month. The rupee hovered near 96.43 per dollar, close to record lows, and one bank economist expects another 50 to 75 basis points of hikes in the coming months.
IMF chief warns that high energy prices, record debt, and the AI boom threaten the global economy. Kristalina Georgieva said oil remains near $100 a barrel, with impaired refining capacity adding about another $100 per barrel in margins on products such as diesel, and that 10-year yields in the US, Germany, and Japan are at their highest since 2007, 2009, and 1996. Public debt is at its highest since World War Two and projected to exceed 100% of GDP before 2030, with advanced economies led by the US singled out as the worst offenders. She said a "prudently hawkish bias" may be appropriate for monetary policy, warned central banks against becoming "monetary cowboys" rescuing fiscal authorities, and said new IMF forecasts due at next week's Bangkok meetings will show the biggest downgrades in war-hit economies.
IEA members agree to speed up emergency oil releases and prioritize diesel, though the new volume is unclear. The agency said about 100 million barrels pledged under its March plan have yet to reach the market, and member governments hold roughly 1.1 billion barrels of public emergency stocks, including over 200 million barrels of diesel. One major bank's analysts said last week's G7 pledge of 100 million barrels appeared largely to accelerate volumes already promised, and Germany and the European Union said releases will stay within the amount approved in March. The IEA board will review the plans next week, and US crude settled 1.3% lower at $88.28 while Brent ended 0.4% lower at $100.20.
DeepSeek weighs expanding its funding round to as much as 100 billion yuan, double its original target. The Chinese AI startup, which began taking outside capital for the first time this year, is drawing strong interest from state-backed funds and corporate investors, and is seeking a valuation of about 500 billion yuan, or $75 billion. A separate report said it is close to securing at least 80 billion yuan, with Tencent and battery maker CATL among the largest backers, and is eyeing an IPO in early 2027. The round was initially expected to close by the end of August but has dragged on as some investors waver over the price.
MANAGEMENT & FED SPEAK
Scott Bessent, Secretary, US Treasury, on inflation and mortgage rates:
Bessent blamed high inflation and mortgage rates on the temporary shock from higher oil prices, saying both should come down once the Iran conflict ends and the energy market is well supplied.
Donald Trump, President, United States, on the Federal Reserve:
Asked about mortgage rates, Trump called Fed Chairman Kevin Warsh "great" but said the rest of the board "would like to see the country do badly," arguing that interest rates should come down.
Neel Kashkari, President, Federal Reserve Bank of Minneapolis, on the Treasury market:
Kashkari said he sees "every indication that the Treasury market is functioning fine," and that he sees no financial stability risk and no reason for the Fed to intervene.
Satya Nadella, CEO, Microsoft, on the future of computing:
Nadella said the company was starting to think about "the frontier ecosystem taking maybe slightly different contours" over the next two, five, and ten years, arguing that distributed computing will remain distributed.
Michelle Gass, CEO, Levi Strauss, on holiday trends:
Gass said she is "encouraged by the strength we are seeing heading into the holiday season," acknowledging that direct-to-consumer sales fell short of internal expectations in the quarter but are on track for mid-single-digit growth in the fourth.
CORPORATE ACTIONS & EARNINGS CALENDAR
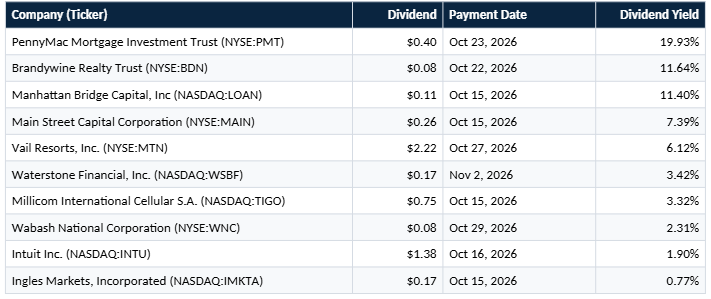
Top Ex-Dividend Companies for Thursday, October 8:
Earnings Reported After the Close (Wednesday, October 7):
Upcoming Earnings (Thursday, October 8):
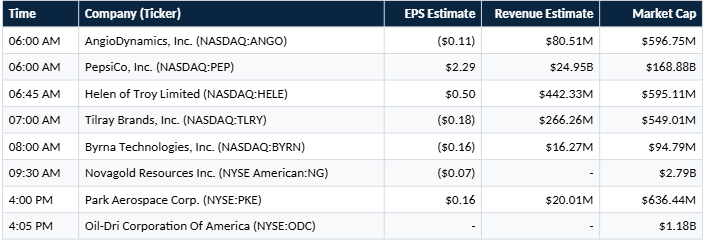
Economic Calendar (Thursday, October 8):
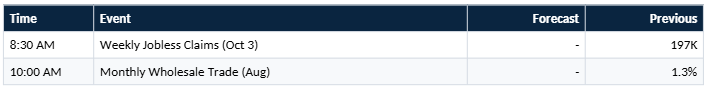
That's the wrap today! Attention turns to Thursday's $22 billion 30-year bond sale and Treasury buyback, PepsiCo's results before the open, and weekly jobless claims, all of which will test whether the long end can steady after touching its highest levels in more than two decades.