Wall Street Wrap: Pre-Market, November 20, 2026
U.S. stock futures slide on Friday, with Nasdaq 100 futures down 1.66%, as the AI selloff deepens after Anthropic's debut. Anthropic sinks toward its IPO price, AMD and Nvidia fall, and Intuit, Ross Stores and Belite Bio drop on guidance and FDA delays.
Futures slide as the AI selloff deepens, Anthropic sinks toward its IPO price, and Intuit, Ross Stores and Belite Bio fall on guidance and an FDA delay
Wall Street looks set for a sharply lower open on Friday, with Nasdaq 100 futures down 1.66%, as the AI selloff deepens a day after the record initial public offering of an artificial intelligence lab failed to steady stocks.
Futures Snapshot
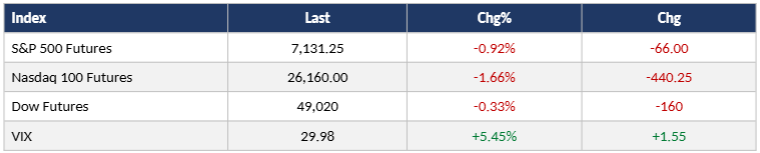
Nasdaq 100 futures are leading the declines, while S&P 500 futures are down 0.92%, Dow futures are down 0.33% and the VIX is up 5.45% at 29.98.
What's Driving the Open
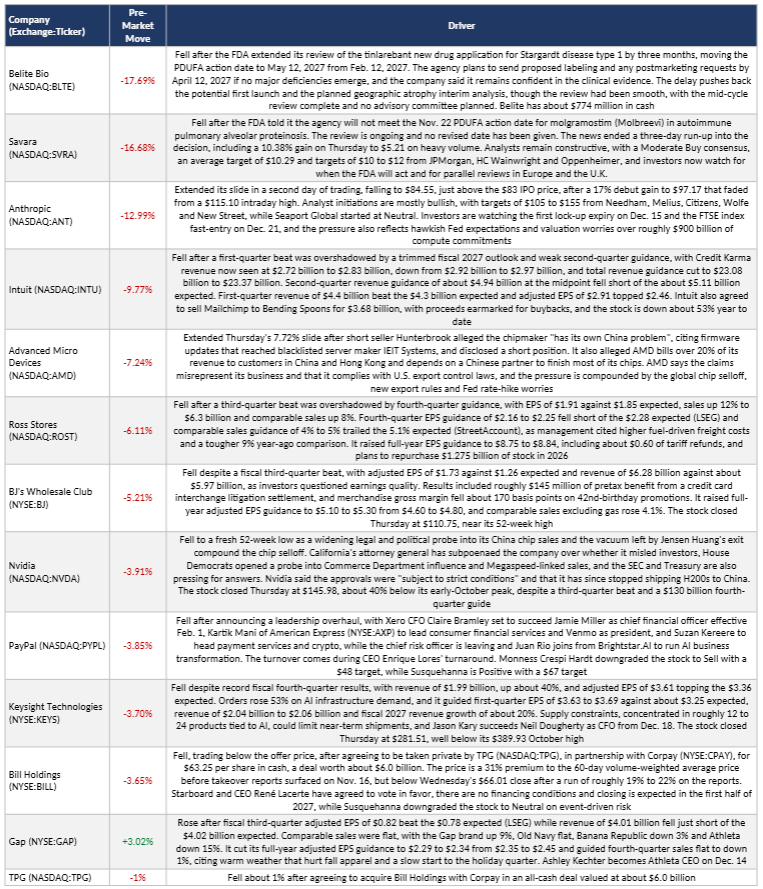
Nasdaq 100 futures are down 1.66%, S&P 500 futures 0.92% and Dow futures 0.33%, extending Thursday's rout, when the S&P 500 fell for a sixth straight session and the Dow closed below 50,000 for the first time since June. Anthropic (NASDAQ:ANT) is down 12.99% in pre-market trading at $84.55, just above its $83 offer price, a day after a 17% debut gain. Nvidia (NASDAQ:NVDA) is down 3.91% to its lowest in more than a year, Advanced Micro Devices (NASDAQ:AMD) is down 7.24% after a short seller's report on its China exposure, and Broadcom (NASDAQ:AVGO) and Micron Technology (NASDAQ:MU) were down 3% to 4% earlier.
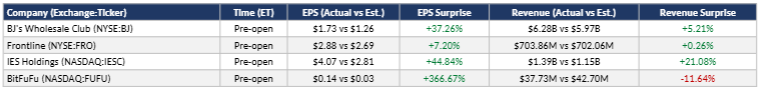
The VIX is near 30, and gold is trading near its lowest level in more than a year as traders price about a 99% chance of a quarter-point Fed rate hike in December. Fed Governor Christopher Waller, who has said a half-point increase is likely necessary, speaks later today, and longer-dated Treasury yields are lower as investors seek safe havens. Among earnings, Intuit (NASDAQ:INTU) is down 9.77% on a lower outlook, Ross Stores (NASDAQ:ROST) is down 6.11% on weak guidance and BJ's Wholesale Club (NYSE:BJ) is down 5.21%, while Gap (NYSE:GAP) is up 3.02%.
What could change the picture: Waller's speech, the final November University of Michigan sentiment reading and any dip-buying could swing risk appetite, with Deutsche Bank (NYSE:DB) strategist Binky Chadha calling the market "very oversold", while further selling in AI-linked stocks or shipping disruptions in the Gulf would add pressure.
Overnight Markets
Asia-Pacific markets ended sharply lower as a technology selloff swept the region, with Asian shares headed for their worst week since 2020. Japan's Nikkei 225 plunged 5.06% to 56,436.65 and the Topix dropped 3.88% to 3,674.22, South Korea's Kospi sank 5.21% to 4,869.96 and the Kosdaq shed 5.71% to 645.68, mainland China's CSI 300 slipped 0.76% to 3,954.57, Hong Kong's Hang Seng was down 2.24% in its last hour of trade and Australia's S&P/ASX 200 closed at 8,592.6. SoftBank Group fell 14.48%, its worst day since August 2024, on its exposure to OpenAI, while Tokyo Electron closed 7.06% lower, Lasertec 9.21% and Renesas Electronics 7.02%. In Europe, tech stocks fell more than 3%, with ASML (NASDAQ:ASML) down 5.8% and ASM International down 5.4%.
Pre-Market Movers
Earnings Before the Bell
Rates, FX & Crypto
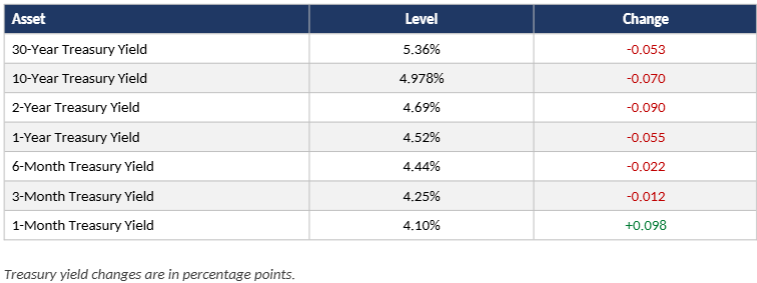
Treasury yields fell as the equity selloff drove investors into safe-haven assets, with the 10-year down 0.070 percentage points to 4.978%, heading for a fifth straight daily decline and its lowest level in about two weeks, the 2-year down 0.090 to 4.69% and the 30-year down 0.053 to 5.36%, while the 1-month yield rose 0.098 to 4.10%. Traders price about a 99% chance of a quarter-point Fed rate hike in December, according to CME FedWatch, and Waller, who said this week that a half-point increase is likely necessary, speaks later today. Philadelphia Fed President Anna Paulson also flagged inflation risks that could warrant another increase, and the dollar extended its rally on safe-haven demand.
Commodities
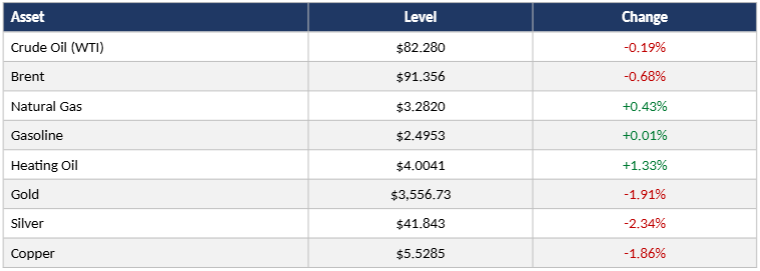
Oil is slightly lower, with WTI down 0.19% to $82.280 and Brent down 0.68% to $91.356, and both benchmarks are on track for a third straight weekly decline of roughly 6% for Brent and 8% for WTI as crude shipments through the Strait of Hormuz have returned to roughly pre-war levels. Gold fell 1.91% to $3,556.73, near its lowest level since September 2025 and down roughly 8% to 9% this week, its steepest weekly drop in eight months, as expectations of a December Fed hike lift the dollar and Treasury yields and some investors liquidate gold positions to cover losses elsewhere. Silver fell 2.34% and copper 1.86%, while heating oil rose 1.33%.
Key Levels & Catalysts Today
Economic data
- The final University of Michigan consumer sentiment reading for November is due, with a modest improvement expected after the preliminary figure rose to 51.0 from 48.0 in October, above the 48.0 expected.
- Waller speaks later in the session, and traders price about a 99% chance of a quarter-point Fed hike in December, according to CME FedWatch.
- The average U.S. gasoline price was $3.72 a gallon on Thursday, according to AAA, down from nearly $4.30 a month ago but above $3.09 a year ago.
Corporate
- Buckle (NYSE:BKE) and Moog (NYSE:MOG.A) hold earnings calls at 10 a.m. ET, with EPS of $0.87 and $2.68 expected, and Dynagas LNG Partners (NYSE:DLNG) holds its call at 4 p.m. ET with $0.34 expected.
- Anthropic trades for a second day after the underwriters exercised their full overallotment option.
Top Stories
The AI selloff deepens, leaving the Dow on course for its worst week since April 2025. Each of the major averages lost more than 2% on Thursday, leaving the Dow down 6.2% for the week and the S&P 500 and Nasdaq each down about 5%, their largest weekly pullbacks in more than a year. The S&P 500 is 8% below its Oct. 6 record, the technology sector has lost nearly 19% since then, and the index fell below its 200-day moving average this week for the first time since April. Concerns over heavy financing needs, the Democrats' midterm sweep and slower data-center expansion are weighing on AI stocks, even as global equity funds drew a net $59.23 billion in the week to Nov. 18, the most since mid-June, according to LSEG Lipper data. Nationwide chief market strategist Mark Hackett said "picking bottoms is difficult" when the market is so emotional.
Anthropic closes its record IPO as Big Tech leans on debt and equity markets to fund AI. Anthropic sold 1.127 billion shares at $83, including the full 147 million-share overallotment, for about $93.5 billion, of which about $91.6 billion went to the company, and a concurrent $26.0 billion private placement of Class N shares to chip and cloud partners brings the total to about $119.5 billion. Alphabet (NASDAQ:GOOGL) raised C$6 billion ($4.19 billion) in a four-tranche Canadian bond offering priced on Thursday and rated Aa2 by Moody's and AA+ by S&P, after lifting its equity offerings to $84.75 billion in June and reporting negative free cash flow of $9.1 billion in the third quarter against expectations near break-even. Meta (NASDAQ:META) announced plans in October for its largest-ever equity offerings, about $97.5 billion including roughly $37.5 billion of stock sales and up to $60 billion more through an at-the-market program.
Washington approved 879,000 advanced AI chips for Chinese buyers, House committee data show. The House Foreign Affairs Committee said the Commerce Department approved shipments of Nvidia H200 and AMD MI325X chips from December 2025 through May 2026, against requests for more than 3.4 million, with over 30% going to companies on the Pentagon's list of alleged Chinese military-backed firms, including 150,000 for Tencent. It is unclear how many approvals became actual shipments, and Commerce said its H200 licensing rests on a January rule that adds national security requirements. Committee Chair Brian Mast called the release the most detailed public disclosure in the history of the Export Control Reform Act, while former U.S. official Chris McGuire said he found the share going to military-linked firms astonishing.
Trump, Xi and Putin pledge more refined fuel supply after their first three-way summit. President Donald Trump, Chinese President Xi Jinping and Russian President Vladimir Putin issued identical statements after about 90 minutes of talks in Shenzhen, saying their countries plan to increase production and supply of refined petroleum products and affirming the importance of stable energy flows. They also reaffirmed that a nuclear war cannot be won and must never be fought, committed to a dialogue on reducing nuclear risks and called for reform of the United Nations, and said the International Criminal Court must not abuse its jurisdiction. The statements were brief and did not mention Russia's war in Ukraine or the U.S. war with Iran, and Trump said the three nuclear powers are "uniquely positioned" to reduce arsenals.
Oil heads for a third weekly decline even as mines hit tankers in Hormuz and Houthis fire at Riyadh. Middle East crude exports have stayed strong, but Iran's Revolutionary Guards Navy said in a statement carried by state media that two tankers hit naval mines in the strait and are burning, and UOB analysts said attacks on tankers are running at roughly one incident per day in November. The Iran-aligned Houthis also fired missiles at Riyadh, while OPEC+ ministers meet on Nov. 29 to decide their 2027 output policy. The International Energy Agency said the conflict has caused the biggest-ever disruption to global oil and gas trade and could cut world oil demand by more than 4% by 2035 if governments accelerate electrification, and Ukrainian drone attacks have cut Russian refineries' combined crude processing by 45% since late October.
Eyes on Waller's speech and the Michigan sentiment reading later Friday, on Anthropic's second session as a public company, and on whether chipmakers stabilize after a week that has left the Dow on course for its worst performance since April 2025.
.png)