Why Did BlackRock (NYSE: BLK) Adjusted EPS Jump 38%?
The world's biggest asset manager gathered $205 billion in a single quarter. The harder question is how much of the profit growth can be repeated.
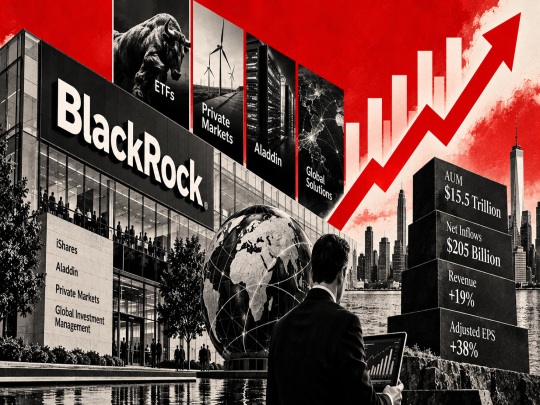
BlackRock, Inc. (NYSE: BLK) reported third-quarter 2026 results on Wednesday, October 14, 2026, and the headline numbers were strong on every measure. Clients added $205 billion of net inflows, taking assets under management to $15.5 trillion, up 15% from a year ago. Revenue rose 19% to $7.75 billion. Adjusted earnings per share climbed 38% to $15.93, while GAAP earnings per share rose 25% to $10.57.
The gap between those two profit figures is where the real story lies. For retail investors asking why BlackRock stock is in focus after earnings, this article sets out the key takeaways, the competitive moat and the questions about earnings quality that deserve attention.
Key takeaways for investors in BlackRock (NYSE: BLK)
- Growth came from clients, not just markets. Over the last twelve months BlackRock gathered $869 billion of net inflows, equal to 10% organic base fee growth. In the third quarter alone the annualized rate was 11%. Markets were actually a drag in the quarter, subtracting about $60 billion of assets, led by a $117 billion fall in fixed income values. Even so, AUM grew by $144 billion from June, because net inflows of $205 billion more than offset it.
- GAAP and adjusted profit tell different stories. GAAP diluted EPS of $10.57 sits well below adjusted EPS of $15.93. Most of the difference is noncash. The largest item is a $564 million pre-tax charge for the change in fair value of contingent consideration tied to the GIP and HPS acquisitions, which BlackRock says is affected by its own share price at period end. Amortization of intangibles and acquisition-related costs make up the rest. These are legitimate reasons to adjust, but investors should watch both numbers.
- Operating leverage is real, but performance fees helped. Revenue grew 19% while employee compensation grew only about 3.5%. Adjusted operating margin reached 47.8%, from 44.6% a year ago. However, performance fees were $630 million, double the $305 million of the prior quarter. BlackRock attributes the rise largely to a single hedge fund whose annual measurement period ends in the third quarter. That makes it a poor guide to the next quarter.
- Nonoperating income flattered EPS growth. Adjusted EPS rose 38%, faster than the 27% rise in adjusted operating income. The reason is that adjusted nonoperating income swung from a loss of $106 million a year ago to a gain of $127 million, including noncash gains of roughly $22 million on Circle and $80 million on Securitize. Investment gains are volatile by nature.
- Capital return continues, at a measured pace. BlackRock repurchased $550 million of shares and paid a quarterly dividend of $5.73 per share, up from $5.21 a year earlier. Shares outstanding including Subco Units fell by about one million year on year. The buyback equals roughly a fifth of adjusted net income, so acquisitions and investment remain the priority.
Where the growth is coming from
The flow picture is unusually broad. iShares exchange-traded funds attracted $135 billion, active strategies took in $66 billion, led by fixed income and systematic equity, and cash management added $31 billion. Institutional index mandates were the exception, with outflows of $27 billion. By region, the Americas contributed $125 billion, EMEA $31 billion and Asia Pacific $19 billion.
The year-to-date picture reinforces this. Long-term net inflows reached $510 billion in nine months, of which ETFs supplied $444 billion and the Americas $400 billion. Asia Pacific contributed only $10 billion so far in 2026, a reminder that the growth story is still heavily weighted to North America and that the international platforms are an opportunity as much as a strength.
Private markets deserve special attention. They hold just 2% of AUM yet generate 11% of base fees, so every dollar that flows into infrastructure or private credit is worth far more than a dollar in an index fund. Private markets drew $15 billion of net inflows in the quarter, and the company's AI Infrastructure Partnership made its first deployment. Technology services and subscription revenue, driven by the Aladdin platform, rose 14% to $588 million, with annual contract value up 12%.
How BlackRock makes its money, in plain terms
For newer investors, it helps to see where the revenue comes from. Base fees and securities lending, charged as a small percentage of assets, produced $6.04 billion of the $7.75 billion total, up from $5.05 billion a year earlier. Because the fee is a percentage of assets, revenue rises when clients add money and when markets rise, which is why inflows and market levels both matter.
The rest is more variable. Performance fees, earned when funds beat targets, brought in $630 million. Technology services and subscription revenue, mostly Aladdin, added $588 million, and distribution fees added $414 million. The most dependable layer is the base fee, and the most unpredictable is performance fees, which is why a quarter with double the usual amount should be treated with caution.
The competitive moat: why BlackRock is hard to dislodge
BlackRock's moat has four layers. The first is scale. With $6.4 trillion in ETF assets, iShares earns 46% of the company's base fees, and scale lets it price competitively while still earning healthy margins. The second is technology. Aladdin gives clients risk management and portfolio tools, creating switching costs that pure asset managers cannot match, and subscription revenue is steady rather than market driven.
The third layer is investment performance. Systematic equity strategies beat their benchmarks or peer medians on 92% of assets over one year, 93% over three years and 95% over five years. Index funds tracked their benchmarks within tolerance on 98% to 100% of fixed income assets. The fourth is the push into private markets through the GIP, Preqin and HPS transactions, which broadens what the firm can offer large pension and sovereign clients. Together these create a platform that clients can use for investing, financing and technology in one relationship.
The forensic view: risks the market should weigh
Market sensitivity is the first risk. Fee revenue follows average AUM, which rose 19% over the year. A sustained market fall would reverse part of that quickly. The second is the quality of flows, since institutional index clients have withdrawn $104 billion this year, which shows that fee pressure and rebalancing remain live issues.
Third, GAAP operating margin was flat at 30.0% and the GAAP effective tax rate rose to 29.4% from 25.2%. The release notes that the contingent consideration adjustments are primarily not deductible, which likely contributes to the higher rate. Finally, integrating three large acquisitions carries execution risk, and the contingent consideration charge will keep moving with the share price.
What to watch next
Management says the fourth quarter is seasonally the strongest and describes accelerating momentum. Investors should watch whether performance fees normalize, whether private markets fundraising keeps pace, how Aladdin contract value grows and whether institutional index outflows narrow.
The central question is whether BlackRock can keep turning scale into rising margins without relying on market gains. The first nine months of 2026, with $527 billion of net inflows, suggest it can, though the next market downturn will be the real test.
All figures are drawn from BlackRock's third-quarter 2026 earnings release. Please verify against official filings before making decisions.
This article is for information only and is not investment advice.