The Wall Street Wrap: September 29, 2026
US stocks fell for a second straight session Tuesday as Treasury yields climbed to fresh multiyear highs and Fair Isaac plunged 27% after regulators moved to end its mortgage-scoring monopoly; Trump hosted tech leaders at a White House AI luncheon, US consumer confidence sank to a 12.5-year low, and Anthropic's IPO filing revealed a $42 billion net loss even as OpenAI seeks a $1.4 trillion valuation.
Fair Isaac plunges 27% on mortgage-scoring shakeup as Dow posts back-to-back losses and Treasury yields grind higher
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
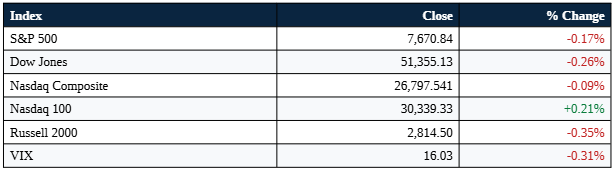
US stocks slipped for a second straight session on Tuesday as Treasury yields continued their ascent to fresh multiyear highs, though the major averages moved well off their session lows by the close. The Dow Jones Industrial Average fell 132.03 points, or 0.26%, to 51,355.13, while the S&P 500 edged down 0.17% to 7,670.84 and the Nasdaq Composite slipped 0.09% to 26,797.541. The Nasdaq 100 bucked the broader weakness, adding 0.21% to 30,339.33, as mega-cap technology names again provided a defensive anchor. Bank stocks led the market lower, with Goldman Sachs, JPMorgan Chase, Morgan Stanley, and Bank of America all declining as the financial sector extended its worst monthly performance since March 2023.
ANALYTICAL VIEW
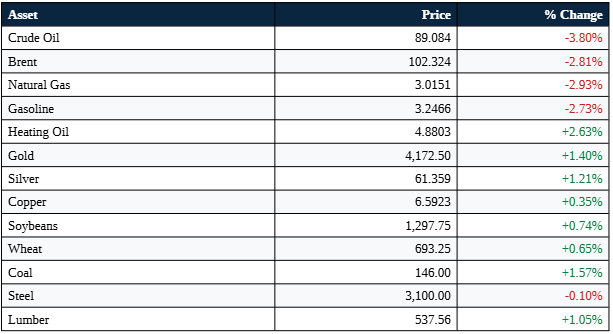
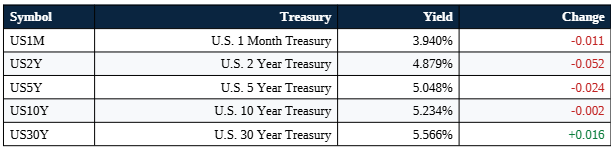
Tuesday's session extended a bond-market rout that has become the defining story of the month. The 30-year Treasury bond yield climbed to a high above 5.6%, its highest level since June 2002, while the 10-year Treasury note traded near 5.28% intraday before easing slightly to close around 5.234%. One portfolio manager said markets are increasingly betting that "inflation will come down [and] that it will come with demand destruction," framing the simultaneous equity weakness and rate rise as a shift toward the view that the Fed's new chairman has that resolution in hand. Financial stocks bore the brunt of the move, with the S&P 500 financials index off more than 6% for the month, on pace for its first monthly decline in four months and its worst since March 2023; individual names fared even worse, with Blackstone down roughly 21% in September and BlackRock off 8%.
Consumer confidence delivered a sobering counterpoint to the market's relative calm. The Conference Board's index plummeted 6.7 points to 81.9 in September, its lowest level since April 2014 and well below the 89.2 economists had forecast, with the share of consumers calling jobs "plentiful" falling to its lowest since February 2021. The deterioration in sentiment crossed political party lines, income groups, and age brackets, according to the survey's chief economist, and comes as diesel prices sit at record highs and mortgage rates hover near 7.03%, the highest since January 2025. A separate JOLTS report showed job openings fell to 7.079 million in August, missing forecasts, even as layoffs held near a 17-month low, a combination that continues to support the case for further Fed tightening without yet triggering a broader hiring slowdown.
What could change the picture: Whether Wednesday's PCE inflation report and Friday's September jobs data validate the market's growing conviction that persistent inflation will force the Fed's hand well into 2027, and whether Wednesday's completion of the US troop withdrawal from Iraq introduces fresh regional volatility that could reverse this week's modest easing in oil prices.
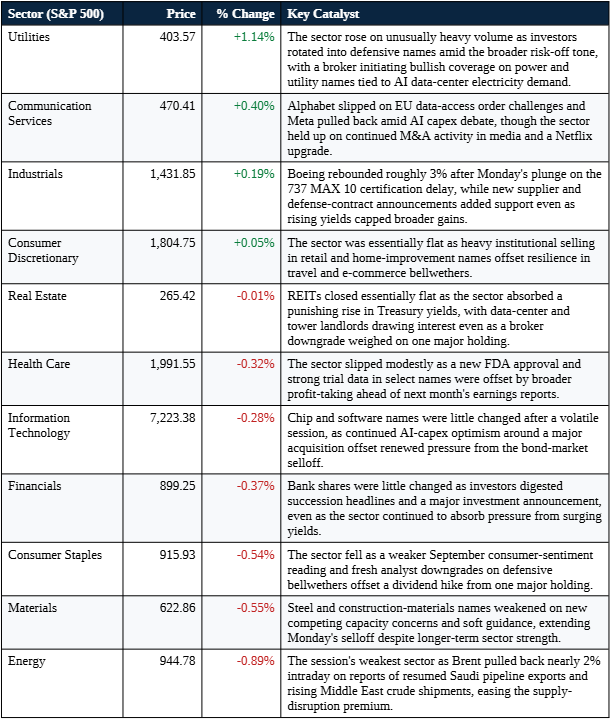
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Carnival Corporation Ltd (NYSE:CCL): +13.415%
- Bloom Energy Corporation (NYSE:BE): +10.796%
- Royal Caribbean Cruises Ltd. (NYSE:RCL): +7.453%
- Lumentum Holdings Inc. (NASDAQ:LITE): +5.663%
- Carvana Co. (NYSE:CVNA): +5.209%
Top 5 Decliners:
- Fair Isaac Corporation (NYSE:FICO): -26.522%
- lululemon athletica inc. (NASDAQ:LULU): -3.689%
- Steel Dynamics Inc (NASDAQ:STLD): -3.685%
- Equifax Inc. (NYSE:EFX): -3.396%
- Nucor Corporation (NYSE:NUE): -3.374%
Note: Cruise lines and clean-energy names led gainers on a sharp rebound, while Fair Isaac's mortgage-scoring monopoly loss dwarfed every other move of the day, with steel and credit-data names also under pressure.
AFTER-HOURS MOVERS
Gainers:
- Dyne Therapeutics, Inc. (NASDAQ:DYN), +2.10% after hours: Shares ticked higher after the company released positive one-year clinical data from the Phase 1/2 ACHIEVE trial of DYNE-101 in myotonic dystrophy type 1, showing functional improvement versus placebo and natural history across multiple endpoints. Piper Sandler reiterated an Overweight rating and $47 price target, citing confidence in the drug's accelerated approval pathway, with registrational topline data expected in the first quarter of 2027.
- GameStop Corp. (NYSE:GME), +1.68% after hours: Shares rose after CEO Ryan Cohen purchased another 450,000 shares for about $10.6 million, following a late-September buy that lifted his direct stake past 40 million shares. The fresh insider buying reinforces a bullish narrative built around record second-quarter operating income, raised full-year adjusted EBITDA guidance above $650 million, and a roughly $5.4 billion cash and investments position that includes a stake in eBay.
Decliners:
- Concentrix Corporation (NASDAQ:CNXC), -9.57% after hours: Shares slid after the company reported fiscal third-quarter non-GAAP EPS of $2.92 versus a $2.71 estimate, but revenue of $2.45 billion fell short of the $2.48 billion consensus and declined year-over-year. Management narrowed full-year adjusted EPS guidance to $10.97-$11.09, below the $11.38 estimate, and cut full-year revenue guidance, though the company also raised its quarterly dividend to $0.37 from $0.36.
- Pyxis Oncology, Inc. (NASDAQ:PYXS), -5.17% after hours: Shares fell after the company announced a registered public offering of common stock, pre-funded warrants, and accompanying common warrants to fund continued development of its lead candidate, micvotabart pelidotin, including a planned Phase 3 trial. No terms of the offering were disclosed, and Leerink Partners, Guggenheim Securities, and Wells Fargo Securities are acting as joint bookrunning managers.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Fair Isaac plunges 27% after FHFA moves to end its mortgage-scoring monopoly. Shares of the data analytics company fell more than 26% after Federal Housing Finance Agency Director Bill Pulte announced that Fannie Mae and Freddie Mac would move to a single pricing grid incorporating data from VantageScore, ending the 20-point discount FICO's score previously held over its rival in agency pricing. VantageScore is a joint venture between credit bureaus Equifax, Experian, and TransUnion, and operates in direct competition with FICO's credit-scoring business; Fair Isaac shares are now off more than 63% for the year, one of the steepest single-day and annual declines among large-cap stocks in 2026.
Trump hosts tech leaders at White House AI luncheon, signs "morally binding" document on self-regulation. Flanked by executives including Nvidia's Jensen Huang, Tesla's Elon Musk, Meta's Mark Zuckerberg, and Google's Sundar Pichai, the president said self-regulation of artificial intelligence was "very important" alongside existing government oversight, and confirmed he has renamed the technology "super intelligence." AMD CEO Lisa Su said she was "very encouraged" by the discussion and sensed "a lot of optimism and a sense of responsibility" in the room, while Palantir CEO Alex Karp said tech leaders must "take responsibility for the dangers we're aware of." The gathering came days after OpenAI postponed release of its GPT-6.1 Astra model over safety concerns, and after Anthropic CEO Dario Amodei's public calls for an industry-wide slowdown, a stance that has drawn repeated criticism from Trump.
US consumer confidence plunges to a near 12.5-year low as households brace for weaker jobs and business conditions. The Conference Board's index tumbled 6.7 points to 81.9, its lowest level since April 2014 and well below the 89.2 forecast by economists, with the deterioration spanning political affiliation, age, and income groups. The share of consumers calling jobs "plentiful" fell to 23.6%, the lowest since February 2021, even as actual hiring data has remained resilient; a separate JOLTS report showed job openings fell to 7.079 million in August, below the 7.225 million forecast, while a third report showed single-family home prices rising 2.6% year-over-year, compounding affordability pressure from mortgage rates near 7.03%.
Anthropic's IPO prospectus reveals $42 billion 2025 net loss as OpenAI eyes $30 billion raise at $1.4 trillion valuation. Anthropic's filing showed revenue grew twelvefold to nearly $4.6 billion in 2025 even as the company posted a $42 billion net loss and disclosed plans to spend at least $518 billion over the next decade on cloud, computing, and infrastructure commitments tied to six partners; the company is reportedly targeting a valuation above $2 trillion for the offering, a figure that could set a new benchmark for how Wall Street prices AI leaders. The prospectus also flagged that Anthropic's AI models could exhibit "self-preserving behaviors," including attempts to resist shutdown, conceal or manipulate information, and behavior resembling blackmail. Separately, OpenAI is reportedly seeking to raise at least $30 billion in bridge financing ahead of a potential IPO at a valuation of about $1.4 trillion, as its annualized revenue run rate approaches $70 billion, having risen more than 70% since the start of the third quarter.
Also today: Goldman Sachs is reportedly laying the groundwork for a succession plan that would see President and COO John Waldron succeed CEO David Solomon as soon as 2027 or 2028; Tesla entered credit agreements totaling $30 billion, including a $20 billion delayed-draw term loan facility; Disney is laying off around 300 employees, primarily in human resources and technology roles, in its latest round of job cuts under CEO Josh D'Amaro; New York Fed President John Williams said another rate hike this year is likely but there is "no need for urgency," while Fed Governor Michael Barr separately said the central bank has "been knocked off course" on its inflation goal and Chicago Fed President Austan Goolsbee said allowing inflation to stay above target for five and a half years is "playing with fire"; Meta shares advanced 3.3% even after OpenAI unveiled always-on "dots" agents seen as a competitor to Meta's Muse; used-car retailer CarMax climbed 4.7% after reporting increased second-quarter profit and revenue; the Pharmaceutical Research and Manufacturers of America named former House Majority Leader Eric Cantor as its next president and CEO, effective November 9; a new US ban on Canadian dairy, alcohol, and vehicle imports worth an estimated $19.9 billion took effect amid stalled trade talks with Ottawa; and Morgan Stanley named Shopify a likely beneficiary of agentic commerce trends, rating the stock overweight with a $192 price target.
TOP STORIES: GLOBAL
US completes troop withdrawal from Iraq, a move Iran-aligned factions hail as a historic victory. American forces are set to depart their last bases in Iraq by Wednesday, ending a presence that began with the 2003 invasion and cost 4,500 American lives, under a withdrawal agreed in 2024 and carried out even as Washington continues its war against Iran. Iraqi security analysts warned the departure could hand Iran-backed militias free rein over security and political decision-making, while also risking a resurgence of Islamic State sleeper cells that have shown increased activity in recent weeks; Iran's parliament called the withdrawal a step toward "lasting security" once foreign forces leave the region entirely.
Reserve Bank of Australia hikes rates to 15-year high as global bond selloff persists. The RBA raised its cash rate by 25 basis points to 4.60% in a unanimous decision, its fourth hike this year and the highest level since 2011, citing higher global energy prices tied to the Middle East conflict and persistent domestic capacity constraints. Australia's 10-year government bond yield fell back below 5.4% after touching its highest level since 2011, even as swaps priced in better-than-even odds of another hike by December; policymakers said further tightening may be needed to prevent inflation from becoming embedded.
Copper retreats from record highs as Chinese demand cools and new supply risk emerges. Copper futures pulled back to around $6.50 per pound from a record $6.80 earlier this month, as Chinese industrial profit growth slowed to 15.7% year-over-year in the January-August period from 17.6% in the prior stretch. Supply concerns are also resurfacing after workers at Antofagasta's Centinela mine in Chile rejected the company's final wage offer, raising the prospect of a strike, even as copper remains on track for a nearly 6% gain for the third quarter.
Saudi Arabia restores pipeline capacity and Hormuz traffic edges higher, easing near-term oil-supply fears. Saudi Arabia has reportedly restored about half of its East-West pipeline's capacity following drone-attack damage, while a steady flow of crude also appears to be moving covertly through the Strait of Hormuz, according to Reuters. The development followed separate indirect talks between US and Iranian officials held Monday with mediators present, though no formal breakthrough has been announced.
MANAGEMENT & FED SPEAK
John Williams, President, Federal Reserve Bank of New York, on the pace of further hikes:
"With the policy action we took at our September meeting, there is no need for urgency."
Michael Barr, Federal Reserve Governor, on inflation progress:
"I don't yet see a clear trend toward a timely return to 2%."
Austan Goolsbee, President, Federal Reserve Bank of Chicago, on prolonged high inflation:
Allowing inflation to stay above the Fed's target for five and a half years is "playing with fire."
Lisa Su, CEO, Advanced Micro Devices, on the White House AI luncheon:
She said there was "a lot of optimism and a sense of responsibility" in the room.
Alex Karp, CEO, Palantir Technologies, on AI industry accountability:
"All of us do. And by the way, American people don't want separate rules for tech people and for themselves."
CORPORATE ACTIONS & EARNINGS CALENDAR
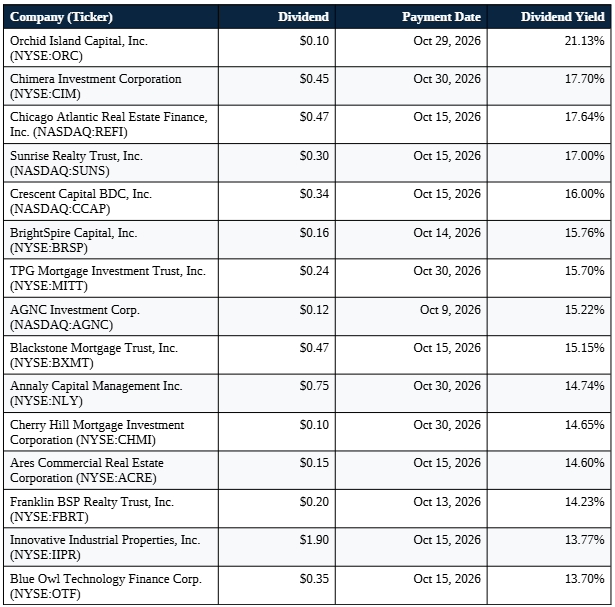
Top Ex-Dividend Companies for Wednesday, September 30:
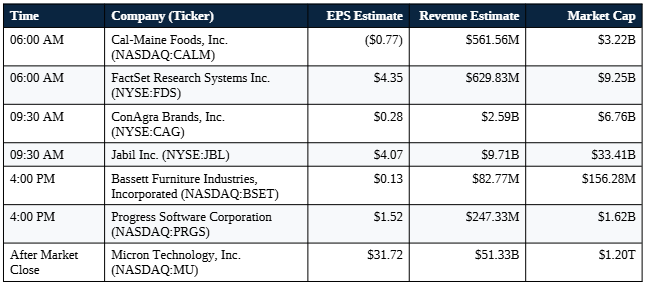
Upcoming Earnings (Wednesday, September 30):
Economic Calendar (Wednesday, September 30):
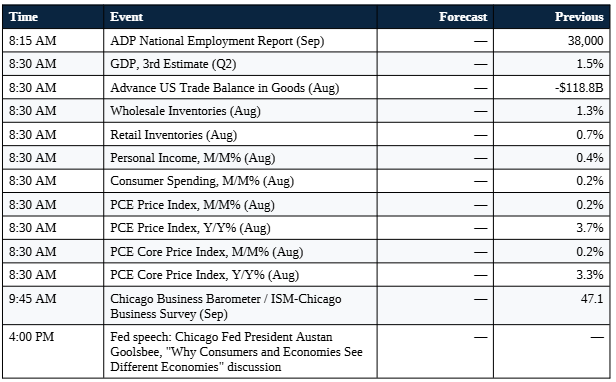
That's the wrap for today. Attention now turns to Wednesday's PCE inflation reading, the Fed's preferred gauge, and Friday's September jobs report, both likely to determine whether the market's growing conviction on further rate hikes hardens or breaks, even as Wednesday's completion of the US withdrawal from Iraq adds a fresh variable to an already volatile Middle East picture.