Wall Street Wrap: Pre-Market, November 2, 2026
U.S. stock futures rise on Monday as oil tumbles on U.S.-Iran diplomacy, Marvell agrees to buy Lumentum for $115 billion, and investors brace for Apple earnings, the midterm elections and Friday's jobs report.
Futures rise as oil tumbles on Iran diplomacy, Marvell bids $115 billion for Lumentum, and traders brace for Apple, the midterms and jobs data
Wall Street looks set for a higher open on Monday as oil prices fall sharply and tech rebounds, ahead of Apple's results, Tuesday's midterm elections and Friday's jobs report.
Futures Snapshot
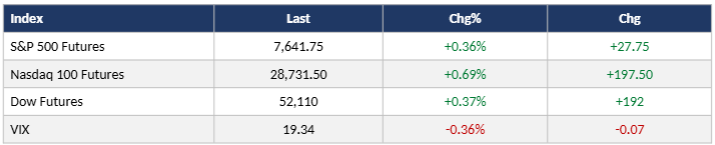
Futures were higher, with the Nasdaq-100 leading, while the VIX eased but stayed above 19.
What's Driving the Open
Oil is setting the tone. Brent fell more than 4% to about $108 a barrel after U.S. Secretary of State Marco Rubio said President Donald Trump would prefer to resolve the Iran war "diplomatically," and Iranian negotiators held a third day of talks with Qatari mediators in Doha. Treasury yields were mixed, and the tight link between oil and bond yields seen earlier in the year faded in October as attention shifted to AI and Big Tech.
Tech is bouncing after a rough stretch. The S&P 500 and Nasdaq both lost ground in October on AI spending worries, and the Nasdaq suffered its worst monthly loss since March 2025, while the Dow rose almost 2% as investors rotated into defensive areas such as healthcare. Nvidia (NASDAQ:NVDA) and Microsoft (NASDAQ:MSFT) edged higher early on. Warren Pies of 3Fourteen Research said he doesn't "see anything broken with the AI trade fundamentally," though "technicals are another story."
The week is packed. Apple (NASDAQ:AAPL) reports after the close, midterm elections are on Tuesday, when Democrats are expected to take the House while Senate control is uncertain, and October nonfarm payrolls on Friday are forecast to show a gain of 55,000 jobs. A newspaper report said the U.S. is preparing for possible renewed military action after the elections, and Trump has said he will not strike Iran before Tuesday.
What could change the picture: A breakdown in the Iran talks would send oil and yields back up, a weak Apple report would pressure the megacap tech rebound, and a surprise in Tuesday's midterm results or Friday's payrolls could move rate expectations.
Overnight Markets
In Europe, the Stoxx 600 was last 0.1% higher after reversing earlier losses, France's CAC 40 gained 0.4% and Germany's DAX added 0.3%. OpenAI CEO Sam Altman made an unannounced weekend visit to South Korea, meeting around 50 Samsung executives and reportedly SK Group Chairman Chey Tae-won, in talks that may have covered AI chips and data centers. Saudi Arabia said its GDP contracted 3.8% year on year in the third quarter after shrinking 4.7% in the second, as the war disrupts Gulf exports. Russian and Ukrainian emergency-alert apps were reportedly hit by cyber-attacks, and Ukraine resumed strikes on Russian oil refineries.
Pre-Market Movers
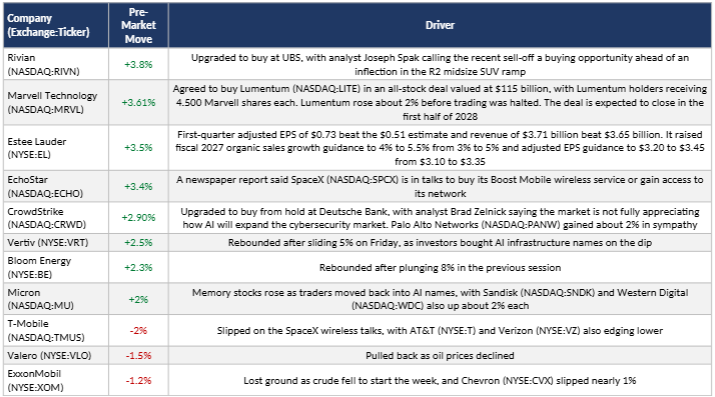
Earnings Before the Bell
Rates, FX & Crypto
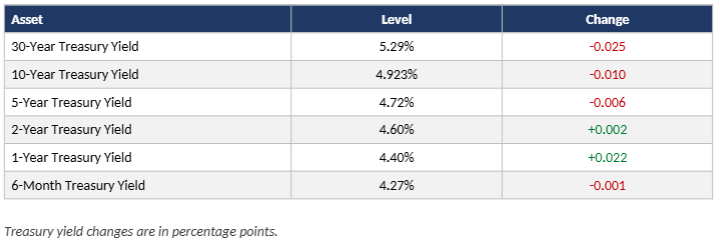
Yields were little changed, with the long end slightly lower and the front end slightly higher, as investors gear up for a busy week of data and the midterms. Friday's equity sell-off had lifted Treasurys on safe-haven demand, and the U.S. Treasury will set out its planned note and bond auction sizes on Wednesday. In crypto, Binance users withdrew a net $3.6 billion after the exchange resumed service on Sunday, about 2% of the assets it held before hackers, believed to be North Korean, stole $6.3 billion last week. Binance is limiting withdrawals and says it will reimburse affected customers.
Commodities
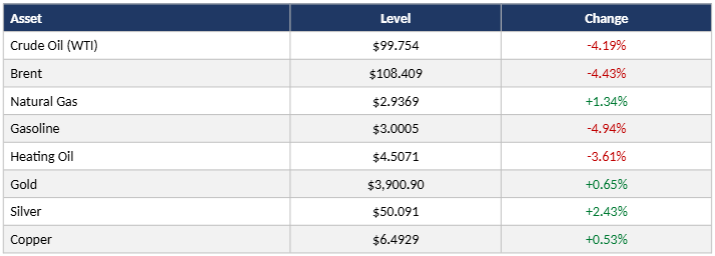
Oil fell sharply as both Washington and Tehran signaled openness to diplomacy. Iran's foreign minister Abbas Araghchi said negotiators had drafted a plan to reopen the Strait of Hormuz within two days of an agreement. OPEC+ kept December output targets steady on Sunday, with most Gulf members still pumping below target, and analyst Jorge Leon of Rystad said the harder test is the Nov. 29 meeting on 2027 quotas.
Key Levels & Catalysts Today
Economic data
- Tuesday brings September JOLTS job openings and the midterm elections.
- Wednesday brings ADP employment and the Treasury's planned auction sizes for notes and bonds.
- Thursday brings productivity and jobless claims.
- Friday brings October nonfarm payrolls, expected to show an increase of 55,000.
Corporate
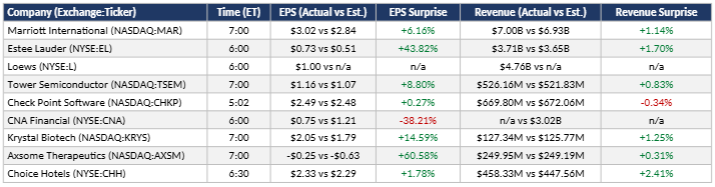
- Earnings before the bell are listed in the table above, led by Marriott and Estee Lauder.
- Apple reports after the close, with McDonald's (NYSE:MCD) and Qualcomm (NASDAQ:QCOM) due later in the week.
- Marvell and Lumentum hold a joint call on the deal at 8:00 a.m. ET.
Top Stories
Marvell to buy Lumentum for $115 billion. The all-stock deal, one of the largest of 2026, values Lumentum at about $1,132 a share, a 23.9% premium to its Oct. 28 close, the last day before speculation began. Marvell holders will own about 67% of the combined company, and Marvell expects more than $1 billion of annual cost synergies and accretion to earnings in the first year after closing. Nvidia invested $2 billion in each company earlier this year, and the deal sharpens Marvell's challenge to Broadcom in custom AI chips. Both stocks had fallen since talks were first reported, Lumentum about 8% and Marvell about 22%.
Oil tumbles as the U.S. and Iran explore a diplomatic path. Iranian authorities signaled a deal is still possible if demands are implemented tangibly, even as Supreme Leader Mojtaba Khamenei called for an "immediate, impactful" response to any threat. Analyst Tamas Varga of PVM Oil Associates said attacks on ships and refineries continue, but "hope springs eternal." Traders are also weighing reports that both sides are preparing for more strikes after Tuesday's elections.
AI labs line up fresh capital. OpenAI signed deals across energy, investment and government in the United Arab Emirates as it works on a $20 billion round co-led by UAE investors, with sources saying it could reach up to $30 billion at a $1.25 trillion valuation. Separately, a filing showed Anthropic will sell up to 552.9 billion yen ($3.5 billion) of shares in Japan as part of its U.S. public listing, with some investors discussing a valuation of about $1.5 trillion.
SpaceX eyes a wireless carrier. A newspaper report said SpaceX is in talks to buy EchoStar's Boost Mobile or gain access to its network, supporting plans for a satellite and ground-based mobile service through Starlink Mobile. The company has already struck an $8 billion spectrum deal, and telecom stocks have come under pressure as investors weigh a new satellite-powered rival. The proposed service may need consent from AT&T and T-Mobile, whose networks Boost leases.
Binance sees heavy withdrawals after a hack. Withdrawals of $3.6 billion followed the exchange's restart, and it is limiting outflows while it phases operations back in and promises to reimburse customers hit by the $6.3 billion theft.
Eyes on Apple after the close, Tuesday's midterm results, and Friday's payrolls.