Wall Street Wrap: Pre-Market, October 29, 2026
U.S. stock futures slip on Thursday as the Google parent heads for its worst post-earnings drop, ServiceNow and Fortinet tumble, and strong GDP and inflation data keep the 10-year Treasury yield above 5%.
Futures slip as the Google parent heads for its worst post-earnings drop, software stocks tumble, and hot GDP data keeps the 10-year yield above 5%
Wall Street looks set for a lower open on Thursday, with tech under pressure after Wednesday's Big Tech earnings while stronger-than-expected growth and sticky inflation keep Treasury yields elevated.
Futures Snapshot
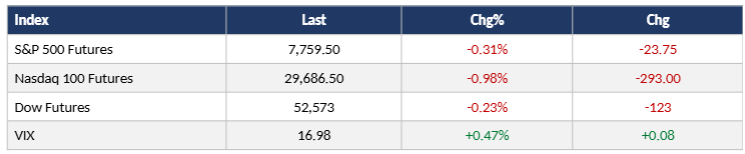
Futures were lower, with the Nasdaq-100 leading the declines as two Dow members were set to drop by more than 10%, while the VIX held below 17.
What's Driving the Open
The pressure comes from Big Tech's latest spending numbers. The Google parent fell about 11% in premarket trading after reporting negative free cash flow of $9.07 billion against the $2.70 billion analysts expected, and it would need to close more than 9.77% lower to record its worst post-earnings reaction since going public in 2004. The software giant rose about 2.7% as Azure revenue grew 48%, even though its capital spending came in below estimates, and delays at outside chip providers pushed some capacity into the first half of 2027. Neocloud stocks fell on those delays, and the iShares Semiconductor ETF (NASDAQ:SOXX) was down more than 2% while the Roundhill Memory ETF (NYSE:DRAM) fell more than 3%. Enterprise software and cybersecurity names tumbled on their own results. Amazon (NASDAQ:AMZN) reports after the close and will give the final read on hyperscaler capex for the quarter.
The macro backdrop is firm. Third-quarter GDP grew 3.4%, ahead of the 3.1% forecast, and the September PCE price index rose 0.5% on the month and 3.6% on the year, while jobless claims fell to 194,000. The Fed held rates at 3.75% to 4% on Wednesday, and the CME's FedWatch tool shows an 83% chance of a quarter-point hike in December. On Wednesday the S&P 500 rose 0.28% to 7,743.98, the Dow gained 97.53 points to 52,475.10 and the Nasdaq Composite added 0.27% to 26,549.85.
What could change the picture: Strong guidance and capex commentary from Amazon would steady AI-linked stocks, hawkish remarks from Fed speakers when their blackout lifts on Friday would push yields higher, and renewed Middle East tensions would send oil back up.
Overnight Markets
In Asia, Japan's Nikkei 225 closed 1.10% higher at 64,659.47 and the Topix gained 0.29% to 4,003.28, while South Korea's Kospi fell 1.24% to 5,937.66 and the tech-focused Kosdaq declined 2.34% to 753.23. Australia's S&P/ASX 200 ended 0.5% higher at 8,891.80, mainland China's CSI 300 closed 1.03% higher at 4,041.84, and Hong Kong's Hang Seng was up 0.24% in its last hour of trade. Samsung Electronics closed 4.13% lower despite a record quarter, as operating profit of 107.44 trillion won was broadly in line with estimates. In Europe, Airbus rose as much as 2.3% after a mixed quarter in which revenue of 17.5 billion euros missed the 18.1 billion euro FactSet estimate but adjusted EBIT of just under 1.8 billion euros beat the 1.75 billion euro forecast.
Pre-Market Movers
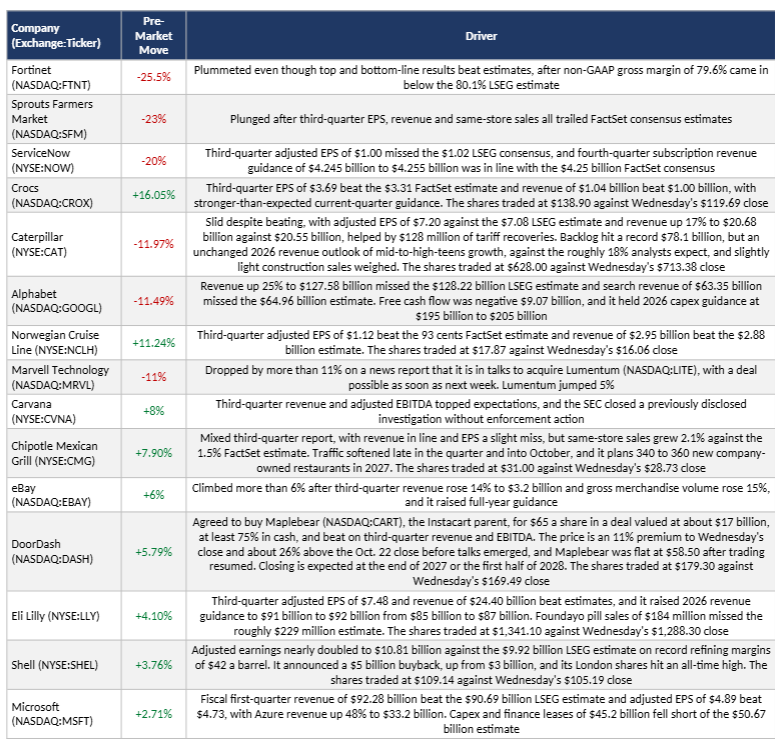
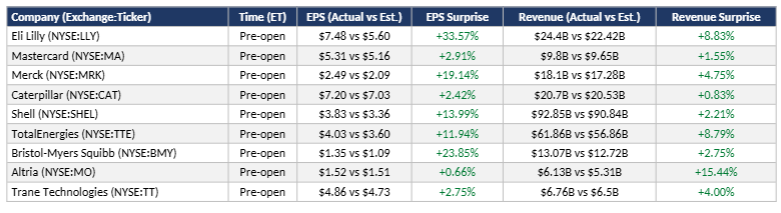
Earnings Before the Bell
Rates, FX & Crypto
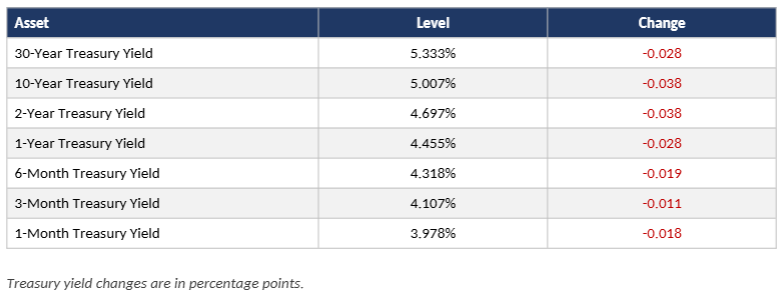
Yields eased from their highs but the 10-year held above 5% after the strong GDP report and firmer inflation data. Ali Hassan of Thornburg Investment Management said markets read the Fed's update as "a softer policy path, not an inflation scare," and still expect a December move but are less convinced of the follow-through. The dollar index edged up to 102.2, and the euro was slightly lower, with EUR/USD at about 1.113 (-0.197%), as European Central Bank President Christine Lagarde announced she will step down in February ahead of the bank's rate decision later today.
Commodities
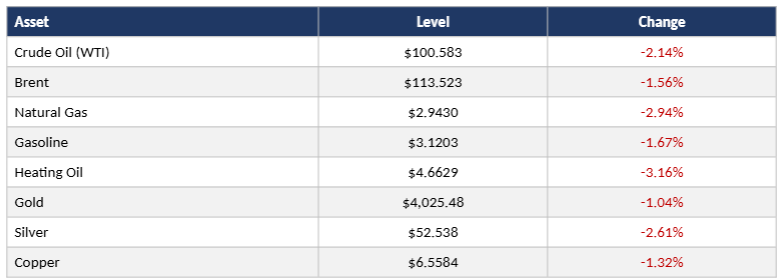
Oil fell as renewed U.S.-Iran peace efforts eased supply fears, following a newspaper report that Vice President JD Vance reached out to Iranian Security Council chief Mohsen Rezaei to restart talks. A senior Iranian official rejected a fresh Qatari proposal as unacceptable, and investors are still weighing Houthi attacks and the possibility of U.S. military action after the Nov. 3 midterm elections.
Key Levels & Catalysts Today
Economic data
- Third-quarter GDP rose 3.4% against the 3.1% forecast and 2.2% in the second quarter, led by a 19.4% jump in private investment and a 20.9% surge in equipment spending tied to the AI build-out.
- September consumer spending rose 0.5% against the 0.6% forecast and personal income rose 0.2% against 0.3%, while real spending was unchanged and real disposable income fell 0.3%.
- The September PCE price index rose 0.5% on the month, in line, and 3.6% on the year against the 3.7% forecast, with core PCE up 0.3% and 3.1%, its highest since May.
- Initial jobless claims fell to 194,000 for the week ending Oct. 24, below forecasts of about 200,000, and continuing claims fell to their lowest in more than three years.
- The European Central Bank announces its rate decision later today and is expected to hold, with Lagarde's press conference to follow.
Corporate
- Earnings before the bell are listed in the table above, including Eli Lilly, Mastercard, Merck and Caterpillar.
- Amazon reports after the close.
- Restaurant Brands International reported adjusted EPS of $1.10 against $1.09 and revenue of $2.53 billion against $2.54 billion, with Burger King U.S. same-store sales up 8.4% and Popeyes down 2.2%.
Top Stories
AI build-out hits a snag as Microsoft and Alphabet hold back on capex. Both reported capital spending below analyst estimates, with Microsoft cutting its capex forecast for the year to $170 billion from $175 billion and Alphabet holding at $195 billion to $205 billion. CFO Amy Hood said delays at third-party GPU providers will push some capacity to the first half of 2027, and shares of CoreWeave (NASDAQ:CRWV), Nebius (NASDAQ:NBIS), IREN (NASDAQ:IREN) and Oracle (NYSE:ORCL) all fell. Hyperscaler capex is still expected to top $1 trillion next year.
Alphabet's search miss revives fears that AI is eating into Google's core. Search and other revenue grew 12% to roughly $63 billion, slowing from 19% in the first quarter and 17% in the second, and missing estimates for a second straight quarter even as query growth was the strongest in five years. Cloud revenue more than doubled to nearly $31 billion and backlog reached about $560 billion, but UBS analysts said the results "bring Search cannibalization fears right back to the forefront."
Lagarde to leave the ECB in February. The European Central Bank president will step down on Feb. 7, 2027, nearly nine months before her term ends, with Klaas Knot and Pablo Hernández de Cos seen as leading contenders to succeed her. Knot is viewed as the more hawkish of the two, while De Cos would signal more continuity. The succession comes as France's bond spread over Germany is at its widest since the early-2010s debt crisis and as euro zone inflation sits at a three-year high.
The Fed holds with two dissents and a calendar change. Governor Lisa Cook, who had never dissented since joining in 2022, and Cleveland Fed President Beth Hammack dissented in favor of a rate hike as the Fed held at 3.75% to 4%, a month after a quarter-point increase. Chair Kevin Warsh said policymakers were not on a set path, and he disclosed that in 2027 one of the eight meetings will have no rate vote or statement, leaving six chances to adjust rates.
Kalshi raises $1 billion at a $40 billion valuation. The prediction market exchange closed a round co-led by Sequoia Capital and Wellington Management, up from the $22 billion valuation set in May and $5 billion a year ago. Growth has been driven by the World Cup, the NFL season and election contracts ahead of the midterms, even as two U.S. appeals courts ruled that states can regulate sports event contracts, a dispute likely headed to the Supreme Court. Kalshi plans to use the funds for leveraged event contracts, perpetual futures on individual stocks and markets to trade the price of compute, and its CEO has said a public listing would not come before 2027.
Eyes on Amazon's capex after the close, the ECB decision later today, and Fed speakers when their blackout lifts on Friday.