ASX Post-Market Wrap: 25 September 2026
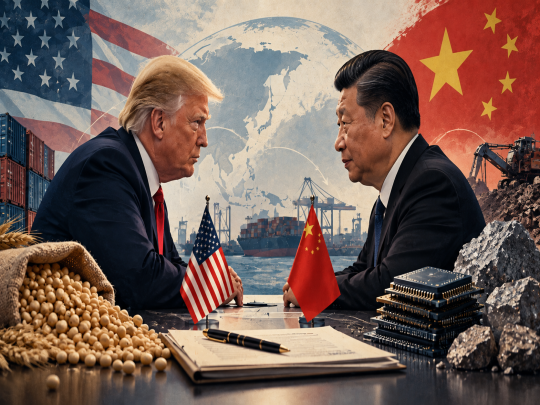
The ASX 200 fell 0.43% to 8,665.0, its lowest close since June 11 and a fourth straight weekly decline, as a quiet, holiday-thinned session saw only 2 of 11 sectors close higher. US and Australian bond yields surged to multi-decade highs, the Trump-Xi summit delivered just a modest trade truce extension, Healius jumped on an asset sale, and Netwealth and Meeka Metals both tumbled on separate setbacks.
ASX Slides to Its Lowest Since June as Bond Yields Hit Multi-Decade Highs
Welcome to ASX Post-Market Wrap, your quick end-of-session rundown of what moved the Australian market today, plus what's shaping global sentiment into tonight's Wall Street open.
Markets Today
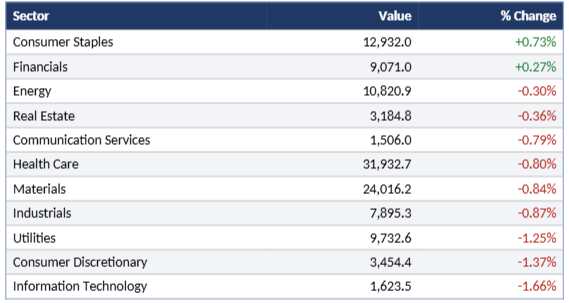
The ASX 200 fell 37.0 points, or 0.43%, to 8,665.0 on Friday, its lowest level since June 11, in a quiet, holiday-thinned session with light corporate newsflow and Melbourne closed for a public holiday. It was the fourth straight weekly decline for the index, down 0.8% for the week and now essentially flat for the year. Only two of eleven sectors finished in the green, led by Consumer Staples and Financials, while Technology was the session's biggest mover to the downside. The path of least resistance remains lower against a genuinely difficult macro backdrop: US and Australian 10-year yields both sit above 5%, Brent crude is above US$100 a barrel, and rate-hike expectations keep climbing on both sides of the Pacific.
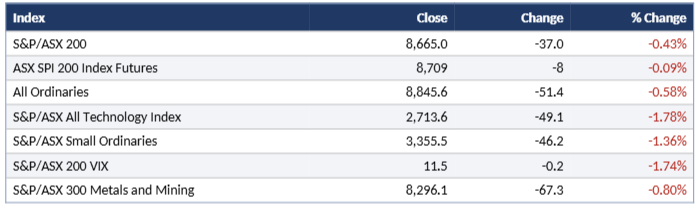
Analytical View
The damage is broadening. Technology, Real Estate and Consumer Discretionary are all down 15-18% over just four weeks, Telcos have lost 11% since August 10, and even the normally slow-moving Utilities sector has shed 5% in five sessions. Breadth scans confirm the extent of it: the average ASX 200 stock now sits 22.9% below its 52-week high, with Technology the weakest sector on this measure (median stock 43.0% off its high, worse than Consumer Discretionary's 37.9%) and more than a third of software names — including WiseTech, Life360, Xero and WhiteHawk — more than 50% off their highs. Real Estate's damage is broad but shallower: every constituent is at least 10% off its high and 80% are down more than 20%, but only 10% have fallen more than half. Financials and Industrials remain the most resilient large sectors, with median stocks down a comparatively modest 16.8% and 16.6% from their highs.
Today's standout mover was Healius, up 5.5% after agreeing to sell Agilex Biolabs to Novotech for $160 million, or 19.8 times FY26 EBITDA; the deal takes Healius to net cash from net debt of $32.8 million at the FY26 result, though management stopped short of committing to return proceeds to shareholders, and the price landed at the low end of the reported $150-200 million range. Netwealth fell 8.1%, with Hub24 and Praemium also lower, after Netwealth's subsidiaries were served with a class action over First Guardian investment options, pushing Netwealth to its lowest level since February 2024. Lithium names were broadly weak as Chinese lithium carbonate futures fell 4.8% to a fresh multi-year low, now down 40% from May's peak; bellwether Pilbara Minerals hit a fresh year-to-date low. Meeka Metals fell 25.9% after an upsized $40 million capital raise priced at a steep discount.
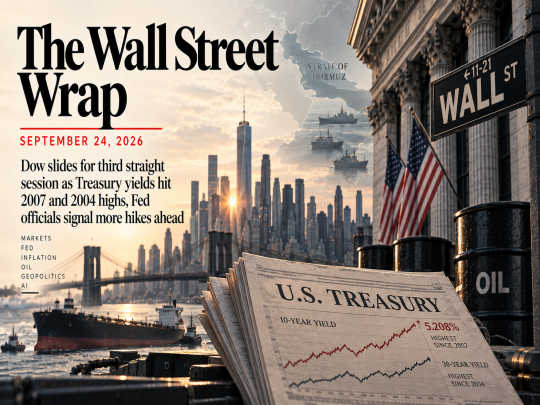
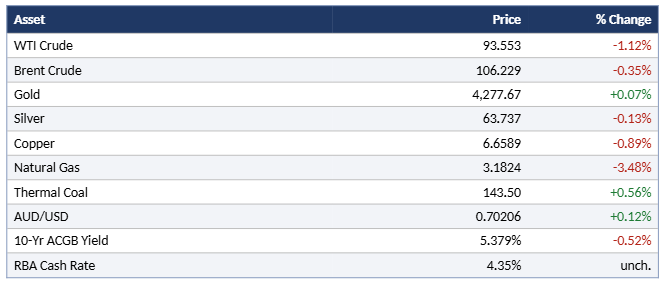
The bigger picture remains a global rates story. The US 10-year Treasury yield hit 5.225% late Thursday, its highest since 2007, while the 30-year touched 5.502%, the highest since 2004 — a selloff driven by hawkish Fed commentary, persistently high energy prices, and a hot US business-activity print. The 30-year US fixed mortgage rate jumped to 7.45% in response, its highest since 2024. Locally, Australian 10-year yields sit close to last week's 15-year peak, and markets are now essentially certain the RBA will lift the cash rate to 4.6% at next week's meeting, with a further move priced for early next year and a real chance of a third hike taking the cash rate above 5% by the middle of 2027. This week's Trump-Xi summit in Washington delivered plenty of pageantry but few concrete deliverables: a two-month trade truce extension fell short of hopes for a longer extension, with the next real opportunity for progress seen at APEC in Shenzhen on November 18-19.
What could change the picture: the RBA's rate decision on September 28-29, where markets will be watching the tone as much as the decision itself, and August inflation data due before then.
Sector Performance
Winners & Losers
Top 5 Gainers:
- NX1 (Nexalis Therapeutics Ltd): +66.67% to $0.015
- M24 (Mamba Exploration Ltd): +33.33% to $0.036
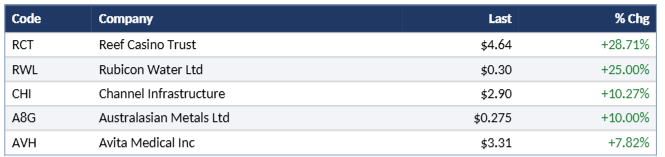
- RCT (Reef Casino Trust): +28.71% to $4.64
- LML (Lincoln Minerals Ltd): +27.27% to $0.014
- RWL (Rubicon Water Ltd): +25.00% to $0.30
Top 5 Decliners:
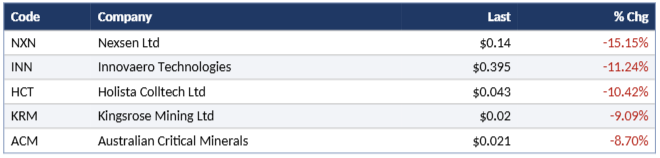
- MEK (Meeka Metals Ltd): -25.93% to $0.10
- GLN (Galan Lithium Ltd): -17.11% to $0.315
- NXN (Nexsen Ltd): -15.15% to $0.14
- WOA (Wide Open Agriculture Ltd): -14.29% to $0.012
- MDI (Middle Island Resources Ltd): -13.33% to $0.013
Volume Outliers
Stocks trading furthest above their 90-day average volume:
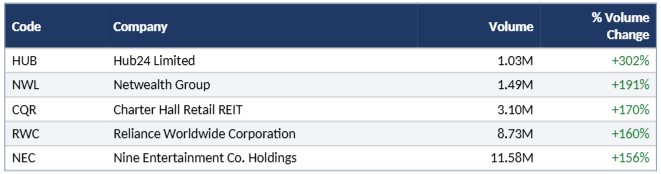
52-Week Highs & Lows
Highs:
Lows:
Near Highs
Commodities & Rates
Corporate Actions & Reporting Calendar
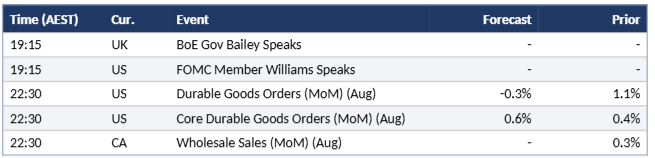
Economic Calendar:
Top Stories: Australia
Healius sells Agilex Biolabs for $160 million, opens strongly. Healius shares rose 5.5% after agreeing to sell Agilex Biolabs to Novotech for $160 million, or 19.8 times FY26 EBITDA, taking Healius to a net cash position from net debt of $32.8 million at the FY26 result. Management did not explicitly commit to returning proceeds to shareholders, and the sale price landed at the low end of the reported $150-200 million range sought. Analysts have noted the sale removes Healius's highest-margin and fastest-growing business unit.
Netwealth hit by First Guardian class action, shares tumble. Netwealth shares fell 8.1% to a two-and-a-half-year low after subsidiaries Netwealth Investments and Netwealth Superannuation Services were served with a class action relating to First Guardian investment options offered through its Superannuation Master Fund. The company said it has already paid $101 million to affected members and intends to defend the claim. Hub24 and Praemium also fell on the read-through to the wider platform sector.
Star Entertainment's Sydney casino licence suspension extended to June. The NSW Independent Casino Commission has extended the suspension of Star Entertainment's Sydney casino licence to June next year, giving special manager Nick Weeks a further nine months to oversee the group's remediation. Star lost the licence in October 2022 after a government inquiry found anti-money laundering failures at its flagship precinct. Commission chief commissioner Philip Crawford said recent governance and culture allegations were serious and being treated as such.
Meeka Metals raises $40 million at a steep discount. Meeka Metals shares fell 25.9% to 10 cents after the gold developer secured firm commitments for a $40 million institutional placement priced at 10 cents per share, a 25.9% discount to its last close. The raise was upsized from an initial $30 million target on strong demand from existing shareholders and new domestic and international investors, with proceeds to fund growth initiatives including deferred consideration for the Mt Holland acquisition.
Insurance Australia Group settles Credit Suisse-linked Greensill litigation. Insurance Australia Group said its subsidiary Insurance Australia has agreed to settle Federal Court proceedings brought by Credit Suisse entities over trade credit insurance policies linked to the collapsed Greensill Capital. The terms of the settlement remain confidential.
Global Stories
Trump-Xi summit yields limited breakthroughs beyond trade truce extension. President Trump and Chinese President Xi Jinping's Washington summit produced only a two-month extension of their trade truce, short of hopes for a longer deal, with Hong Kong's Hang Seng falling 1.3% and Shanghai's benchmark down 1.2% on the outcome. Xi told Trump there was more opportunity for cooperation than competition on artificial intelligence, saying the two sides could continue AI dialogue and guard against its misuse, while China's Commerce Ministry confirmed the first formal US-China AI talks had taken place. The next major opportunity for progress is seen at APEC in Shenzhen on November 18-19.
Oil swings as US and Iran reportedly discuss a phased deal to reopen Hormuz. Brent crude eased toward US$105 a barrel, snapping a two-day rally, after reports that US and Iranian negotiators were discussing a phased agreement to reopen the Strait of Hormuz in exchange for the US lifting its naval blockade, with Qatari officials mediating talks on the sidelines of the UN General Assembly. Iran has said it wants the US to return to a June memorandum of understanding that previously collapsed into renewed fighting. Houthi missile attacks on Saudi targets continued, and a senior Iranian military adviser warned the conflict could widen as far as the Indian Ocean if the US or Israel strike again.
US Treasury yields hit multi-decade highs, mortgage rates follow. The US 10-year Treasury yield touched 5.225% late Thursday, its highest since 2007, while the 30-year reached 5.502%, the highest since 2004, driven by hawkish Fed commentary, high energy prices and strong economic data. The average 30-year fixed mortgage rate jumped 19 basis points in a single day to 7.45%, its highest since 2024, as the bond selloff fed directly through to borrowing costs ahead of the US midterm elections.
European stocks rise as oil eases and bond selloff moderates. European benchmarks gained on Friday, with the Stoxx 50 up 0.9% and the broader Stoxx 600 up 0.7%, as easing oil prices lifted fuel-sensitive sectors including airlines and travel and leisure stocks. Energy stocks were among the session's biggest decliners. German consumer sentiment deteriorated more than expected heading into October on rising energy prices, while UK consumer confidence unexpectedly hit a more than two-year high in September.
Management & Fed/RBA Speak
Xi Jinping, President of China, on AI cooperation with the US, Trump-Xi summit:
"The two sides can continue AI dialogue, exchange views on risks and benefits, and together guard against the misuse or malicious use of AI," Xi said, according to a Chinese state media readout of the meeting.
Philip Crawford, Chief Commissioner, NSW Independent Casino Commission, on Star Entertainment's Sydney licence:
Crawford said Star needed to "learn from past mistakes" before regaining its own casino licence, adding that recent allegations regarding governance, leadership and culture at the casino "are serious and are being treated as such."
That's the wrap for today's session, and for the week. The RBA's rate decision on September 28-29 is now the singular focus for markets, with a hike to 4.6% all but fully priced and attention turning to the central bank's tone for clues on the path beyond next week.