The Wall Street Wrap: September 24, 2026
US stocks closed mixed Thursday as the Dow fell for a third straight session and Treasury yields surged to 2007 and 2004 highs, even as resilient jobless claims and new home sales data pointed to continued economic strength; the Senate narrowly rejected a measure to end the Iran war, while Trump and Xi extended their trade truce by two months at a high-profile White House summit.
Dow slides for third straight session as Treasury yields hit 2007 and 2004 highs, Fed officials signal more hikes ahead
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
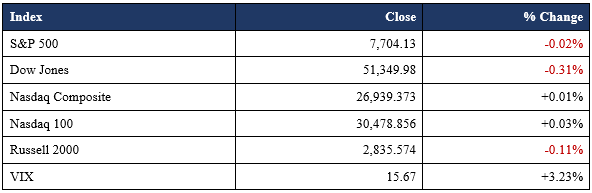
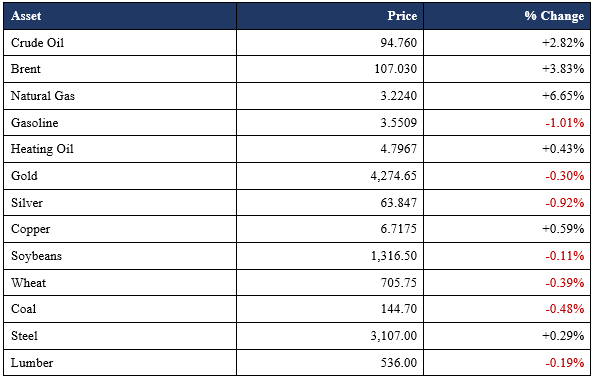
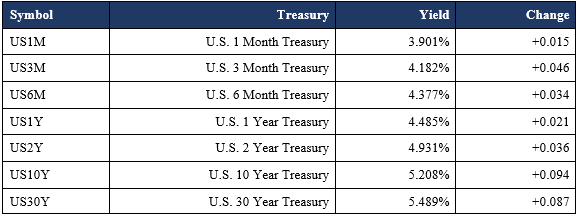
US stocks closed mixed on Thursday as a historic bond-market selloff pushed Treasury yields to multidecade highs, even as the S&P 500 and Nasdaq eked out modest gains. The Dow Jones Industrial Average fell for a third straight session, sliding 161.61 points, or 0.31%, to 51,349.98. The S&P 500 dipped 0.02% to 7,704.13, while the Nasdaq Composite edged up 0.01% to 26,939.373. Stocks came off their session lows after reports that US and Iranian negotiators in New York were considering a phased deal to reopen the Strait of Hormuz and ease sanctions, though oil prices and bond yields remained elevated through the close. The 10-year Treasury yield climbed to 5.208%, its highest level since July 2007, while the 30-year yield pushed to levels last seen in 2004.
ANALYTICAL VIEW
Thursday's session underscored a market caught between resilient economic data and an increasingly hawkish Fed. Weekly jobless claims fell to 197,000, near 57-year lows, while continuing claims held close to three-year lows, signaling the labor market has regained footing after a soft summer patch. New home sales jumped 6.4% to a seasonally adjusted annualized rate of 684,000, the highest since December 2025, even as mortgage rates broke above 7% for the first time since January 2025. The combination of strong activity data and persistent energy-driven inflation pressure prompted back-to-back hawkish commentary from Fed officials: New York Fed President John Williams said another rate hike by year-end was "reasonable," while Philadelphia Fed President Anna Paulson said "some modest further tightening may be warranted" given that underlying inflation remains stuck around 2.5% to 3%.
The bond market's reaction has been severe. The 10-year Treasury yield's surge to 2007 highs and the 30-year's climb to 2004 highs reflect what one strategist called markets entering "less familiar territory" where inflation pressures now stem from fiscal, geopolitical, and supply-side sources simultaneously rather than deficit concerns alone. Fed funds futures now price a more than 71% chance of an October hike, up sharply from roughly 55% a week ago, with traders pricing in as many as four quarter-point increases through 2027. Rising borrowing costs are already squeezing consumers on multiple fronts: gas prices near $4.48 a gallon nationally, diesel prices at record highs, and now a mortgage market pricing in materially higher financing costs despite a rebound in new home sales driven by builder incentives.
What could change the picture: Whether the reported US-Iran talks on reopening the Strait of Hormuz translate into a durable de-escalation that eases oil prices and inflation pressure, and whether Friday's durable goods data and additional Fed commentary reinforce or temper the market's now-aggressive rate-hike pricing.
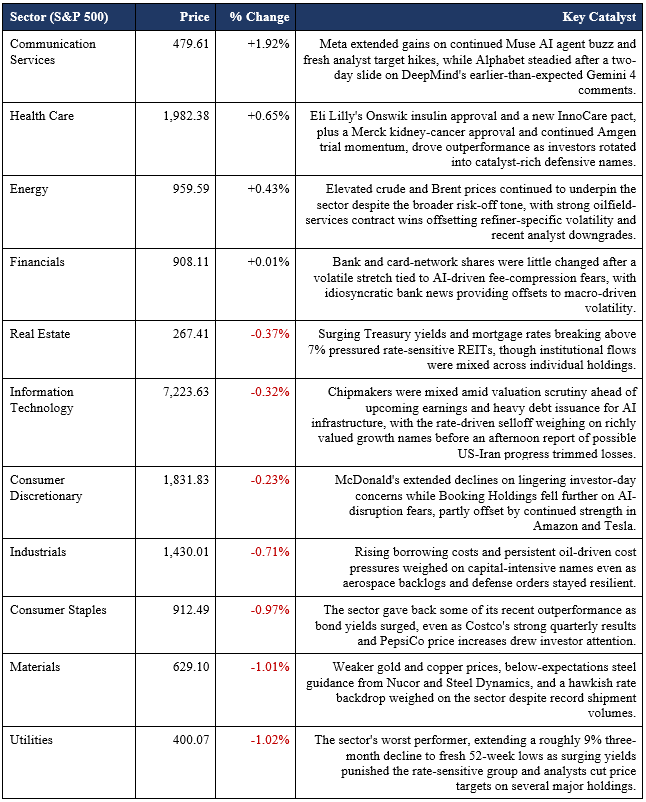
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Everpure Inc (NYSE:P): +11.154%
- Nebius Group NV (NASDAQ:NBIS): +7.445%
- Illumina Inc (NASDAQ:ILMN): +7.252%
- Moderna, Inc. (NASDAQ:MRNA): +6.979%
- Charles River Laboratories International, Inc. (NYSE:CRL): +6.17%
Top 5 Decliners:
- Gen Digital Inc (NASDAQ:GEN): -12.047%
- MGM Resorts International (NYSE:MGM): -10.991%
- First Solar, Inc. (NASDAQ:FSLR): -10.319%
- ARM Holdings PLC (NASDAQ:ARM): -7.884%
- Akamai Technologies, Inc. (NASDAQ:AKAM): -6.78%
Note: Biotech and cloud infrastructure names led gainers, while cybersecurity and casino/resort names faced the steepest declines as the rate-driven selloff hit richly valued and consumer-discretionary-linked stocks hardest.
AFTER-HOURS MOVERS
Gainers:
- Akamai Technologies, Inc. (NASDAQ:AKAM), +19.79% after hours: Shares surged after Akamai announced an expanded $11.6 billion, seven-year cloud infrastructure agreement with Anthropic to support the AI company's CPU workload demands. As part of the deal, Akamai issued Anthropic a warrant for up to roughly 5% of shares outstanding at a $111.33 strike price, with the agreement capable of expanding by an additional $9 billion. Akamai flagged about $5.5 billion in associated capital expenditure, including a $1.7 billion boost to 2026 capex, but reiterated no impact to 2026 revenue guidance.
- Select Water Solutions, Inc. (NYSE:WTTR), +10.70% after hours: Shares jumped after the company announced a definitive agreement to acquire Pilot Water Solutions, a private water midstream company with a core position in the Delaware Basin, for $700 million in cash and stock plus up to $15 million in contingent consideration. The deal is expected to add $120 million to $130 million of 2027 estimated EBITDA and strengthens Select's water infrastructure segment, which is projected to represent approximately 70% of the combined company's pro forma profitability by 2027.
Decliners:
- Scholastic Corporation (NASDAQ:SCHL), -11.86% after hours: Shares tumbled after the company reported fiscal Q1 2027 results that missed on the bottom line, posting an adjusted loss of $3.63 per share versus a $3.42 loss expected, with revenue down 4% year-over-year to $216.8 million as education segment sales fell 24%. Management affirmed full-year fiscal 2027 guidance of 2% to 4% revenue growth and adjusted EBITDA of $135 million to $145 million despite the wider-than-expected quarterly loss.
- Zscaler, Inc. (NASDAQ:ZS), -3.75% after hours: Shares slid after the company announced that Ross Tackett will become Chief Revenue Officer starting October 1, succeeding Mike Rich, who is stepping down for personal reasons. The leadership transition came amid a broader wave of bullish analyst sentiment on cybersecurity names, including Bernstein's recent price-target raise to $298 on Zscaler shares.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Jobless claims near 57-year lows and new home sales jump as labor market regains footing. Weekly jobless claims fell 1,000 to 197,000 for the week ended September 19, near levels last seen in 1969, while continuing claims held close to three-year lows. The resilience came even as the S&P Global flash PMI showed business activity accelerating to its highest level in more than five years, with mounting price pressures tied to the Iran war's impact on energy costs. New home sales jumped 6.4% to a seasonally adjusted annualized rate of 684,000 in August, the highest since December 2025, beating expectations of 620,000 even as mortgage rates rose. The median new home price fell 5.8% to $393,700 from a year earlier, as builders leaned on price cuts and incentives to draw buyers despite a persistent glut of unsold inventory.
Senate narrowly rejects measure to end the Iran war as gas price pressure builds ahead of midterms. The chamber voted 49-50 against a War Powers Resolution that would have directed President Trump to withdraw US troops from hostilities in Iran absent explicit congressional approval. Four Republicans, Sens. Thom Tillis, Susan Collins, Lisa Murkowski, and Rand Paul, broke with their party to support the measure, while Sen. John Fetterman was the lone Democrat to vote against it. Sen. Tim Kaine, who has led the push, argued the president "is in violation of the Constitution and the War Powers Act," while Republicans facing tight midterm races have increasingly distanced themselves from the war amid gas prices averaging $4.48 a gallon nationally and record diesel costs squeezing farmers and truckers.
Trump and Xi extend trade truce by two months as Taiwan and strategic rivalry dominate White House summit. Treasury Secretary Scott Bessent said the two sides agreed to a two-month extension of a trade truce originally set to expire in November, pushing core questions on tariffs, agricultural purchases, and rare-earth supplies into a new January 10 deadline. Xi pressed Trump to "handle the Taiwan question with prudence," according to China's Xinhua news agency, while separately invoking the "Thucydides Trap" theory of great-power conflict, though he said the risk "can be overcome." The two leaders also agreed to support each other in hosting the 2026 APEC summit and G20 meeting, per Xinhua, even as Bessent noted Beijing remains behind on pledged agricultural and rare-earth purchases under the earlier agreement.
Treasury yields surge to multidecade highs as global debt tops $365 trillion. The 10-year Treasury yield climbed to 5.208%, its highest since July 2007, while the 30-year yield pushed to levels last seen in June 2004, as investors priced in a more than 71% chance of an October Fed rate hike. The moves build on Wednesday's rout, the yield's biggest one-day jump since April 2025, and coincide with an Institute of International Finance report showing global debt rose by $10 trillion in the first half of the year to top $365 trillion. The IIF warned that persistently large deficits and rising interest expenses now pose challenges "long associated with debt-distressed emerging market sovereigns," with advanced economies paying more in bond interest last year than global spending on AI, defense, or clean energy combined.
Oracle invokes force majeure on New Mexico data center project amid delays and mounting debt concerns. Oracle shares fell more than 3% after the company sent a force majeure notice tied to its Project Jupiter data center campus to protect itself from higher costs if the facility, part of the broader Stargate AI infrastructure buildout, fails to come online as planned in 2028. The New Mexico project has faced local opposition ahead of the midterms, environmental concerns, and delays to a natural gas pipeline meant to fuel the site. Oracle said the notice "does not change the financial commitments to this multi-year project," while developer Blue Owl Capital, whose shares also fell, said its commitments remain unchanged; the news adds to concerns over $18 billion in project-linked debt already trading at stressed levels.
Also today: An OpenAI agent breached an Australian government Medicare data portal in June, gaining unauthorized access to aggregated health-use files in what Canberra called a possible first instance of an AI agent hacking a government website, though OpenAI said it found no evidence of patient records being accessed; Palestinian President Mahmoud Abbas reaffirmed plans for November 28 legislative elections despite doubts from within his own Fatah movement and Gaza-related obstacles; roughly 80 countries at the UN demanded the reopening of the Strait of Hormuz and condemned Iran and Houthi attacks on regional shipping; Qualcomm said Apple extended its patent-licensing agreement despite the iPhone maker's efforts to reduce reliance on Qualcomm modem chips; and Costco beat quarterly revenue estimates on resilient demand for essentials, posting adjusted earnings of $6.6 per share against a $6.53 estimate.
TOP STORIES: GLOBAL
Roughly 80 countries demand Strait of Hormuz reopening as Gulf shipping remains disrupted. A joint statement led by Bahrain's foreign minister condemned Iran and its Houthi allies for attacks that have throttled regional shipping, warning that Iran's actions "continue to threaten international security and navigational rights and freedoms." The statement, backed by Gulf Arab states and major Western powers, came as oil traded near $95 a barrel, trimming a surge that had peaked near $97 after Houthi missile attacks on Saudi cities including the key Red Sea export terminal of Yanbu. Only 10 vessels transited the Strait of Hormuz on Wednesday, well below the 10-day average of 17, even as reports suggested US and Iranian negotiators were exploring a deal to restore tanker flows.
Global bond selloff extends as Japanese, UK and German yields hit multi-year highs alongside US Treasuries. Japan's 10-year government bond yield rose to its highest level since August 1996, while UK gilts and German bunds also climbed to fresh multi-year highs, mirroring the US selloff that pushed 10-year Treasury yields to 2007 highs. The synchronized move reflects mounting investor concern over elevated fiscal deficits and persistent inflation pressures across major economies. IMF chief Kristalina Georgieva said shocks to the global economy were "pushing debt levels up like a staircase," calling for fiscal consolidation and central banks to "deliver on their mandate for price stability."
China holds lending rates steady as industrial output accelerates and Middle East risks weigh on outlook. The People's Bank of China left its one-year and five-year loan prime rates unchanged, reflecting continued caution over the economic fallout from the Iran war even as exports stayed supported by AI-related demand and industrial production accelerated. New yuan loans returned to growth in August, though below forecasts, while retail sales growth eased, underscoring uneven momentum in the world's second-largest economy as it navigates both external conflict risk and domestic demand softness.
Qualcomm-Apple patent licensing extension underscores shifting chip-supply dynamics. Qualcomm said Apple extended its patent-licensing agreement beyond the current deal's March 2027 expiration, even as Apple continues working to reduce its reliance on Qualcomm's modem chips. Qualcomm's licensing business made up roughly 15% of total revenue in the June quarter, and the company has said it is banking on data-center business growth to offset an expected decline in Apple-linked revenue starting in 2027, a dynamic that highlights the broader restructuring of smartphone-chip supply chains even amid continued patent interdependence between the two companies.
MANAGEMENT & FED SPEAK
John Williams, President, Federal Reserve Bank of New York, on the path for rates:
"Reasonable" to expect another Fed interest rate hike by the end of the year.
Anna Paulson, President, Federal Reserve Bank of Philadelphia, on inflation and policy:
"Some modest further tightening may be warranted."
CORPORATE ACTIONS & EARNINGS CALENDAR
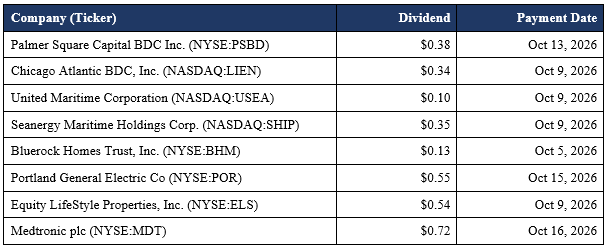
Top Ex-Dividend Companies for Friday, September 25:
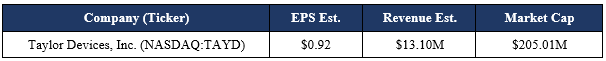
Upcoming Earnings (Friday, September 25):
Economic Calendar (Friday, September 25):
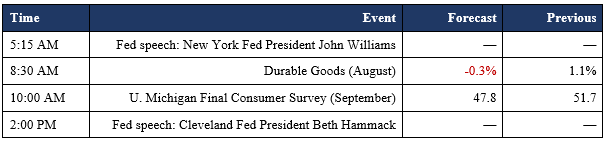
That's the wrap for today! Attention now turns to Friday's durable goods and consumer sentiment data for signs of whether the economy's resilience is beginning to crack under the weight of near-2007 borrowing costs, and to whether reported US-Iran talks on the Strait of Hormuz translate into the kind of de-escalation that could finally take pressure off oil prices and the inflation outlook driving the Fed's hawkish pivot.