ASX Pre-Market: Tuesday, 15 September 2026
ASX 200 futures point to a modest pullback after Wall Street's AI-linked selloff overnight and a brief touch of 5% on the US 10-year Treasury yield, with this week's Fed decision now priced at roughly 90% odds of a hike.
Welcome to your morning briefing on overnight Wall Street action and what's set to move the ASX 200 at the open.
ASX Futures
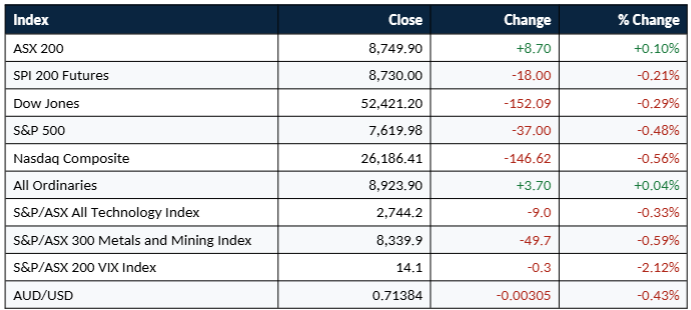
SPI 200 futures were down 18 points, or 0.21%, to 8,730, pointing to a modest pullback after Monday's local session closed narrowly higher. The softer lead follows Monday's close, where the ASX 200 edged up 8.70 points, or 0.10%, to 8,749.90, and comes as Wall Street's major indices fell overnight amid a broad AI-related selloff and a brief touch of 5% on the US 10-year Treasury yield.
Overnight Leads + This Morning
Monday's local session was a genuinely mixed one, with the ASX 200 edging up just 8.70 points, or 0.10%, to 8,749.90, as gains in healthcare offset losses in technology and materials. Catalyst Metals and Lovisa Holdings led the index, up 6.11% and 5.73% respectively, while easing metals prices weighed on miners, with the basic materials sector logging a third straight losing session as copper prices retreated. Health Care outperformed, adding 1.5%, with Telix Pharmaceuticals up more than 4% on FDA approval for its glioma-imaging drug, alongside solid gains for CSL and Cochlear. Financials rose 0.4% as Westpac, Commonwealth Bank and ANZ improved, though Macquarie fell on reports its capital settings draw softer regulatory treatment than other banks. Energy added 0.4% as Woodside, Ampol and Viva rallied and Santos touched a four-year high on the stronger oil price. Technology was the laggard, down 1.1%, as Nasdaq futures pointed to a sharp drop for US tech stocks following weekend calls from industry leaders to slow the pace of AI development. The index has lost 2.90% over the past five trading days but remains virtually unchanged for the year.
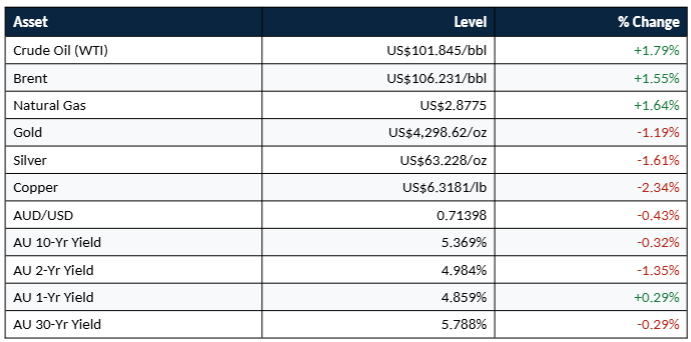
Overnight, Wall Street pulled back from its session lows but still kicked off the week in the red, with the S&P 500 falling 0.5% to 7,619.98, the Nasdaq dropping 0.6% to 26,186.41, and the Dow losing 152 points, or 0.29%, to 52,421.20. AI-related stocks led the declines after industry leaders called for a slowdown in the development of the technology, following Anthropic CEO Dario Amodei's weekend essay urging a coordinated pacing of frontier AI development, a call that drew public support from OpenAI's Sam Altman and Elon Musk. The US 10-year Treasury yield briefly touched the psychologically significant 5% level intraday for the first time since October 2023, before retreating; it has not yet settled and remains a live point of focus heading into this week's Federal Reserve meeting. Oil extended its advance, with Brent rising as much as 3.7% to above $108 a barrel intraday before paring gains, after Saudi Arabia's East-West pipeline closure and continuing attacks in the Persian Gulf tightened the supply picture further. Fed funds futures were pricing roughly a 90% probability of a quarter-point hike at this week's meeting, according to the CME FedWatch Tool, up from around 67% before last week's inflation data.
Close Levels
Analytical View
Monday's local session showed a market genuinely split by sector rather than moving as one. Healthcare's 1.5% gain, powered by Telix's FDA approval and steady gains in CSL and Cochlear, was the standout, while Financials also firmed as the major banks advanced. Set against that, Materials fell for a third straight session as copper prices retreated, and Technology dropped 1.1% as the sector priced in the same AI-development-slowdown concerns that hit US markets. The net result, an index up just 0.10%, understates how much rotation happened beneath the surface. The five-day decline of 2.90% shows the index has not yet recovered from the prior week's broader selloff, even with Monday's modest bounce.
Overnight, Wall Street's story was similarly split. The headline move, the 10-year Treasury yield's brief touch of 5% for the first time since October 2023, reflects a genuine inflection point for borrowing costs, even though the yield retreated intraday and has not settled. Layered on top of that was a distinct and separate story: a broad selloff in AI-infrastructure names after Anthropic's Dario Amodei called for the industry to deliberately slow the pace of frontier model development, a call that drew public support from OpenAI's Sam Altman and Elon Musk over the weekend. That combination, a still-unsettled bond market alongside a reassessment of AI-capex-linked equities, is a materially different setup than Friday's session and leaves both the ASX 200's rate-sensitive names and its own AI-infrastructure-adjacent stocks exposed heading into Tuesday's open.
What could change the picture: The Federal Reserve's September 16–17 meeting is the immediate catalyst, with markets pricing a roughly 90% probability of a quarter-point hike, ahead of the Bank of Japan's own decision later this week and the RBA's call on 29 September, which markets now price at a roughly 75% probability of a hike.
Commodities & Rates
Home & Away
Names with a foot in both camps today, ASX movers with direct overseas read-through, and overseas news with a local echo.
Santos (ASX:STO), Woodside Energy (ASX:WDS) and Ampol (ASX:ALD): all rallied Monday as oil extended its advance, with Santos touching a four-year high after Brent rose as much as 3.7% intraday above $108 a barrel following the Saudi pipeline closure and continued Gulf attacks.
Telix Pharmaceuticals (ASX:TLX): rose more than 4% after the FDA approved the company's New Drug Application for Pixclara, an amino acid PET imaging drug for gliomas, which management said is the only FDA-approved radiopharmaceutical imaging drug for the brain cancer.
WiseTech Global (ASX:WTC) and Xero (ASX:XRO): both fell sharply Monday, down 6.97% and 5.01% respectively, as the local session priced in the same AI-development-slowdown concerns that hit Wall Street overnight. The moves stand out against the ASX 200's otherwise flat finish and confirm the AI-sentiment shock reached beyond the US chip names into Australia's own software and cloud-exposed stocks.
Goodman Group (ASX:GMG): rose 1.45% Monday, decoupling from the broader AI-linked weakness hitting WiseTech and Xero. As one of the ASX's primary data-centre and logistics-property plays tied to the AI infrastructure build-out, Goodman's gain suggests the local market is drawing a distinction between AI-development-pacing concerns, which weighed on chip-and-software-adjacent names, and the physical infrastructure buildout, which continues to be read as a separate, still-intact growth story.
Paladin Energy (ASX:PDN): fell 6.91% Monday, a standout decline against a broadly flat index, though the move doesn't appear tied to any single overnight uranium-price or company-specific catalyst that could be verified — worth flagging as one to watch for a same-day announcement rather than attributing to a clean overnight read-through.
Local Catalysts
FleetPartners (ASX:FPR) receives three revised takeover bids. The board has concluded initial due diligence and now has three revised, non-binding proposals to consider: SG Fleet at $4.55 a share, ORIX at $4.65, and a Sumitomo-led consortium at $4.65. The stock surged to a record high of $4.64, up more than 12%, after Element Fleet, the second bidder to enter the race in August at $3.80 a share, withdrew from the process. The board has granted the three remaining parties access to a further phase of due diligence, and stressed no revised offer is binding or guaranteed to lead to a transaction.
Catalyst Metals (ASX:CYL) upgrades Trident reserves. The company announced a 32% upgrade to reserves at its Trident project, to 524,000 ounces at 4.2g/t gold, underpinning an anticipated roughly 10-year mine life at a steady-state annual production rate of 60,000-80,000 ounces. Shares rose 6.1% to lead the ASX 200.
Vysarn (ASX:VYS) terminates NewGround acquisition. Vysarn and NewGround's vendors mutually agreed to terminate the binding share sale agreement under which Vysarn planned to acquire 100% of NWG Enterprises for up to 33 million shares and $25 million in cash, a deal originally intended to establish a new water infrastructure, irrigation and facilities management segment. The share price was unchanged at $0.96 following the announcement, per company disclosure; the ASX 200 pre-market data separately shows the stock down 13.6% on the day.
GenusPlus Group (ASX:GNP) secures $160 million battery storage contract. The company will deliver a 400MW/1.86GWh battery energy storage system for the Birdwood Energy Reserve in Wodonga, Victoria, scheduled for completion in late 2028. GenusPlus will execute balance-of-plant works including civil, structural and electrical infrastructure, high-voltage connection assets and control systems.
Northern Star Resources (ASX:NST) appoints two new directors amid activist pressure. The company appointed former Anglo American CEO Mark Cutifani and mining engineer Peter Rozenauers to its board, effective October 1, both recommended by activist shareholder Elliott Investment Management, which holds a stake worth more than A$1 billion in the company and has pushed for a strategic review. Cutifani's appointment follows his resignation from Woodside Energy's board, effective September 13, for personal reasons. Northern Star has cut production guidance several times over the past year amid issues at its Kalgoorlie processing plant.
PLC Resources (ASX:PLC) restarts drilling at Rochefort, WA. The company has commenced a follow-up reverse circulation drilling program of approximately eight holes for 2,400 metres at the Rochefort gold prospect, targeting the interpreted north-western and down-dip extensions of its maiden drill pattern, which returned anomalous gold in three of five holes. The program is expected to take 14 days, with first assay results anticipated in four to six weeks.
ADX Energy (ASX:ADX) brings in partner for Austrian gas well. The company has signed an agreement with Empyrean Energy, under which Empyrean can earn a 10% interest in the GOLD-1 gas well in Austria via a non-refundable option fee, with drilling planned for the fourth quarter of 2026.
Global News
Saudi pipeline shutdown tightens global oil supply further. Saudi Arabia's East-West pipeline, capable of carrying 7 million barrels per day, remains shut after a drone attack from Iraq damaged a pumping station last Thursday; Riyadh has not disclosed the extent of the damage or a timeline for repairs. Kpler estimates the market could lose 120 million barrels if the closure extends a month and Red Sea storage at Yanbu is drawn down. A planned diplomatic meeting between Iran and Gulf Arab states in Oman to discuss the Strait of Hormuz was abruptly postponed following the attack, and a tanker came under attack in the Gulf on Sunday, resulting in a severe onboard fire.
Fed rate-hike odds have climbed further ahead of this week's meeting. Markets are pricing a roughly 90% probability of a quarter-point hike at this week's Federal Reserve meeting, according to the CME FedWatch Tool, up from around 67% before last week's inflation data. National Australia Bank has abandoned its prior forecast of a Fed hold through 2027, now expecting the Fed to deliver 50 basis points of hikes across coming meetings, citing resilient economic growth, a tight labour market and the spike in oil prices.
Anthropic's Amodei's AI slowdown call continues to reshape industry positioning. Following Saturday's essay calling for a coordinated pacing of frontier AI development, the proposal has drawn continued reaction through Monday, with commentators noting the biggest financial impact may fall on AI infrastructure and newer start-ups tied to the sector's growth, rather than on Anthropic and OpenAI themselves.
Microsoft publishes AI code of conduct in response to safety debate. Microsoft AI chief Mustafa Suleyman said the company's provisional code of conduct, in development for roughly five months, was released now given the intensity of recent discourse. The guidelines bar Microsoft's models from entertaining requests related to weapons manufacturing or dangerous substances, and require that models not conceal their reasoning or communicate with other AI systems in ways beyond human understanding. Suleyman said Microsoft has coordinated informally with Anthropic, OpenAI and Google DeepMind on safety pacing since as early as 2016.
Management & Fed / RBA Speak
Donald Trump, President of the United States, on calls for AI regulation:
Rejected growing calls for AI regulation in a series of Truth Social posts, writing that the only "guardrail" AI needs is "a STRONG AND SMART (High IQ!) PRESIDENT, and the U.S.A. has that, in spades!" He characterised the industry's safety concerns as a "SICK conspiracy" and a "hoax," and said the US must not "kill the Golden Goose" of its lead in AI development over China.
Chen Yixin, Minister of State Security, China, on AI governance:
Wrote that the field of AI has become "the main battleground for global technological competition and a new arena for strategic rivalry among major powers," calling for the acceleration of an AI security risk prevention and control system and "healthy and orderly" development of the technology.
China's Foreign Ministry separately dismissed the US AI leaders' call for a slowdown as unhelpful, with a spokesperson characterising it as disruptive to the process of global AI governance.
Corporate Actions & Earnings Calendar
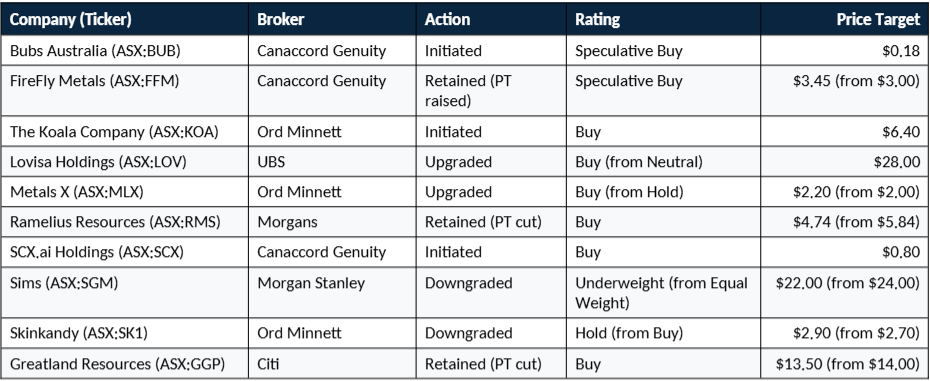
Broker Moves (excluding Retained ratings):
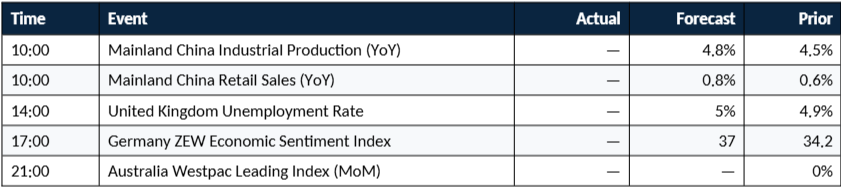
Economic Calendar (Tuesday, 15 September):
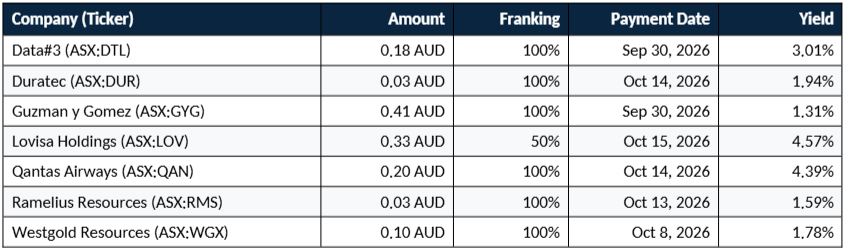
Ex-Dividend Today (Tuesday, 15 September 2026):
Closing Line
That's the pre-market wrap for today. The ASX opens under modest pressure after Wall Street's AI-linked selloff overnight, with SPI 200 futures pointing to a 0.21% pullback following Monday's narrow local gain. The underlying picture remains genuinely unsettled: the US 10-year Treasury yield touched 5% for the first time since 2023 before retreating, oil continues to climb on the Saudi pipeline shutdown, and this week's Federal Reserve decision, now priced at roughly 90% odds of a hike, will set the tone ahead of the RBA's own call on 29 September.

.png)