Earnings Today : PepsiCo, Tilray, Byrna and Three More Stocks Report Before the Bell
Six US-listed companies report before the open on October 8, led by PepsiCo (NASDAQ:PEP), with only two expected to turn a profit. Timings, estimates and the key metrics to watch.
Key Highlights
- Six US-listed companies report on October 8, between 06:00 ET and the opening bell, spanning staples, medtech, cannabis, personal defense and gold.
- Only PepsiCo and Helen of Troy are expected to post a profit, while the other four are forecast to report losses.
- PepsiCo anchors the slate, with adjusted earnings near $2.29 a share and revenue near $24.95 billion expected.
- Options pricing points to one-day moves above 10 percent for AngioDynamics, Helen of Troy and Byrna.
- Tariff costs, consumer demand and the funding of growth recur across the group.
A Morning of Contrasts
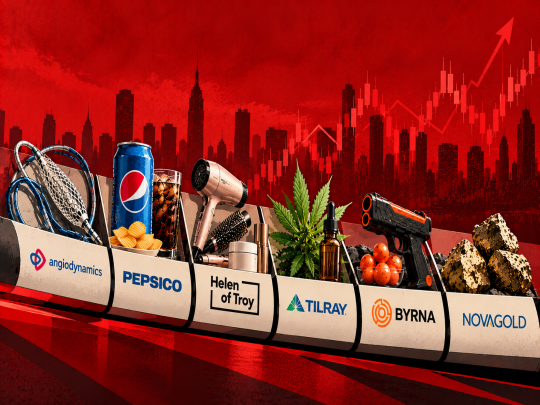
Six companies are due to report results before or at the start of trading on Thursday, October 8, and the group is an unusual mix. PepsiCo (NASDAQ:PEP) is a staples giant worth about $171.6 billion. AngioDynamics, Inc. (NASDAQ:ANGO), Helen of Troy Limited (NASDAQ:HELE), Tilray Brands, Inc. (NASDAQ:TLRY), Byrna Technologies Inc. (NASDAQ:BYRN) and NovaGold Resources Inc. (NYSE American:NG) are much smaller, with market values between about $86 million and $2.9 billion.
Consensus estimates divide the slate in two. PepsiCo and Helen of Troy are expected to report positive adjusted earnings per share. The other four are forecast to post losses, which makes cash, growth and project milestones as relevant as the headline figure.
The running order in Eastern time is AngioDynamics and PepsiCo at 06:00, Helen of Troy at 06:45, Tilray at 07:00, Byrna at 08:00 and NovaGold at 09:30. Conference calls follow between 08:00 and 11:00.
06:00 ET: AngioDynamics (NASDAQ:ANGO) and the MedTech Mix
AngioDynamics reports the first quarter of fiscal 2027. Consensus points to a loss of about 11 cents a share on revenue near $80.5 million. The company has beaten estimates in six of the past seven quarters, and last quarter's revenue of $86.6 million topped forecasts by about 8 percent.
The metric to watch is MedTech growth. The segment rose 18.4 percent to $150 million in fiscal 2026 and now accounts for 47 percent of sales, up from roughly 22 percent in fiscal 2020. Within it, the Auryon atherectomy platform grew 17.7 percent and the NanoKnife ablation system 35.2 percent. Management guided fiscal 2027 sales to between $336 million and $341 million, so any change to that range will draw attention, as will tariff costs, which reached $4.8 million last year, and a chief executive transition expected in the first half of the fiscal year. The company ended fiscal 2026 debt-free with $53.9 million in cash. Options pricing implies a move of about 11 percent, against a historical average near 9 percent.
06:00 ET: PepsiCo (NASDAQ:PEP) and the Volume Question
PepsiCo is expected to report adjusted earnings of about $2.29 a share on revenue near $24.95 billion, which would be growth of roughly 4 percent. Last quarter revenue grew 6.4 percent to $24.2 billion and beat forecasts by about 1 percent.
Volume is the central issue. In the first half of 2026, food volumes rose 3 percent and beverage volumes 2 percent, the fastest pace since 2022. North America weakened in the second quarter, however, as higher fuel prices weighed on convenience and gas-station sales. Management reaffirmed full-year guidance while pointing to the low end of its earnings range, and said tariff refund claims could add about one point to earnings per share. International operations, on course to exceed $40 billion in sales this year, are the offsetting strength.
Sector peers have sent mixed signals. Constellation Brands grew revenue 6.1 percent and beat expectations, while Conagra reported a 1.4 percent decline in line with forecasts and its shares fell. PepsiCo shares have dropped about 9 percent over the past month heading into the report.
06:45 ET: Helen of Troy (NASDAQ:HELE) and Margin Pressure
Helen of Troy is forecast to earn about 51 cents a share on revenue of roughly $442 million, implying growth of 2 to 3 percent from $431.8 million a year earlier. The earnings estimate sits below the 59 cents reported a year ago, which puts margins and cost control in focus.
The first quarter showed how sharply the shares can react. Sales rose 8.2 percent and adjusted earnings of 17 cents beat the 2 cents expected, helped by $4 million to $5 million of favorable order timing, yet the stock fell more than 10 percent the next day. Management's full-year adjusted earnings range is $3.25 to $3.75 a share, with about 20 percent expected in the first half. Tariff refunds worth $9.2 million are in the outlook but are more than offset by commodity inflation, adverse yuan movements and higher freight costs, and the company has paid $71 million in tariffs not yet subject to refund. A low-single-digit sales decline is guided for the second half, with Middle East supply disruption flagged as a risk. Options imply a move near 14 percent.
07:00 ET: Tilray Brands (NASDAQ:TLRY) and the Cost of Growth
Tilray is expected to post a loss of 18 cents a share on revenue of about $266 million, roughly 27 percent above the year-earlier quarter, a jump that reflects acquisitions. Last quarter revenue of $281.7 million beat forecasts by 14 percent, but the loss of 43 cents a share was far wider than analysts expected.
Fiscal 2026 revenue reached a record $915.5 million, adjusted EBITDA was $61.1 million, and cash of about $235 million left net debt below $1 million. Beverage alcohol is the growth engine, supported by the BrewDog acquisition and a Carlsberg partnership in the US that begins on January 1, 2027. Management guided fiscal 2027 adjusted EBITDA to between $68 million and $75 million. The question for investors is whether faster revenue turns into narrower losses, and whether international cannabis, which grew 34 percent last year despite price compression, holds its pace.
08:00 ET: Byrna Technologies (NASDAQ:BYRN) and a Reset Quarter
Byrna is forecast to report a loss of about 16 cents a share on revenue near $16.3 million for the quarter that ended August 31. Last quarter was difficult. Revenue fell 42.5 percent to $16.4 million, missing forecasts by more than a quarter, and the loss of 44 cents a share was far larger than expected. Reported gross margin dropped to 11 percent after an inventory write-down, an equipment impairment tied to the closure of the Fort Wayne ammunition facility and an inventory reserve, although adjusted margin held near 62 percent.
Management said fiscal 2026 would not be a growth year, described the third quarter as a transition and pointed to holiday demand and new marketing for a fourth-quarter improvement. Cash of $10.4 million and no debt provide some room, though trailing free cash flow has been negative. Options imply a move of about 25 percent, the widest on the slate.
09:30 ET: NovaGold (NYSE American:NG) and the Funding Path
NovaGold has no revenue, so the consensus loss of about 7 cents a share matters less than news on Donlin Gold, the Alaska project it owns equally with Barrick. Last quarter's loss of $25.5 million, or 6 cents a share, matched forecasts. Treasury stood at $370.2 million at the end of that quarter, which management said covers corporate costs for at least a year.
The bankable feasibility study is targeted for the first half of 2027, and the company has said financial advisors are engaged on project financing, so any update there will be read closely. Management estimates a post-tax net present value near $20 billion at a 5 percent discount rate, assuming gold above $4,000 an ounce, with output above one million ounces a year over 27 years. That valuation depends heavily on the gold price and on financing. NovaGold reports at the opening bell, and its call at 11:00 comes after trading has started.
What the Morning Could Signal
Three themes recur across the slate: tariff costs, consumer demand and the funding of growth. Tariffs touch PepsiCo, Helen of Troy and AngioDynamics. Consumer demand shapes the results of PepsiCo, Helen of Troy, Tilray and Byrna. Funding matters most to the four expected loss-makers.
The risks run both ways. A steady PepsiCo report may reassure the staples group, but slower volumes could reinforce concerns about the sector. Smaller reporters with wide implied moves can swing sharply on a single line, such as guidance, margins or a financing update, and company outlooks may change without much notice. The calls that follow, from 08:00 to 11:00, may matter as much as the numbers themselves.