The Wall Street Wrap: September 21, 2026
US stocks rallied sharply Monday as tech led the charge and oil tumbled on hopes for US-Iran diplomacy, with the Nasdaq closing at a record. AMD topped a $1 trillion market cap, Meta surged on its new Muse AI app, and bitcoin climbed above $86,000.
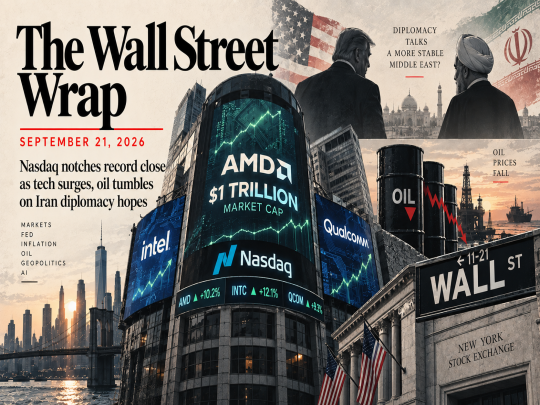
Nasdaq notches record close as tech surges, oil tumbles on Iran diplomacy hopes
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
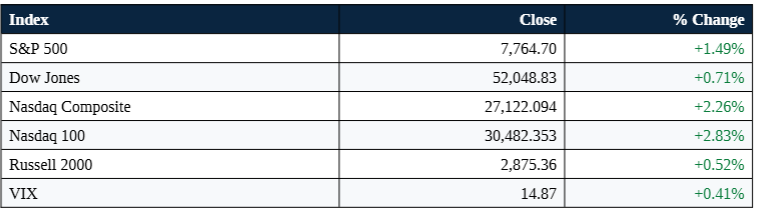
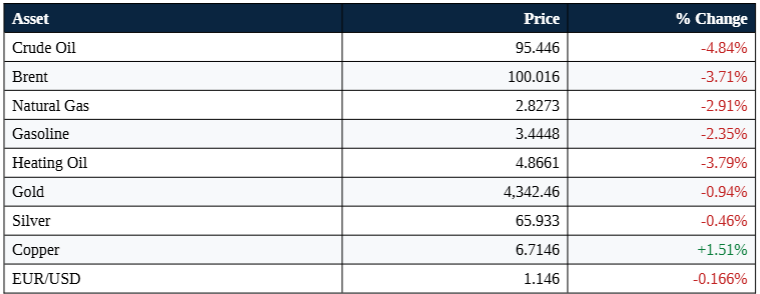
US stocks rose sharply Monday as key technology names advanced and oil prices and Treasury yields slipped, with Wall Street recovering from a mostly lower week. The S&P 500 climbed 1.49% to 7,764.70, while the Nasdaq Composite gained 2.26% for a record close of 27,122.09, its first since June. The Dow added 366.19 points, or 0.71%, to 52,048.83. The broader market was supported by a rise in AI-related stocks: Intel popped 12%, AMD added about 10% and hit a $1 trillion market cap for the first time, and Qualcomm rose more than 9%. The advance was aided by a 4.5% drop in US crude to $95.78 a barrel, as markets reacted to the latest developments in the Middle East, including reports that the US had decided against striking Houthi targets in Yemen and that Trump could be open to meeting Iranian President Masoud Pezeshkian this week.
ANALYTICAL VIEW
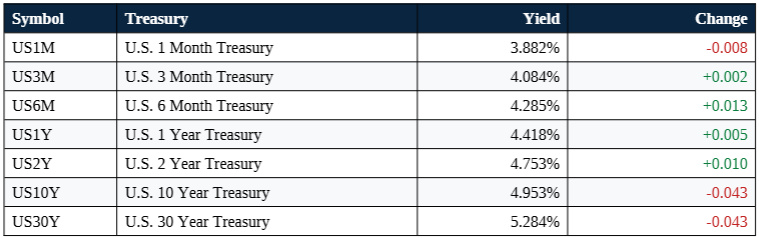
Monday's rally reversed last week's Fed-driven weakness, with the retreat in oil and yields doing much of the work. Treasury yields declined alongside crude: the 10-year fell more than 4 basis points to 4.953%, easing back from last week's 19-year high of 5.041%, as the market read easing Middle East supply fears as reducing near-term inflation pressure. That reading came with a caveat from strategists, who noted the underlying risks haven't disappeared. "Higher-for-longer energy prices add to the case for further tightening," wrote one prominent Wall Street strategist, pointing out that the Middle East conflict "continues to threaten oil production and shipping, while Ukrainian strikes on Russian refineries and sanctions on Russia are further constraining global fuel supplies." Another strategist tied the dynamic directly to this week's diplomacy, noting "the same geopolitical conflict inflating energy prices is also what's keeping the Fed hawkish and what's squeezing Chinese refiners," with the Fed's own inflation outlook effectively conditioned on oil markets settling down.
That context sharpens the stakes for this week's Trump-Xi summit, which will cover AI, tariffs, and critical minerals, alongside preparatory meetings between Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng. Bitcoin added to the risk-on mood, rising above $86,000 for its highest level since late January, as some strategists argued the "crypto winter" that began after bitcoin's October 2025 peak above $126,000 is now over, with early signs of investors rotating out of AI names and back into crypto after the sector's recent run.
What could change the picture: how this week's Trump-Xi summit shapes the trade and AI policy outlook, and whether Middle East diplomacy holds enough to keep oil prices and Treasury yields moving lower.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- ARM Holdings (NASDAQ:ARM): +17.16%
- Astera Labs (NASDAQ:ALAB): +12.36%
- Akamai Technologies (NASDAQ:AKAM): +12.33%
- Moderna (NASDAQ:MRNA): +12.27%
- Intel Corp (NASDAQ:INTC): +12.14%
Top 5 Decliners:
- Marathon Petroleum (NYSE:MPC): -5.30%
- Valero Energy Corp (NYSE:VLO): -4.84%
- United Parcel Service (NYSE:UPS): -4.35%
- HP Inc (NYSE:HPQ): -4.22%
- Phillips 66 (NYSE:PSX): -4.17%
Note: chip and AI-infrastructure names dominated gainers as the sector-wide rally accelerated, while refiners and energy-linked names led decliners as crude's four-day slide weighed heavily on the sector.
AFTER-HOURS MOVERS
Gainers:
- Travere Therapeutics (NASDAQ:TVTX), +2.61% after hours: Shares rose after the company announced CEO Eric Dube will step down effective December 1 to focus on his health and family, with the board unanimously appointing Bradley Campbell, former CEO of Amicus Therapeutics, as his successor. The transition follows a record second quarter in which FILSPARI US net sales surged 96% year-over-year to $141.1 million, and comes after seven senior officers, including Dube, sold a combined $57.7 million in shares over the prior three sessions.
- PDD Holdings (NASDAQ:PDD), +7.00% after hours: Shares extended a stabilization from multi-month lows as investors weighed renewed optimism ahead of the anticipated Trump-Xi summit and Treasury Secretary Bessent's comments that trade talks with China were successful. The stock still trades well below its 50-day and 200-day moving averages amid lingering concerns about Chinese regulatory scrutiny targeting e-commerce platforms, though some investors see value given a consensus fair-value estimate near $167 versus the current price.
Decliners:
- GRAIL (NASDAQ:GRAL), -24.54% after hours: Shares surged as much as 35% in regular trading after the FDA released favorable staff briefing documents ahead of Wednesday's advisory committee meeting on its Galleri multi-cancer detection test, with reviewers flagging no major concerns on performance, safety, or study design. The after-hours pullback suggests profit-taking and a reassessment of the FDA's more nuanced question about whether Galleri's data supports its characterization as an "early detection" test, with the panel vote on September 23 the key catalyst investors are watching.
- Quest Diagnostics (NYSE:DGX), -6.90% after hours: Shares closed little changed near their 52-week high after Truist Securities raised its price target on confidence in the company's double-digit revenue and earnings growth guidance for 2026, but reversed sharply after hours with no specific catalyst identified in available reporting. The drop stands out against a broadly positive healthcare sector backdrop and the stock's roughly 42% year-to-date rally through mid-September.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
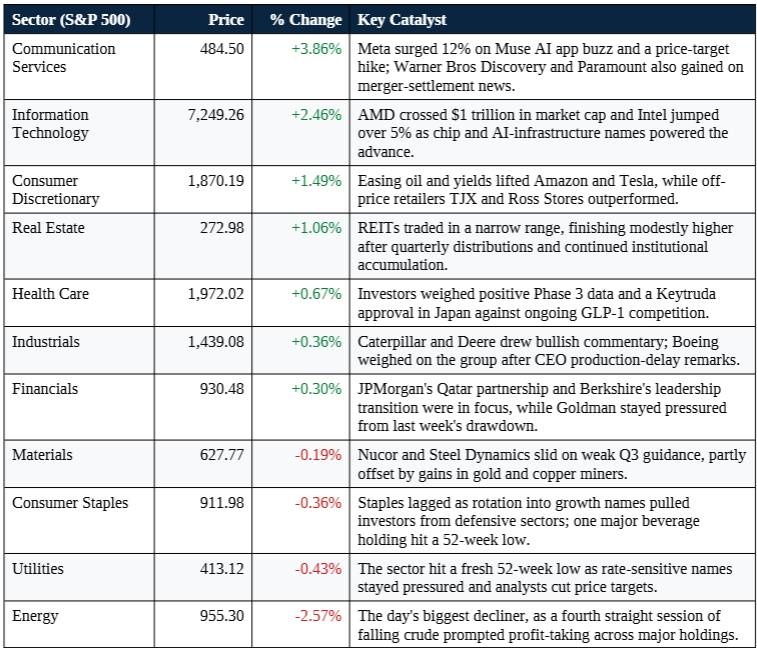
AMD (NASDAQ:AMD) hits $1 trillion market cap as shares surge to a record high. Advanced Micro Devices stock jumped about 10% Monday, capping a five-day winning streak during which shares have gained roughly 25%, with its intraday high of $615.52 pushing the company's value just above $1 trillion. The chipmaker is up more than 180% this year, with AI chips driving Data Center unit sales up 107% year-over-year in its most recent quarter, though it remains well behind Nvidia's roughly $5.4 trillion market cap.
Critical Metals Corp (NASDAQ:CRML) and other Greenland-exposed stocks surge on US-Denmark security deal. Shares jumped nearly 37% after President Trump said the US had struck a deal with Denmark on Greenland's security status and would establish a military presence on the island, with the agreement expected to be signed during this week's UN General Assembly. Trump said the deal would come at no cost to the US and would let Washington "immediately begin the process of developing a large Military presence in the appropriate part of Greenland."
Meta Platforms (NASDAQ:META) surges 11% as Muse AI app tops app store charts. Meta's new Muse personal AI agent overtook ChatGPT as the top free iOS app in the US less than two weeks after its September 8 launch, racking up 730,000 downloads in its first five days. Wells Fargo raised its price target on the stock to $796, while Amazon has blocked the Muse bot from its site over privacy and security concerns, even as Shopify agreed to let the app handle agentic checkout in its online stores.
Paramount Skydance (NASDAQ:PSKY) settles with states, clearing path for $110 billion Warner Bros Discovery (NASDAQ:WBD) merger. The settlement with a California-led coalition of states and the Writers Guild of America came after months of legal battling, with Paramount agreeing to temporary film quotas, a news oversight committee, and a pledge not to raise rates on theater operators for three years. Warner Bros Discovery shares surged more than 10% on the news, while Paramount shares pared earlier gains.
Novo Nordisk (NASDAQ:NVO) shares plummet 7.7% as new long-term goals fail to reassure investors. The Danish drugmaker's Capital Markets Day targets, including more than five "multi-blockbuster" drug launches by 2030, fell short of what the market wanted to see, with CEO Mike Doustdar acknowledging that semaglutide's coming loss of patent exclusivity is "the elephant in the room." Shares closed at their worst day since February, extending a 27% decline over the past 12 months versus rival Eli Lilly's 52% gain.
Also today: CNN, MS NOW, and Politico sued the Trump administration over their White House ban, seeking a temporary restraining order with a hearing scheduled for Wednesday, a dispute that prompted other major broadcast networks to suspend the White House television pool arrangement just as Trump prepares to host Chinese President Xi Jinping this week; bitcoin rose above $86,000 for its highest level since late January, with crypto-linked stocks Strategy and Coinbase also higher; Alphabet's Google opened pre-orders for Googlebook, a new premium Android laptop line built around its Gemini AI tools starting at $899; US and UK regulators reportedly asked banks about their exposure to large trading firms following July's losses at the Situational Awareness hedge fund; and US retail diesel prices climbed above $6 a gallon for the first time on record amid supply disruptions from the wars in Iran and Ukraine.
TOP STORIES: GLOBAL
China holds lending rates steady for 16th straight month. The People's Bank of China kept its one-year loan prime rate at 3.0% and its five-year rate at 3.5%, reflecting caution over the Middle East conflict's impact even as exports remained supported by AI-related demand. Industrial production accelerated while retail sales growth eased, and new yuan loans returned to growth in August, though below forecasts.
Iranian President Pezeshkian's UN appearance lifts diplomacy hopes, even as both sides keep threatening escalation. Pezeshkian will lead Iran's delegation to the UN General Assembly on Tuesday, a development that helped lift stocks, ease oil prices, and pull down global bond yields on Monday. But Trump has said the only options on the table are "wiping Iran out" or letting its economy "rot" absent a deal, while Iran's military warned of "painful" retaliation against any new US strike.
Global diesel prices hit fresh records as Middle East and Ukraine conflicts curb exports. Diesel futures in Europe closed at an all-time high last week, more than double their level at the start of 2026, as wars have cut exports from Russia, Saudi Arabia, and the UAE. The International Energy Agency warned that stretched global refining capacity leaves "few available options to prevent a further tightening of supplies and higher prices in the coming months."
German state elections deal severe losses to Merz's CDU as far-right AfD gains ground. The AfD became the strongest party in Mecklenburg-Western Pomerania and placed third in Berlin, marking the CDU's worst result in any state election since 1949 and intensifying pressure on Chancellor Friedrich Merz, who called the outcome a "disaster." The result raises questions about Merz's reform agenda and Germany's economic policy direction, with the AfD drawing support in part through a pledge to revive the Nord Stream gas pipeline from Russia to lower energy costs, a proposal that could complicate the EU's broader energy strategy if the party's momentum continues.
MANAGEMENT & FED SPEAK
Mike Doustdar, CEO, Novo Nordisk, on the company's patent cliff:
"We created an incredibly attractive market, and now almost every other single pharma company, big or small, is trying to come and compete with us. We need to be ready for that."
David Ellison, CEO, Paramount Skydance, on the Warner Bros Discovery settlement:
"Our goal has always been to build a stronger Hollywood, one with more stories told, greater choice for consumers and stronger competition."
CORPORATE ACTIONS & EARNINGS CALENDAR
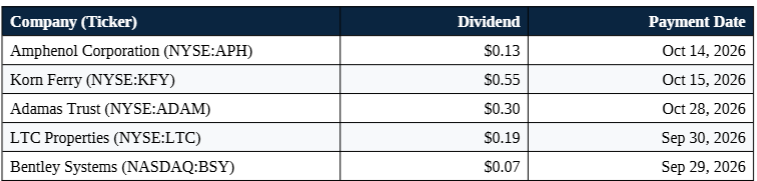
Top Ex-Dividend Companies for Tuesday, September 22:
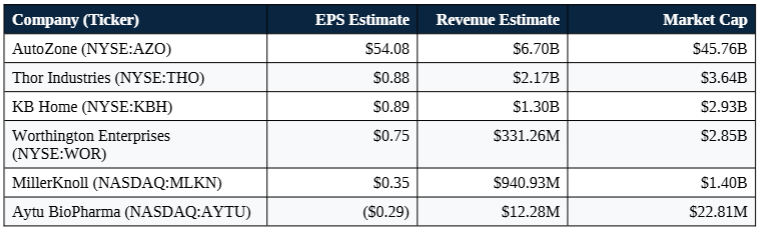
Upcoming Earnings (Tuesday, September 22):
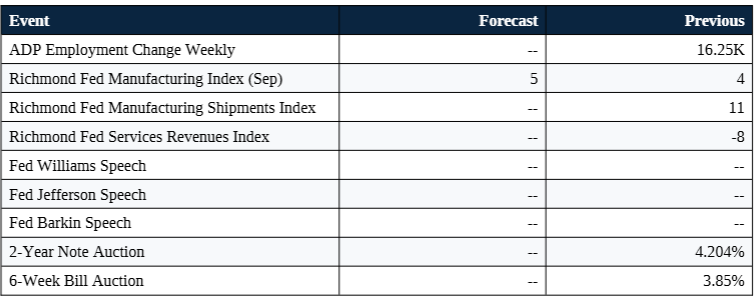
Economic Calendar (Tuesday, September 22):
That's the wrap for today. Attention now turns to this week's Trump-Xi summit in Washington, Wednesday's FDA advisory panel on GRAIL's cancer test, and whether Middle East diplomacy continues to ease the oil-driven pressure that has shaped markets over the past two weeks.