Wall Street Wrap: Pre-Market, November 4, 2026
U.S. stock futures jump on Wednesday as Democrats win Congress and Trump accepts the result, easing election risk, while AMD, Novo Nordisk and CVS Health headline a busy earnings morning.
Futures surge as a Democratic sweep of Congress and Trump's acceptance of the result ease election risk, while AMD, Novo Nordisk and CVS headline earnings
Wall Street looks set for a sharply higher open on Wednesday, as futures reversed steep overnight losses once Democrats won control of Congress and President Donald Trump said he would accept the results.
Futures Snapshot
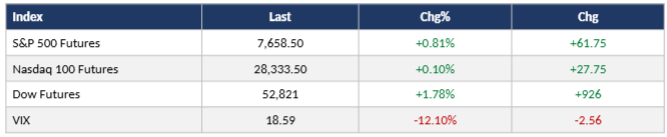
Futures were higher, led by the Dow, while the VIX dropped more than 12% and the Nasdaq-100 recovered from overnight lows.
What's Driving the Open
The reversal was sharp. Futures initially fell as results came in, with Nasdaq-100 contracts touching 27,615.75, their lowest since July 30, before climbing back more than 900 points as investors judged that divided government tends to mean gridlock. Jay Woods of Freedom Capital Markets said "there will be gridlock and historically this is good for the market." Economy-linked shares led early gains, with Walmart (NYSE:WMT) up 2% and Bank of America (NYSE:BAC) up 1.9%, and the dollar slid, with the ICE dollar index down about 0.6% to 101.25.
Earnings added to the relief. Advanced Micro Devices (NASDAQ:AMD) beat on third-quarter results and forecast faster growth through 2027, calming nerves about the AI build-out. Data released this morning also showed private employers added 86,000 jobs in October, ahead of the 75,000 Dow Jones estimate, and Treasury yields moved lower.
On Tuesday, SPY closed up 0.30% at $754.35 and QQQ gained 0.62%, while the Dow ETF lost 0.44%.
What could change the picture: A fresh round of AI-related selling, hawkish signals from the Fed, or a breakdown in the U.S.-Iran talks would push yields and oil back up, while a shutdown fight over the budget would weigh on sentiment.
Midterm Elections: Democrats Take Congress
Democrats won control of both chambers, with projections showing at least 250 House seats and 54 Senate seats after flipping seven Republican-held Senate seats in Iowa, Kansas, Maine, North Carolina, Ohio, South Carolina and Texas. In Texas, James Talarico defeated Ken Paxton for the state's first Democratic Senate seat in nearly four decades, and Gina Hinojosa defeated Gov. Greg Abbott after campaigning for a pause on new data-center projects. Nearly nine in 10 voters in exit polls called the cost of living a crucial or major factor, and traders at JPMorgan said markets are now focused on "reduced deficit spending" and the risk of a government shutdown.
Sector moves followed the policy shift. Renewables rallied, with First Solar (NASDAQ:FSLR) up 8.5%, Plug Power (NASDAQ:PLUG) up 10.6% and Sunrun (NASDAQ:RUN) up 8.64%. Healthcare gained on hopes of friendlier policy, with HCA Healthcare (NYSE:HCA) up 7.16%, Molina Healthcare (NYSE:MOH) up 6.3% and Centene (NYSE:CNC) up 5%. Neocloud and Elon Musk-linked shares fell on fears of tougher data-center scrutiny, while GEO Group (NYSE:GEO) and CoreCivic (NYSE:CXW) fell 6.2% and 5.7% and Northrop Grumman (NYSE:NOC) lost 2.7% on doubts over the $1.5 trillion defense request.
Overnight Markets
In Asia, Japan's Nikkei 225 closed 1.42% lower at 62,188.63 and the Topix fell 0.89% to 3,895.38, while South Korea's Kospi rose 0.62% to 5,683.80 and the Kosdaq gained 1.5% to 714.95. Mainland China's CSI 300 rose 2.31% to 4,101.34, Hong Kong's Hang Seng was up 1.43% in its last hour of trade, and Australia's S&P/ASX 200 fell 0.59% to 8,834.50. In Europe, the Stoxx 600 rose 1.57% to 655.81, France's CAC 40 gained 1.66% to 8,153.76, Germany's DAX rose 1.51% to 26,254.73, the FTSE 100 added 1.60% to 10,808.55 and Spain's IBEX 35 jumped 3.03%. European renewables surged, with Oersted up more than 9% and Vestas up about 5%.
Pre-Market Movers
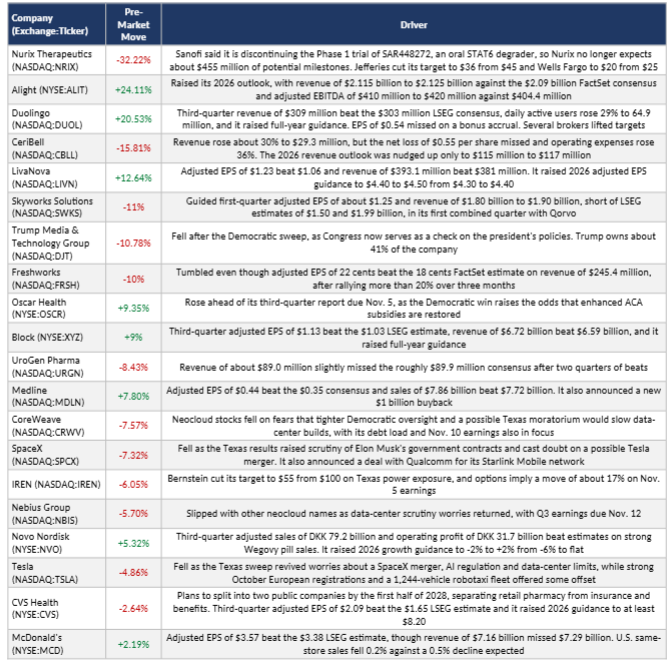
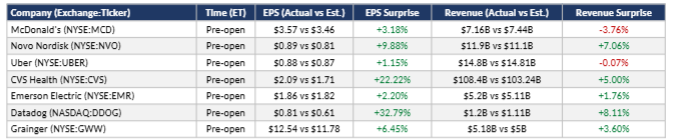
Earnings Before the Bell
Rates, FX & Crypto
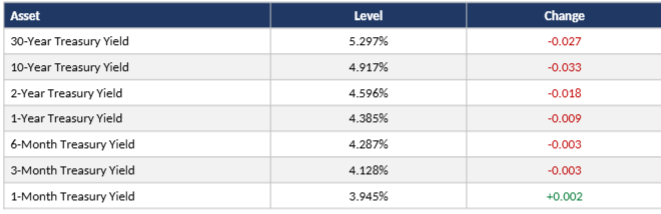
Treasury yield changes are in percentage points.
Yields eased as investors weighed the Democratic wins, with the 10-year down about 3 basis points. The dollar index fell 0.6% to 101.254, and the euro rose about 0.7% to a four-week high near $1.126 to $1.128 after eurozone October inflation hit a three-year high of 4%, making an ECB hike in December very likely. Bitcoin briefly hit about $75,736 overnight before recovering to roughly $78,300, up about 1.3%, with the 50-week moving average holding, while Ether traded near $2,323. Bitcoin ETFs saw about $1.16 billion of outflows over three sessions, and the stalled CLARITY Act market-structure bill faces a tougher path.
Commodities
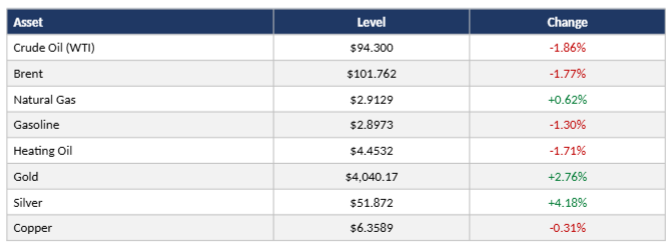
Oil slipped as U.S.-Iran negotiations continued and mediators weighed new proposals, easing inflation worries. Gold and silver jumped as the weaker dollar and lower yields lifted precious metals, with platinum up more than 3% and palladium up more than 6%. Gold is still down more than 7% this year and silver almost 28%, and analyst Rhona O'Connell of StoneX said a divided Congress should support gold as rates and the dollar come under pressure.
Key Levels & Catalysts Today
Economic data
- ADP private payrolls rose 86,000 in October, matching a downwardly revised September and beating the 75,000 estimate, with pay for job-changers up 4.8%.
- Mortgage applications fell 1.2% last week even as the 30-year rate dropped to 7.3% from 7.37%, its third straight weekly decline.
- The Treasury sets out its planned note and bond auction sizes today.
- Thursday brings productivity and jobless claims, and Friday brings October nonfarm payrolls, expected at 59,000 after 29,000 in September.
Corporate
- Earnings before the bell are listed in the table above, led by McDonald's, Novo Nordisk, Uber and CVS Health.
- After the close, Qualcomm (NASDAQ:QCOM), AppLovin (NASDAQ:APP), McKesson (NYSE:MCK), Aflac (NYSE:AFL), Allstate (NYSE:ALL) and MetLife (NYSE:MET) report.
Top Stories
AMD forecasts faster AI growth. The chipmaker reported third-quarter revenue of about $13 billion, with data-center revenue up 97% to $8.55 billion against the $8.20 billion estimate, and guided fourth-quarter revenue to about $17 billion. CEO Lisa Su said overall 2027 revenue should rise more than 80%, ahead of the 77% analysts expected. TD Cowen said the outlook shows AI spending extending beyond Nvidia's accelerators, while the stock has gained about 126% this year.
CVS to split into two companies. The company will separate its retail pharmacy business from its insurance and pharmacy-benefit operations by the first half of 2028, unwinding much of its $78 billion Aetna deal. Healthcare solutions, including Aetna and Caremark, will keep the CVS Health name under CEO David Joyner, while Prem Shah will lead CVS Pharmacy. Morningstar's Julie Utterback said the timing reflects moving "from a place of strength."
SpaceX adds Qualcomm to its mobile push. Qualcomm will supply base-station technology for Starlink Mobile, with a rollout planned to begin next year and terms undisclosed. SpaceX, valued at close to $2 trillion after its June IPO, has been buying spectrum and held talks to acquire EchoStar's Boost Mobile. Starlink made up 36% of third-quarter revenue and 85% of operating profit.
Novo Nordisk raises guidance again. Wegovy pill sales of DKK 5.4 billion beat the roughly DKK 4.6 billion expected, and adjusted sales and operating profit growth are now seen at -2% to +2%. Management gave no 2027 guidance, warned of U.S. price erosion of 10% to 15% for Ozempic and 30% to 35% for Wegovy, and said CFO Karsten Munk Knudsen will leave at year-end, with Luigi La Corte succeeding him.
Crypto steadies after election-night dip. Binance customers withdrew a net $4.72 billion after the exchange reopened following a hack of about $6 billion, the largest in crypto history, which triggered the biggest weekly bitcoin ETF outflow since early July at $884 million. Tim Sun of HashKey said the market faces "strong headwinds," and the crypto sector spent more than $300 million backing candidates of both parties.
Eyes on the Treasury auction sizes, Qualcomm after the close, and Friday's payrolls report.
Related post