The Wall Street Wrap: November 2, 2026
US stocks were mixed on Monday as the Nasdaq Composite fell 1.07% on a chip selloff after Marvell agreed to buy Lumentum for $115 billion and Oracle filed to sell $20 billion of stock and notes, while the Dow rose 0.41%. Crude oil fell 7.43% on hopes for US-Iran talks, sending energy down 3.93%, and Apple and Palantir reported after the close. Overseas, South Korea unveiled a record budget and Ryanair warned of higher fares.
Oil's 7% plunge on Iran diplomacy drags energy down almost 4% and Marvell's $115 billion Lumentum deal hits chip stocks, while the Dow rises on consumer, industrial, and materials strength
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
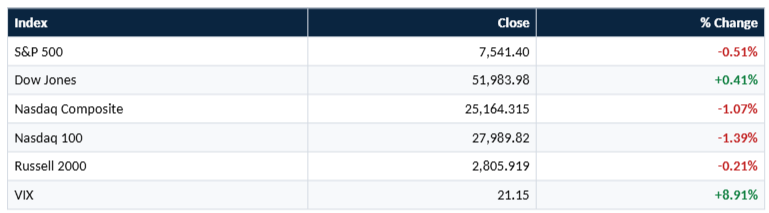
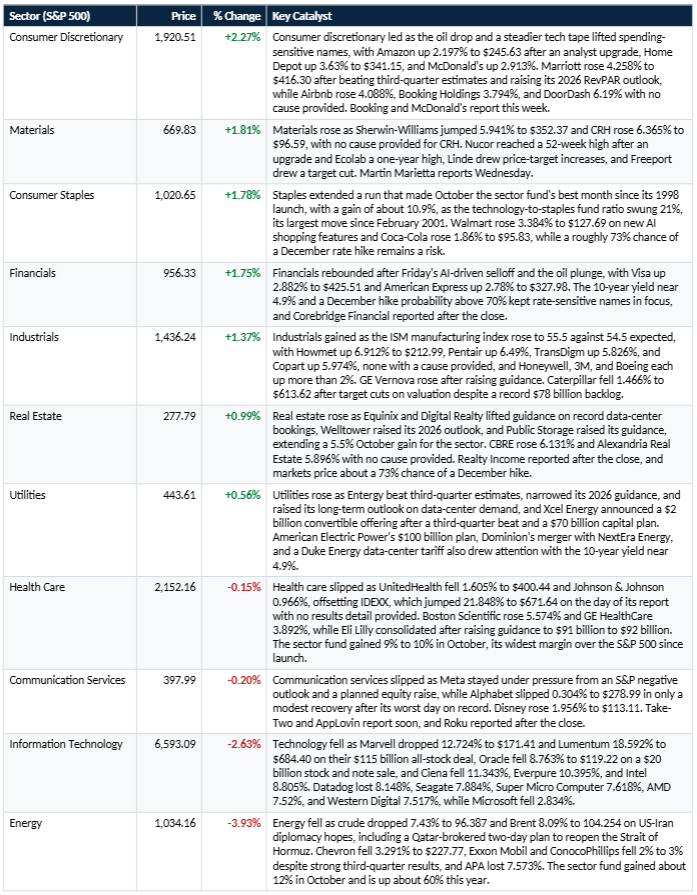
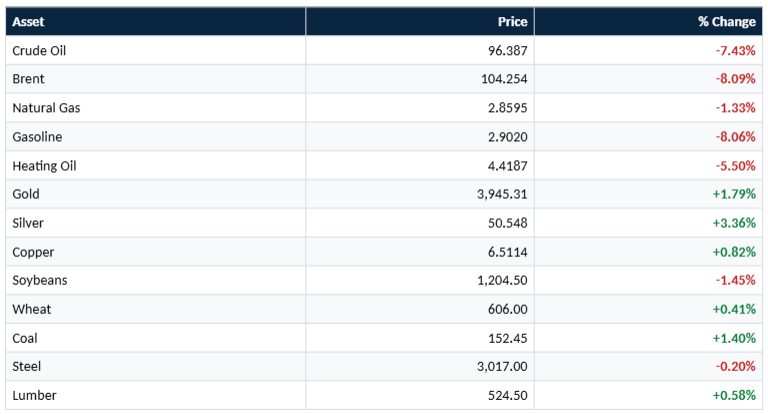
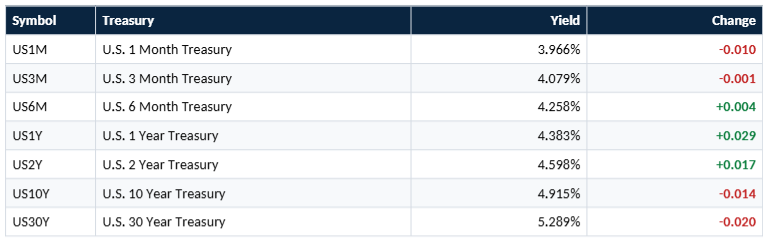
US stocks were mixed on Monday as a rotation out of technology and an oil-price plunge on hopes for US-Iran talks split the market, with the Dow Jones Industrial Average rising while chip and AI-related shares led the Nasdaq lower. The S&P 500 fell 0.51% to 7,541.40 and the Nasdaq Composite lost 1.07% to 25,164.315, while the Nasdaq 100 fell 1.39% to 27,989.82, the Dow rose 0.41% to 51,983.98, and the Russell 2000 slipped 0.21% to 2,805.919. The VIX rose 8.91% to 21.15. Seven of the 11 S&P 500 sectors rose, led by consumer discretionary at 2.27%, materials at 1.81%, and consumer staples at 1.78%, while energy fell 3.93% and information technology 2.63%. IDEXX rose 21.848% and Howmet Aerospace 6.912%, while Lumentum fell 18.592% and Marvell Technology 12.724%. The 10-year Treasury yield eased to 4.915%, crude oil fell 7.43% to 96.387, and gold rose 1.79% to 3,945.31.
ANALYTICAL VIEW
The selling that began last week in chips and AI infrastructure continued, but money moved to other corners of the market rather than leaving it. Marvell Technology fell 12.724% and Lumentum 18.592% after Marvell agreed to buy its optical-components supplier in a $115 billion all-stock deal, Oracle fell 8.763% after filing to sell $10 billion of common stock and $10 billion of notes, and Intel fell another 8.805% after Friday's 29% plunge and a 45% drop in October, its worst month on record. AMD fell 7.52% ahead of its Tuesday results, Western Digital 7.517%, and Seagate 7.884%, while Microsoft fell 2.834% and Apple 1.831% before its report. Information technology fell 2.63%, and a technology sector fund's October decline of about 8.3% was its worst month since March 2025.
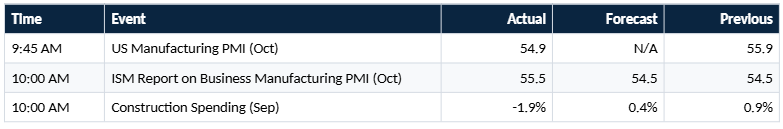
Cyclical and defensive shares took the other side. Home Depot rose 3.63%, Sherwin-Williams 5.941%, Walmart 3.384%, McDonald's 2.913%, and Visa 2.882%, lifting the Dow, and an equity strategist said the market's "ability to bend but not break under pressure has been a positive sign." The ISM manufacturing PMI rose to 55.5 against 54.5 expected, though construction spending fell 1.9% in September, its biggest monthly drop since April 2020. Crude fell 7.43% to 96.387 and Brent 8.09% to 104.254 after President Donald Trump said Iran wants a deal, pulling energy down 3.93% even as Exxon Mobil, Chevron, and ConocoPhillips each fell only 2% to 3% on strong third-quarter results, while gold rose 1.79% and silver 3.36%. The 10-year Treasury yield eased to 4.915%, and markets still price roughly a 70% to 73% chance of a December rate increase.
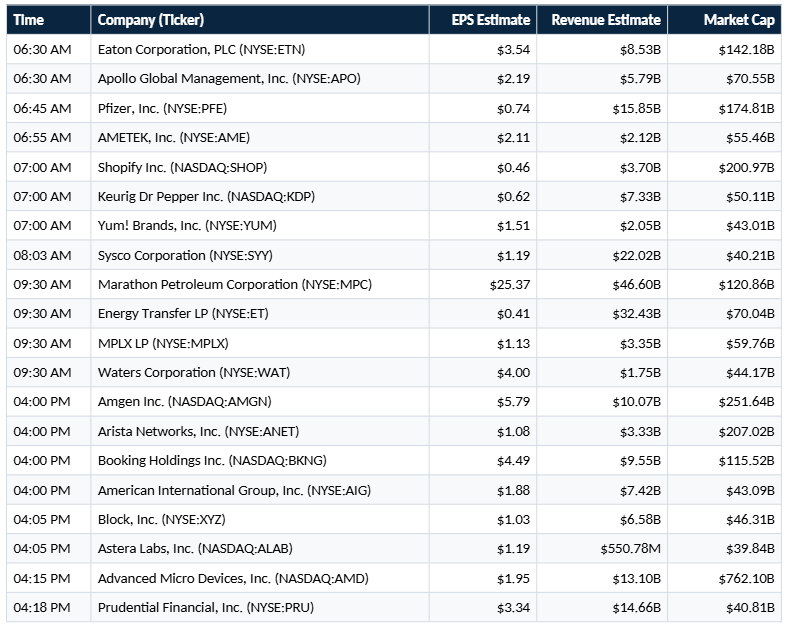
What could change the picture: Whether crude's drop on Iran diplomacy holds once Tuesday's midterm elections pass, whether results from AMD, Pfizer, Amgen, and Arista Networks on Tuesday steady the chip and AI trade after Apple and Palantir, and whether the jobs data later this week firms up the case for a December rate hike with the 10-year Treasury yield at 4.915%.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- IDEXX Laboratories, Inc. (NASDAQ:IDXX): +21.848%
- Howmet Aerospace Inc. (NYSE:HWM): +6.912%
- Pentair plc (NYSE:PNR): +6.49%
- CRH PLC (NYSE:CRH): +6.365%
- DoorDash, Inc. (NASDAQ:DASH): +6.19%
Top 5 Decliners:
- Lumentum Holdings Inc. (NASDAQ:LITE): -18.592%
- Marvell Technology, Inc. (NASDAQ:MRVL): -12.724%
- Ciena Corporation (NYSE:CIEN): -11.343%
- Everpure, Inc. (NYSE:P): -10.395%
- Intel Corporation (NASDAQ:INTC): -8.805%
Note: Lumentum and Marvell fell after Marvell agreed to buy Lumentum in a $115 billion all-stock deal, and Intel extended its slide after Friday's 29% plunge and a 45% drop in October. IDEXX jumped on the day of its third-quarter report, though no results were provided. No specific cause was provided for the moves in Howmet, Pentair, CRH, DoorDash, Ciena, or Everpure.
AFTER-HOURS MOVERS
Gainers:
- Upwork Inc. (NASDAQ:UPWK), +15.54% after hours: Shares rose to $11.23 after third-quarter adjusted earnings of $0.40 a share beat the $0.31 estimate and revenue of $185.6 million topped the $180.2 million expected. The company raised its full-year adjusted earnings guidance to $1.45 to $1.47 a share, narrowed its revenue outlook to $742 million to $750 million, and guided fourth-quarter revenue to $169 million to $177 million. The stock had closed 6.23% higher at $9.72.
- Harmonic Inc. (NASDAQ:HLIT), +15.41% after hours: Shares rose to $11.76 after third-quarter adjusted earnings of $0.23 a share topped the $0.17 consensus and revenue of about $148.8 million beat the roughly $129.5 million expected. The report followed a second quarter with record backlog of $587.6 million and raised broadband guidance, and investors had questioned whether that backlog would convert into sustained growth. The stock had closed 0.39% lower at $10.19.
- Aehr Test Systems (NASDAQ:AEHR), +15.23% after hours: Shares rose to $59.31 after fiscal first-quarter adjusted earnings of $0.28 a share beat the roughly $0.11 expected and revenue of $33.0 million, up about 200% from a year earlier, topped the $27 million estimate. The company raised its fiscal 2027 sales outlook to $150 million from a prior range of $130 million to $150 million, against a $137 million consensus. The stock had closed 6.23% lower at $51.47.
- Ibotta, Inc. (NYSE:IBTA), +10.84% after hours: Shares rose to $55.50 after third-quarter revenue of $97.8 million, up about 17.5% from a year earlier, topped the roughly $88.6 million consensus, with adjusted earnings of $0.62 a share against estimates of $0.38 to $0.44. Fourth-quarter revenue guidance of $94 million to $98 million was above the $93.4 million estimate. The stock had closed 2.98% higher at $50.07, near its 52-week high.
- Ethos Technologies Inc. (NASDAQ:LIFE), +10.28% after hours: Shares rose to $47.00 after third-quarter revenue rose 151% to $235.2 million, above the $169.05 million expected, with net income of $4.7 million, adjusted EBITDA of $34.9 million, and non-GAAP earnings of $0.49 a share. The company activated 142,111 new policies, up 189% from a year earlier, and its board authorized a share repurchase of up to $100 million. The stock had closed 1.77% lower at $42.62.
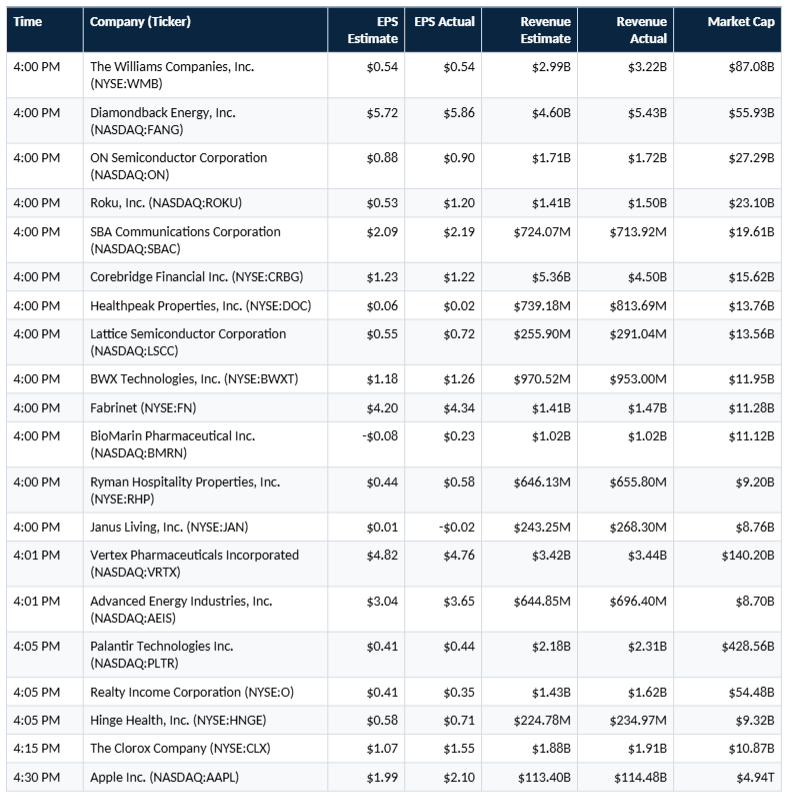
- Palantir Technologies Inc. (NASDAQ:PLTR), +0.59% after hours: Shares rose to $179.40 after third-quarter adjusted earnings of $0.44 a share beat the $0.41 estimate and revenue of $2.31 billion, up 96%, topped the $2.18 billion expected, with US commercial revenue up 148% to $984 million, surpassing US government revenue of $953 million for the first time. Fourth-quarter revenue guidance of about $2.65 billion and full-year guidance of about $8.53 billion were above the $8.21 billion consensus for the year. The stock had closed 3.13% lower at $178.34.
Decliners:
- Adeia Inc. (NASDAQ:ADEA), -19.16% after hours: Shares fell to $16.71 after third-quarter revenue of $80.2 million fell from $87.3 million a year earlier and $96.1 million in the second quarter, with adjusted earnings of $0.21 a share. The company lowered its 2026 revenue outlook to $375 million to $415 million from $395 million to $435 million, though it said it remains confident of reaching the high end and reiterated a $600 million long-term annual revenue outlook. It also named Dipti Vachani chief executive, succeeding Paul Davis. The stock had closed 3.59% lower at $20.67.
- Bioventus Inc. (NASDAQ:BVS), -18.59% after hours: Shares fell to $10.71 after third-quarter revenue of $142.4 million, up 3%, fell short of the $149.51 million expected, even though adjusted earnings of $0.17 a share beat the $0.15 estimate and adjusted EBITDA rose 7% to $28.4 million. The company continues to review strategic alternatives. The stock had closed 1.31% lower at $13.15.
- BioMarin Pharmaceutical Inc. (NASDAQ:BMRN), -6.04% after hours: Shares fell to $53.97 after the company cut its 2026 adjusted earnings guidance to $2.80 to $3.10 a share from $4.90 to $5.10, against a $3.32 estimate, and trimmed its sales outlook to $3.80 billion to $3.90 billion from $3.875 billion to $3.925 billion. Third-quarter revenue of about $1.025 billion, up 32% on the Amicus acquisition, was roughly in line with the $1.02 billion consensus, with adjusted earnings of $0.23 a share. The stock had closed 1.83% lower at $57.44.
- ON Semiconductor Corporation (NASDAQ:ON), -5.41% after hours: Shares fell to $66.32 even though third-quarter earnings of $0.90 a share beat the $0.88 estimate and revenue of $1.72 billion topped the $1.71 billion expected. Investors were focused on gross margin progress toward a 42% to 43% range, fourth-quarter guidance, and cash given the amended all-cash Synaptics deal of about $5.7 billion and reported talks to buy Ferric. The stock had closed 2.18% lower at $70.11.
- Apple Inc. (NASDAQ:AAPL), -0.54% after hours: Shares fell to $336.50 after fiscal fourth-quarter earnings of $2.10 a share beat the $1.99 estimate and revenue of $114.48 billion topped the $113.40 billion expected, in the first report under Chief Executive John Ternus. Investors weighed the holiday-quarter outlook, demand for the new iPhone Duo, and rising memory-chip costs against a premium valuation, and options had implied a move of about 4%. The stock had closed 1.83% lower at $338.32.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Stocks rotate out of technology as the Dow outperforms and Intel extends its slide. The Nasdaq Composite fell 1.07% and the S&P 500 0.51% while the Dow rose 213.67 points, or 0.41%, as investors added exposure to other parts of the market after a losing October for technology. Home Depot rose 3.63% and Sherwin-Williams 5.941%, and Honeywell, 3M, and Boeing each gained more than 2%, while Intel fell 8.805% to $59.97, extending Friday's 29% plunge and a 45% drop in October that was its worst month on record. Intel is shifting some Oregon factory capacity from its advanced 18A process to older Intel 3 wafers for server chips, and a Harvard Business School professor and former Intel director said spinning off the foundry business may be "the only solution" to its lack of a marquee customer. Chief Executive Lip-Bu Tan has said "a couple customers" would be announced in the next two quarters.
Marvell agrees to buy Lumentum for $115 billion in one of the year's biggest AI connectivity bets. The all-stock deal implies an enterprise value of $115 billion, with Lumentum shareholders receiving 4.5 Marvell shares for each share held and owning about 33% of the combined company. Marvell expects the deal to close in the first half of 2028, to generate more than $1 billion in annual cost synergies, and to expand its addressable market to $550 billion. Marvell fell 12.724% to $171.41 and Lumentum 18.592% to $684.40, though Marvell edged up 0.37% after hours, and both stocks had been big winners in the AI boom, with Lumentum quadrupling over the past year before Monday's selloff. Marvell closed a multibillion-dollar deal for optical-interconnect startup Celestial AI earlier this year.
Oracle falls 8.8% after filing to sell $10 billion of stock and $10 billion of notes. The company filed on Monday for the stock and senior notes sales, with Wells Fargo, Citigroup, and BNP Paribas among the book runners, and plans to use the proceeds for general corporate purposes including capital spending and debt repayment. The raise was previewed at last week's investor day, when Oracle said it would limit additional capital-market funding to $20 billion over its fiscal 2027 to 2030 investment cycle, and a research analyst said "I'm not sure why the market is freaking about it." Shares fell 8.763% to $119.22 and are down 33% this year, Oracle's five-year credit default swaps stand at 296, up 270% in a year, and S&P rates the company BBB-, one level above junk, with $125.34 billion of debt as of August 31.
Crude oil falls more than 7% as Washington and Tehran signal openness to talks. West Texas Intermediate fell 7.43% to 96.387 a barrel, its biggest daily loss since July 27, and Brent fell 8.09% to 104.254, after Trump said Iran wants to make a deal and Iranian President Masoud Pezeshkian said Tehran is seeking to resolve problems through dialogue. Iran's foreign minister said an agreement is possible if Washington demonstrates goodwill, and mediators are discussing a proposal under which the US would lift sanctions, reduce its military presence, and lift the blockade. Oil had gained more than 10% in October on fears of escalation after Tuesday's midterm elections, and a commodity strategist at a bank said the risk premium will not fully erode on diplomacy headlines alone while tanker and Houthi attacks continue.
Anthropic reports $17 billion in third-quarter revenue and $895.4 billion of purchase commitments in an amended IPO filing. The amended Form S-1 showed revenue of $33.24 billion for the first nine months, up roughly 1,200% from a year earlier, and a net loss of $104 billion, most of it from changes in the fair value of convertible notes and derivative liabilities. Third-quarter revenue was about $17 billion, up about 1,127% from a year earlier but up only 47% from the second quarter, after sequential growth of 144% in the second quarter and 132% in the first, and the third-quarter net loss was $23.29 billion. Aggregate committed spend on purchase commitments and leases was about $895.4 billion, substantially all for compute and infrastructure. The filing arrives after Microsoft, Alphabet, and Amazon results last week renewed worries about AI funding, with Microsoft cutting its capital spending forecast to $170 billion from $175 billion.
Also today: The ISM manufacturing index rose to 55.5 from 54.5 in September, above the 54.5 consensus, with production up 2.3 points to 59.0, inventories up 2.8 points to 51.4, order backlogs down 1.8 points to 54.6, employment at 52.3, and the prices index down 2.7 points to 75.2; S&P Global's US manufacturing PMI came in at 54.9 against 55.9 in September; construction spending fell 1.9% in September, its biggest monthly decline since April 2020 against a 0.4% gain expected, with residential spending down 5.5%, nonresidential up 0.6%, and total spending down 2.7% from a year earlier; Apollo Global Management launched European Credit Company, a EUR10 billion ($11.2 billion) private credit platform backed by the Abu Dhabi Investment Council, Athora, Norinchukin Bank, Standard Chartered, and Aranda Principal Strategies, a week after agreeing to buy nearly 10% of Mubadala Capital; traders on Kalshi put the chance of Democrats winning the Senate at 74%, the highest since the market opened, after a poll showed Democrats leading in several battleground states; JPMorgan gave a Democratic sweep a 66% likelihood with the S&P 500 between down 0.25% and up 0.50%, a Democratic House with a Republican Senate 26% with a 0.5% to 1% gain, and a Republican hold 7% with a 1% to 1.25% gain; the Justice Department asked the Supreme Court to temporarily block California from counting mail-in ballots of about 20,000 voters it suggests may not be US citizens, three days after the 9th Circuit rejected its bid in a 2-1 ruling; Texas Governor Greg Abbott has a 60% chance of beating Democrat Gina Hinojosa on Kalshi, with her odds up from 8% in July to 40%, data-center development a campaign issue and more than 7.7 million Texans already voting early.
TOP STORIES: GLOBAL
Asian markets close mixed as South Korea unveils a record budget. South Korea's Kospi rose 2.38% to 5,859.08 and the Kosdaq 1.38%, Japan's Nikkei 225 gained 0.33% to 63,081.86, and China's CSI 300 added 0.79%, while Australia's S&P/ASX 200 fell 0.58% to 8,856.5. President Lee Jae Myung proposed record 2027 spending of 820.9 trillion won ($610.14 billion), up 12.8%, including 21.3 trillion won for semiconductors, physical AI, and AI data centers, nearly double the 2026 level, and 4.7 trillion won for a sovereign AI model. October exports jumped 93.7% from a year earlier to a record $115.3 billion, shipments totaled $930 billion in the first 10 months, and the trade surplus reached $42.5 billion.
European and UK factory activity beats expectations. The euro zone manufacturing PMI came in at 52.7 against 52.4 expected, down slightly from September's four-year high of 52.9, and an S&P Global economist said it pointed to the strongest run of manufacturing growth in more than four years, helped by defense spending, inventory building, and shifting trade patterns. UK manufacturing output expanded at its fastest pace in more than two years in October, with new orders growing faster and business confidence at an eight-month high, though cost pressures and supply disruption stayed elevated and a six-month run of rising hiring halted.
Ryanair warns European fares could rise by up to 20% next year as fuel hedges roll off. Chief Executive Michael O'Leary said fares across Europe could rise 10% and possibly 20% in 2027, with jet fuel at about $170 a barrel and no resolution in the Middle East. Profit fell 15% to EUR2.15 billion in the first fiscal half as the price of its unhedged fuel doubled, and the airline said higher fares would not fully offset an estimated EUR2 billion rise in fuel costs, so it is launching a cost review that includes lowering crew rations, a potential temporary pay freeze, and AI-driven efficiencies. Winter capacity will be flat, cash stood at EUR2.6 billion, and Irish-listed shares rose 3.7% while the US-listed shares closed 2.92% higher at $55.29.
Binance sees $3.64 billion of net outflows after reopening withdrawals. The exchange processed $4.65 billion of withdrawals and $1.01 billion of deposits on Sunday, a net outflow equal to 2.1% of its $171 billion of assets, and said withdrawal volumes were stabilizing. It said it has covered about 95% of the amount affected by last week's $6.3 billion hack, up from 90%, with the rest in less liquid tokens that will take longer to source, while Circle said it froze more than $1.1 billion of USDC linked to the incident. The FBI attributed the attack to North Korean hackers in an operation it identified as TraderTraitor, and Binance said it will absorb the losses rather than pass them on to users.
MANAGEMENT & FED SPEAK
Matt Murphy, Chairman and Chief Executive Officer, Marvell Technology, on the Lumentum deal:
Murphy said "AI infrastructure is undergoing a fundamental architectural shift toward optical connectivity," arguing that combining two complementary technologies will create a new category of company. He dismissed concerns about Nvidia's circular dealmaking, calling the deal "a double down on supporting Nvidia" and saying the partnership remains central.
Michael O'Leary, Chief Executive Officer, Ryanair, on fares and fuel:
O'Leary called the expiry of fuel hedges "a very significant cost cliff we're all facing next year," with jet fuel at about $170 a barrel. He expects airfares across Europe to rise 10% and perhaps 20%, and said Ryanair is cutting winter capacity for the first time in many years because buying unhedged fuel at those prices makes growth uneconomic.
Marco Rubio, Secretary of State, on Iran:
Rubio said Trump "hasn't made a decision" on whether to strike Iran again and expressed confidence that the US could act militarily if needed, but said "we would prefer to do it peacefully." He spoke over the weekend, as reports suggested both sides were preparing for further strikes after the midterm elections.
Donald Trump, President of the United States, on Iran:
Trump told reporters on Monday that Iran wants to "make a deal and that could happen." In an interview on Sunday he said "Either they'll make a deal, or we'll just end it," adding that the US would put the conflict away "very soon, one way or the other."
Kevin Warsh, Chairman, Federal Reserve, on the meeting schedule:
Warsh said at his October 28 news conference that the Fed will keep meeting eight times a year but that one meeting in 2027 will not include a rate vote or post-meeting statement, rising to two meetings in 2028 and leaving six opportunities to adjust rates. Economists said the change, along with his curbs on forward guidance, could leave borrowers waiting longer for relief and give the public less insight into decisions.
CORPORATE ACTIONS & EARNINGS CALENDAR
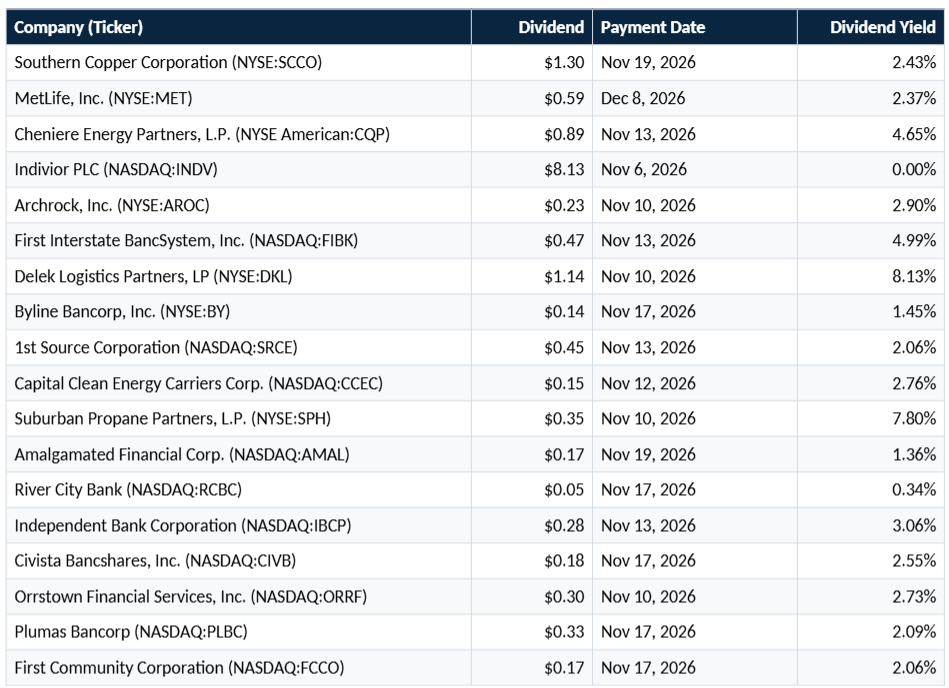
Top Ex-Dividend Companies for Tuesday, November 3:
Earnings Reported After the Close (Monday, November 2):
Upcoming Earnings (Tuesday, November 3):
Economic Calendar (Monday, November 2):
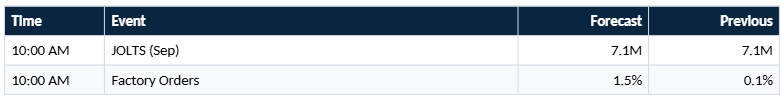
Economic Calendar (Tuesday, November 3):
That's the wrap for today! Attention turns to Tuesday's US midterm elections, results from AMD, Pfizer, Amgen, Arista Networks, and Shopify, and whether the rotation out of technology and the slide in oil hold.