Wall Street Wrap: Pre-Market, October 2, 2026
U.S. futures jump as a weak September jobs report (just 29,000 added) sharply cools Fed rate-hike bets and sends Treasury yields and oil tumbling. Synaptics, ON Semiconductor, and Moderna lead pre-market gainers, while Nike, Seagate, and Western Digital slide on guidance cuts and a Toshiba capacity threat.
Futures extend gains as a weak jobs report cools rate-hike bets and oil tumbles
Stock futures rose Friday as traders assessed a weaker-than-expected September jobs report, which sharply reduced bets on another Fed rate hike this month and sent Treasury yields and oil prices lower.
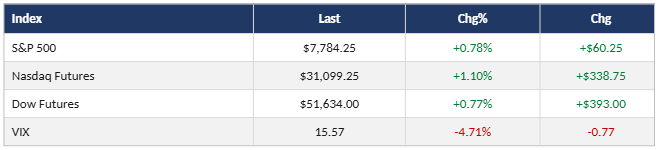
Futures Snapshot
What's Driving the Open
September's nonfarm payrolls report showed U.S. employers added just 29,000 jobs, far below the 84,000-90,000 economists had expected, while the unemployment rate rose to 4.2% from 4.1%. August's gain was revised down to 133,000 from a previously reported 162,000; July was revised down to a loss of 10,000. Average hourly earnings rose just 0.1% month-over-month to $37.81, below the 0.3% expected, with annual wage growth slowing to 3.0%, its weakest since May 2021.
Economists cautioned the weak print likely reflects a calendar quirk rather than a material shift in the labor market — payrolls tend to underperform when Labor Day falls late in the month, as it did this year — rather than a broad deterioration, noting jobless claims remain near 57-year lows. Still, the data reduced expectations the Fed will hike again at its October 27-28 meeting: CME's FedWatch tool put the odds at roughly 22-28% Friday, down sharply from about 69-72% a week earlier.
Treasury yields tumbled on the news, with the 10-year falling as much as 7 basis points intraday to around 5.175-5.18%, retreating further from this week's peak above 5.34%, its highest since 2002. Oil extended losses as well, with Brent slipping back below $100 a barrel, on reports that European Union states are weighing a French proposal, following US pressure, to release diesel and crude reserves to ease a global supply shortage.
Despite the volatility, Luca Paolini, chief strategist at Pictet Asset Management, said he expects global stocks to "power on" on strong earnings momentum, noting MSCI World companies are on track for earnings growth of more than 30% this year. All three major indexes remain on track for a weekly loss regardless, with the S&P 500 down around 1.2%, the Dow off roughly 1.7-1.8%, and the Nasdaq down about 0.8%.
What could change the picture: Any signs the weak jobs number reflects more than a calendar quirk could unsettle the relief rally; a resolution on European fuel-reserve releases or further softening in oil would reinforce it.
Overnight Markets
Asian stocks closed mixed Friday as Middle East tensions and elevated bond yields kept investors on edge. Japan's Nikkei 225 lost 0.94% to 68,309.46, while the Topix closed 0.99% lower at 4,091. South Korea's Kospi rose 0.46% to 7,003.74, while the small-cap Kosdaq slid 0.11% to 893.29. Australia's S&P/ASX 200 added 0.79% to 8,682.1. Hong Kong's Hang Seng index was 2.8% lower in its last hour of trade. Mainland China markets were closed for a holiday.
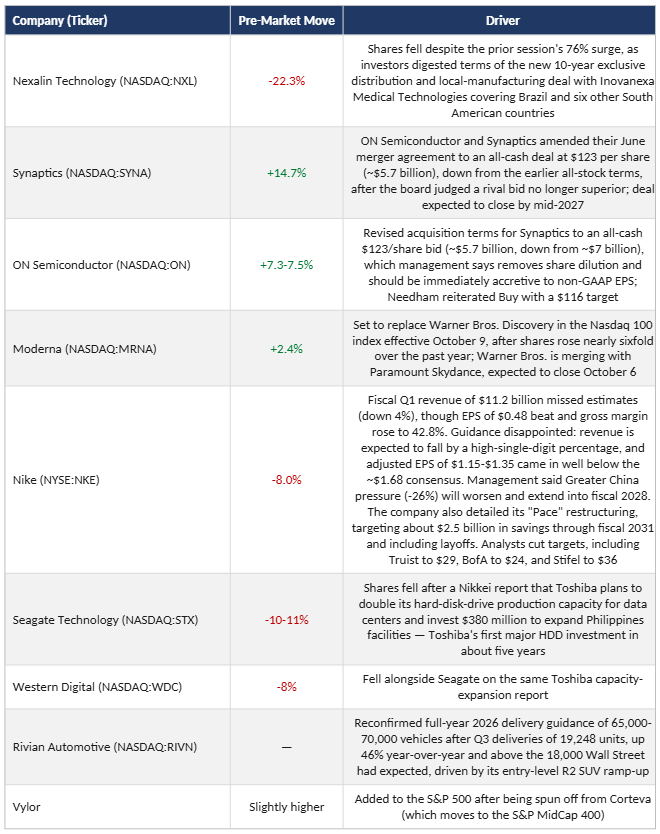
Pre-Market Movers
Rates, FX & Crypto
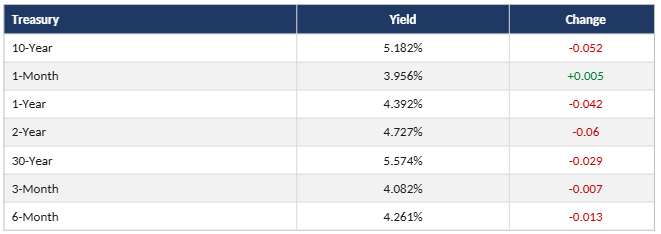
The 10-year yield fell nearly 6 basis points to around 5.18% after reaching its highest level since 2002 earlier this week; the 30-year fell 3 basis points to 5.57%; the 2-year, most sensitive to Fed policy, fell 6 basis points to about 4.73%. Government bond yields eased elsewhere too, with 10-year yields down around 3 basis points across major European economies.
Commodities
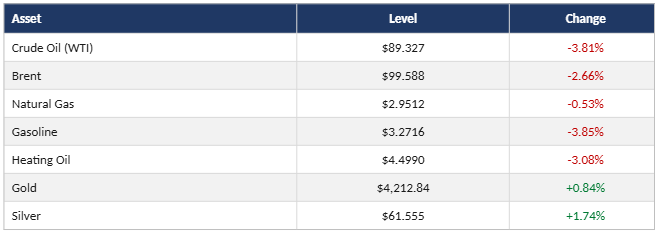
Oil fell sharply on reports that EU member states are discussing a French proposal to release additional diesel reserves, following pressure from the Trump administration, with the aim of easing a global fuel supply shortage. Gold rebounded above $4,200 on the weak jobs data, as reduced odds of a near-term rate hike boosted the metal's appeal.
Key Levels & Catalysts Today
Economic data
- Nonfarm payrolls rose just 29,000 in September, versus the 84,000-90,000 expected, with increases concentrated in health care (+17,000), construction (+11,000), and manufacturing (+9,000), while financial activities fell (-7,000). July was revised down by 31,000 to a loss of 10,000, and August was revised down by 29,000 to +133,000 — a combined 60,000 lower than previously reported.
- The unemployment rate rose to 4.2% from 4.1%, slightly above the 4.1% expected. Total employment rose 406,000 to 163.15 million; the labor force grew 485,000 to 170.26 million, lifting the participation rate to 61.8% from 61.6%. The broader U-6 rate eased to 7.6% from 7.7%.
- Average hourly earnings rose 0.1% month-over-month to $37.81, below the 0.3% forecast; production and nonsupervisory employee earnings rose 0.2% to $32.60. Year-over-year wage growth slowed to 3.0%.
Corporate
- Novartis (NYSE:NVS) signed a licensing deal worth up to $7.8 billion with Chinese biotech Abogen to develop mRNA-based autoimmune therapy, gaining exclusive rights to Abogen's experimental ABO2203 and options on other RNA-based treatments; Abogen receives $575 million upfront with up to $7.2 billion in potential milestones. The deal follows a roughly $30 billion market-value hit Novartis took in September after two late-stage trial failures prompted shareholder calls for tighter M&A oversight.
- Nvidia (NASDAQ:NVDA) was named Morgan Stanley's top semiconductor pick Friday, with analyst Joseph Moore citing the breadth of AI customers beyond major hyperscalers (overweight rating, $300 price target).
- Brazil holds the first round of a closely watched presidential election October 4, with incumbent Luiz Inácio Lula da Silva and Senator Flávio Bolsonaro leading the polls; the outcome could shape Brazil's trade and critical-minerals relationships with the US and China.
Top Stories
Russia and China tighten the squeeze on global diesel supply. Russian President Vladimir Putin said he will not sell diesel internationally until Western sanctions on Russia are lifted, a response to the export ban Moscow imposed after Ukrainian strikes on its refineries. Chinese refiners have also suspended fuel exports for October. The US reportedly told France and Germany to release their own diesel reserves or face export restrictions on American stocks.
The US sends up to 10,000 more troops to the Middle East. The deployment, including a third aircraft carrier, is expected to arrive by the end of November as President Trump weighs whether to resume strikes on Iran. Trump has rejected an Iranian ceasefire proposal and said attacks could resume after the November 3 midterm elections.
The ISM manufacturing survey flags rising tariff anxiety. A Thursday survey showed growing concern among US manufacturers over the trade war with Canada, adding to headwinds including record-high diesel prices that economists expect could begin disrupting the broader labor market by year-end and into 2027.
Eyes on how markets digest the jobs-report-driven repricing of Fed expectations into next week, and on Brazil's October 4 election as a potential swing factor for US-China-Brazil trade dynamics.
Related post