Wall Street Wrap: Pre-Market, October 28, 2026
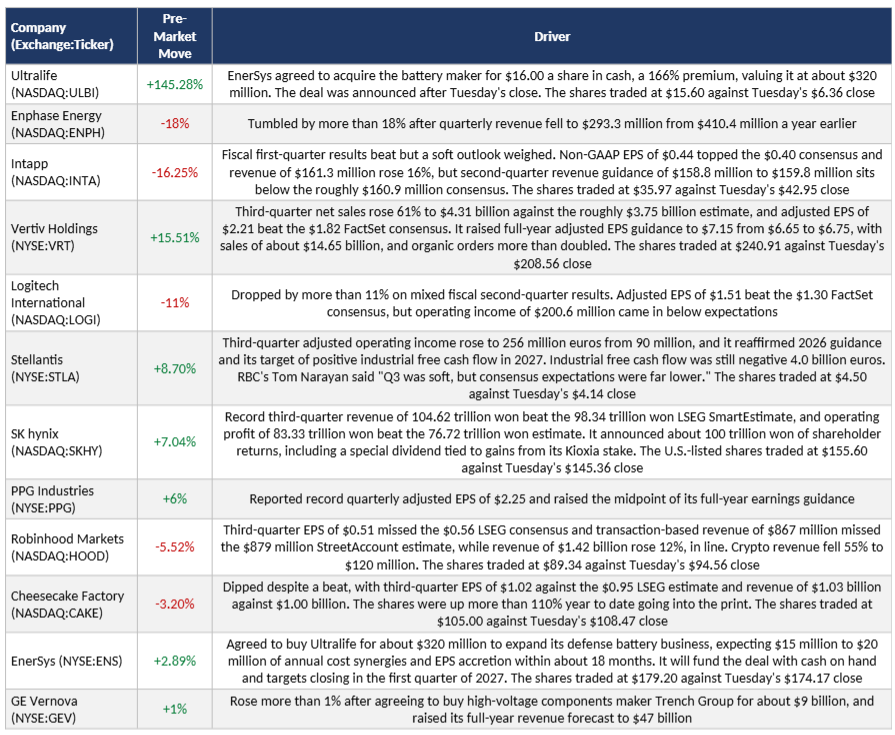
U.S. stock futures edge higher on Wednesday ahead of the Fed decision and Alphabet and Microsoft earnings, as Ultralife surges on an EnerSys bid, Vertiv and SK hynix jump on strong results, and Intapp and Enphase sink.
Futures edge higher ahead of the Fed decision, Ultralife leaps on an EnerSys bid, and SK hynix's record profit lifts chip stocks
Wall Street looks set for a slightly higher open on Wednesday as investors await the Federal Reserve's rate decision at 2 p.m. ET and results from Alphabet (NASDAQ:GOOGL) and Microsoft (NASDAQ:MSFT) after the close.
Futures Snapshot
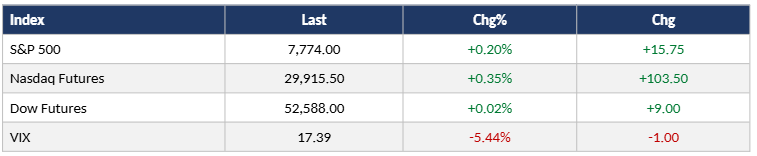
Futures were modestly higher early Wednesday, with the Nasdaq leading and the VIX lower as traders positioned for the Fed and Big Tech earnings.
What's Driving the Open
The Fed wraps up its two-day meeting and is widely expected to hold its target range at 3.75% to 4%, after raising rates by a quarter point in September. CME's FedWatch tool shows a roughly 90% chance of no change, but some investors expect Chair Kevin Warsh to signal that more hikes are coming, and markets are pricing about an 80% to 84% chance of a December hike. The 10-year Treasury yield sits near 5%, and Thursday's PCE inflation report and third-quarter GDP could test those expectations.
Chip stocks are leading premarket after a record quarterly profit from a South Korean memory maker, with Micron Technology (NASDAQ:MU) up 4%, Arm Holdings (NASDAQ:ARM) up 2% and Intel (NASDAQ:INTC), Marvell Technology (NASDAQ:MRVL) and Advanced Micro Devices (NASDAQ:AMD) each up almost 2%. Alphabet was up more than 1% and Microsoft down marginally. Tuesday's session set the tone, with the Nasdaq Composite up 1.2%, the S&P 500 up 0.6% to 7,722.60 and the Philadelphia Semiconductor Index up 3.6%, as Broadcom (NASDAQ:AVGO) gained 4% on a $63 billion Anthropic financing deal and the AI company's IPO filing lifted sentiment. Mike Wilson, Morgan Stanley's (NYSE:MS) chief U.S. equity strategist, said "most of the correction is already over" after four or five months of declines. Oil is higher after the Houthis said they hit Saudi Arabia's Ras Tanura refinery.
What could change the picture: A hawkish signal from Warsh would pressure rate-sensitive and AI-linked stocks, weak cloud or capex guidance from Alphabet and Microsoft would revive worries about AI spending, and an escalation in the Gulf would push oil higher and weigh on equities.
Overnight Markets
In Asia, markets were mostly higher. South Korea's Kospi jumped 6.63% as SK hynix closed 10.89% higher, Japan's Nikkei 225 closed 1.08% higher and mainland China's CSI 300 gained 0.85%, while Australia's S&P/ASX 200 was flat. In Europe, markets were slightly lower on Wednesday morning, with the Stoxx 600 down 0.27%, the U.K. FTSE 100 down 0.33%, the French CAC 40 down 0.13% and Germany's DAX down 0.11%.
Pre-Market Movers
Earnings Before the Bell
Rates, FX & Crypto
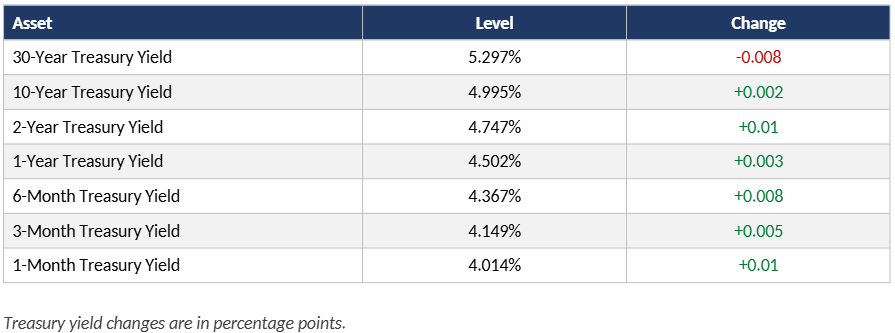
Yields were little changed, with the 10-year near 5% as investors await the Fed. The dollar index held near 102.4, a two-week high, while EUR/USD slid to about 1.1120, its weakest since May 2025, on a weak European Central Bank lending survey and French fiscal worries ahead of Thursday's ECB meeting.
Commodities
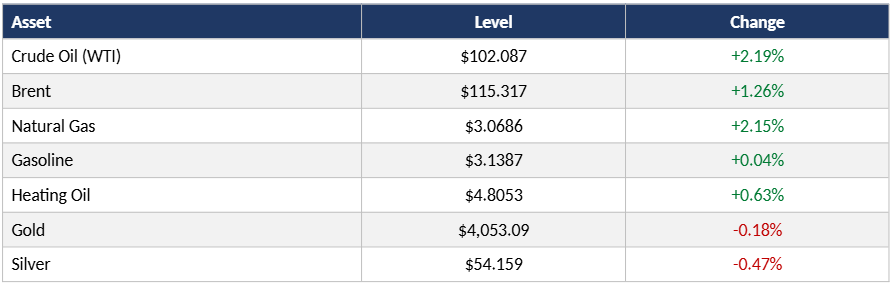
Oil rose after the Houthis said they struck Saudi Arabia's Ras Tanura refinery with a ballistic missile, reversing a roughly $2 drop on Tuesday tied to Iran peace-talk hopes. Goldman Sachs (NYSE:GS) sees $120 if shipping attacks escalate. President Trump said the war with Iran would end on his terms and that Tehran must be prevented from acquiring nuclear weapons.
Key Levels & Catalysts Today
Economic data
- The Fed announces its rate decision at 2 p.m. ET, with a hold at 3.75% to 4% expected.
- The U.S. goods trade deficit widened to $134.9 billion in September, the widest since March 2025, against a forecast of about $130 billion.
- Wholesale inventories rose 0.6% in September, above the 0.5% forecast.
- Mortgage applications rose 3.4% last week, breaking a seven-week decline, as the average 30-year fixed rate fell to 7.37% from 7.41%.
- Thursday brings the advance third-quarter GDP estimate, forecast to grow at a 3.2% annualized rate after 2.2% in the second quarter, and the PCE inflation report.
Corporate
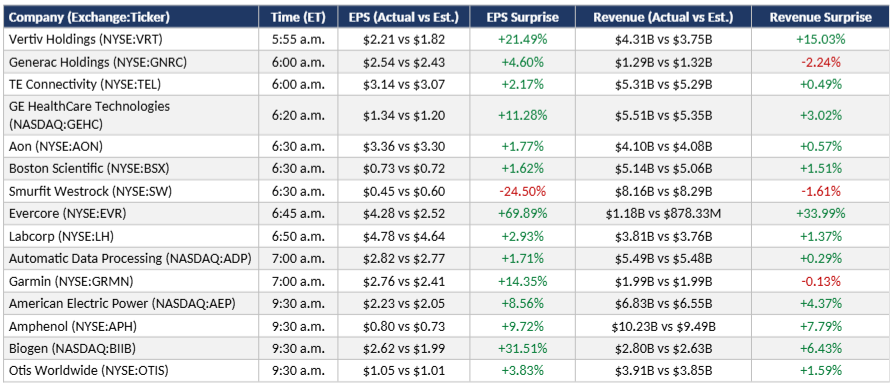
- Earnings before the bell are listed in the table above, including Vertiv, Boston Scientific, Garmin and Amphenol.
- Alphabet and Microsoft report after the close, and Samsung Electronics reports Thursday.
Top Stories
Google takes its AI chips outside its own data centers. A day before its earnings report, Alphabet said Oracle (NYSE:ORCL) will offer Google's tensor processing units, the first time customers can access them outside Google's infrastructure. TD Cowen models $9.4 billion of TPU sales in the second half of this year and $62.5 billion for 2027, though it estimates only a 20% operating margin on those sales against about 35% for cloud overall. Analysts expect Google Cloud revenue to jump about 90%. Anthropic is the biggest customer, with an agreement for up to 1 million TPUs, and Broadcom detailed a $63 billion vehicle backed by Blackstone (NYSE:BX) and three big banks to buy TPUs and networking gear and lease them to Anthropic for five years. OpenAI also plans to buy TPUs, according to a news report.
SK hynix posts a record profit and shelves its Solidigm IPO. The chipmaker's revenue rose 327.9% from a year earlier and operating profit climbed 632.1%, while it said it would return about 100 trillion won to shareholders. DRAM prices rose by a high-20s percentage from the previous quarter, shipments of server DDR5 chips rose more than 40%, and it has long-term agreements with 14 customers covering more than half its 2027 and 2028 capacity. It expects memory demand to outpace supply through 2030 and cited market volatility for halting its review of a U.S. listing for Solidigm. Samsung Electronics reports Thursday.
Trian offers to take Wendy's private. Nelson Peltz's Trian Fund Management leads a group offering $7.35 a share in cash for Wendy's (NASDAQ:WEN), valuing the burger chain at about $1.4 billion, a 20% premium to Tuesday's close, according to a regulatory filing. Trian is a longtime shareholder, and the company had a market value of about $1.2 billion on Tuesday.
Israel's election leaves no clear winner. Exit polls suggested neither Prime Minister Benjamin Netanyahu nor his main challenger, Gadi Eisenkot, would reach the 61 seats needed in the 120-seat parliament. Netanyahu's Likud may remain the largest party but is projected to shed perhaps a quarter of its seats. Protracted coalition talks would cloud the outlook for Israel's approach to Iran.
Mortgage demand rebounds as rates ease. Total mortgage application volume rose 3.4% last week, with refinancing up 3% and purchase applications up 4%, though refinancing was still 61% below a year earlier. A growing share of borrowers chose riskier adjustable-rate loans, with the ARM share rising to 11.3%, the highest in more than a year. Mortgage rates are still more than a percentage point above last year, and some agents say buyers are waiting for the midterm elections.
Eyes on the Fed's 2 p.m. decision, Alphabet and Microsoft results after the close, and Thursday's GDP and PCE data.
.png)