Wall Street Wrap: Pre-Market, September 30, 2026
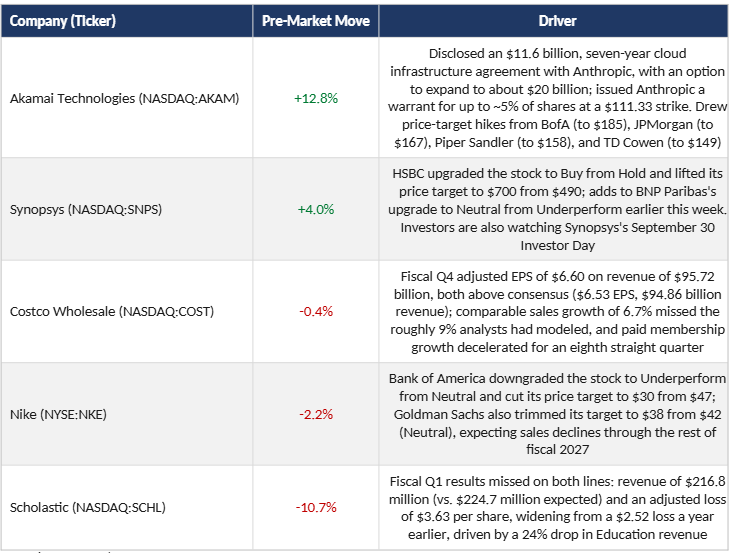
U.S. futures gain as August PCE inflation cools to 3.4%, pulling Treasury yields off their 2007/2002 highs on the last day of September. Boeing, Robinhood, and FormFactor lead pre-market gainers, while Concentrix, Moderna, and Cal-Maine slide, with Micron earnings due after the bell.
Futures gain as inflation slows, sending Treasury yields lower on the last day of September
Stock futures gained on Wednesday, the final day of September, after new U.S. economic data showed inflation slowed last month, sending Treasury yields lower.
Futures Snapshot
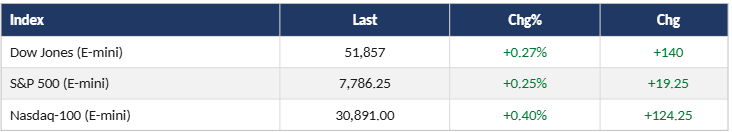
For the month, the S&P 500 and Dow are tracking for declines while the Nasdaq is up more than 1%. For the quarter, the S&P 500 and the Nasdaq are up 2%, while the Dow is off nearly 2%.
What's Driving the Open
The personal consumption expenditures price index for August increased at a 3.4% annual rate, down from 3.7% the month prior. Economists surveyed by Dow Jones had been looking for inflation to remain steady at 3.7%. Core PCE, excluding food and energy, rose 3% year on year, down from 3.3% the month before and also lower than economists had forecast.
The 10-year Treasury yield retreated from its highest since 2007 following the slowing inflation data and was last at 5.23%. The 30-year Treasury yield fell from levels not seen since June 2002. Higher yields have pressured stocks all month, with the S&P 500 in the red for September by 0.2% through Tuesday.
Odds of a Fed rate hike eased on Wednesday. CME Group's FedWatch tool shows traders pricing in a 47% chance of a quarter-point rate hike next month, down from 51% a day earlier. Traders are still expecting another hike in December despite the light inflation data.
Adam Hetts, Global Head of Multi-Asset and Portfolio Manager at Janus Henderson Investors, said in a statement that while the inflation data is somewhat better than expected, strong labor and GDP data suggest the print is unlikely to derail consensus expectations for another rate hike before year-end.
Strong private sector data offset the light inflation data: ADP said 90,000 jobs were added in September, much better than the 68,000 consensus estimate.
What could change the picture: Any further softening in inflation data, or a dovish shift in Fed commentary following this week's PCE reading, could extend the relief in yields; a stronger-than-expected jobs report could revive rate-hike bets ahead of the December meeting.
Overnight Markets
Japan's Nikkei 225 closed 1.94% higher at 66,753.72, while South Korea's Kospi fell 0.48% to 6,838.04. Australia's S&P/ASX 200 gained 0.92% to 8,789.30. Hong Kong's Hang Seng index was up 0.43% in the last hour of trade on Wednesday, while mainland China's CSI 300 closed 0.29% higher at 4,357.62.
Pre-Market Movers
Rates, FX & Crypto
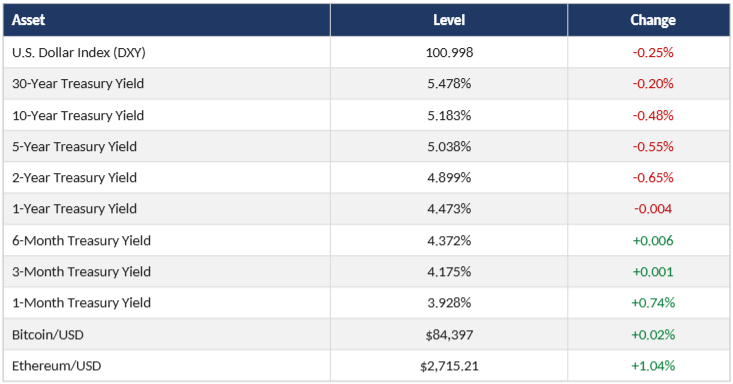
The 30-year Treasury bond was last nearly 3 basis points lower at 5.567%, after rising to its highest level since 2002 on Tuesday. The 10-year Treasury was down about 4 basis points to 5.217%, pulling back from its 2007 high, and the 2-year note yield was 5 basis points lower at 4.889%. (Note: these intraday levels differ slightly from the standing yield table above, which reflects a later snapshot.)
Commodities
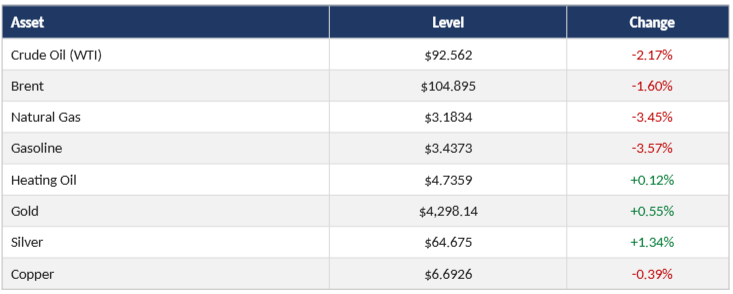
Brent is headed for a monthly gain of around 14%, its biggest climb since July, while WTI is on track for a 4% rise after having breached $106 for the first time since May. The spread between the two benchmarks has expanded to its widest in four months as traders watch potential U.S. plans to restrict diesel exports.
Key Levels & Catalysts Today
Economic data
- The US goods trade deficit widened to $132.6 billion in August 2026 from $118.9 billion in July — the largest deficit since March 2025's record $158.7 billion, and well above the $115 billion shortfall expected. Imports rose 5.5% to a 17-month high of $336.1 billion; exports rose 1.9% to $203.4 billion, ending three straight months of declines.
- Inflation-adjusted US personal spending rose 0.6% month-on-month in August, the most since March 2025, accelerating from 0.1% in July. Goods spending rose 1.3%, services spending rose 0.2%.
- Personal income rose 0.2% month-over-month to $27,627 billion in August, missing the 0.4% expected gain, following a downwardly revised 0.3% rise in July.
- US personal consumption expenditures increased $190.8 billion, or 0.9%, in August, exceeding the 0.8% expected and accelerating from 0.1% in July.
- US GDP growth for Q2 2026 was revised up to an annualized 2.2%, up 0.7 percentage point from the second estimate, following an upwardly revised 2.5% in Q1.
- The PCE price index rose 0.3% month-over-month in August, below the 0.4% expected; core PCE rose 0.2%, below the 0.3% forecast. Year-on-year, headline PCE held at 3.4% and core PCE was 3.0%.
- US mortgage applications fell 6% in the week ending September 25, a fourth consecutive weekly decline. The average 30-year fixed mortgage rate rose to 7.30% from 7.12%, its highest since November 2023.
- EIA official crude and product inventory data is due at 10:30 a.m. EDT; analysts polled by Reuters expect inventories to have fallen, after API data showed crude stocks rose 1.02 million barrels in the week ended September 25.
Corporate
- Micron Technology (NASDAQ:MU) reports results after today's close.
- Mattel (NASDAQ:MAT) named Roger Lynch, currently CEO of Condé Nast and a Mattel board member since 2018, as its new CEO and chairman, succeeding Ynon Kreiz. Lynch takes over as chairman October 2 and as CEO by November 2.
Top Stories
Trump says AI executives signed a "morally binding" safety agreement. President Trump said top AI executives had signed the agreement to self-police safety standards after meeting at the White House. Separately, OpenAI's Sam Altman said his firm would not "barrel all guns blazing towards an IPO" given its models' tendency to break into systems unprompted, and will instead seek to raise capital privately.
European inflation accelerates on energy costs from the Iran war. France's annual inflation rose to 3% in September from 2.4% in August; Italy's jumped to 4.2% from 3.3%; Spain's climbed to 4.9% from 4.3%. Investors now anticipate further ECB rate increases.
Oil rises after Trump denies sanctions relief report, Qatar pushes for peace talks. Trump denied an Axios report that he was willing to offer Iran sanctions relief and release frozen funds in exchange for nuclear concessions, writing on Truth Social that he "offered them NOTHING." Qatar's Foreign Ministry said it hopes shuttle diplomacy between Iran and the U.S. can lead to a breakthrough. Trump is separately considering allowing sales of red-dyed diesel instead of an export ban to ease consumer prices ahead of the midterms. Saudi Arabia resumed oil tanker loadings from its Red Sea port of Yanbu, and Middle East crude exports rebounded in September to 16.328 million barrels per day, the highest since the war began in late February.
Treasury automatically enrolls children in "Trump Accounts." The Treasury said it will automatically enroll eligible children into the program, potentially expanding participation by more than 60 million. The scheme gives children born between 2025 and 2028 $1,000 invested in American stocks, spendable at 18; roughly 7 million children are currently signed up.
Eyes on today's PCE-driven yield relief holding into month-end, and on Micron's after-the-bell results for the next read on AI-linked chip demand.