The Wall Street Wrap: November 4, 2026
US stocks surged on Wednesday as Democrats swept Congress and the Dow jumped 3.03% for its best day since April 2025, while crude oil fell 7.93% on hopes for an end to the Iran war and energy fell 4.77%. AI-infrastructure shares such as Datadog, Vistra, and CoreWeave sank on data-center regulation fears, and CVS fell 12.5% on plans to split in two. After the close, AppLovin jumped and Snap, Expedia, and Qualcomm fell.
Stocks surge as Democrats sweep Congress and the Dow posts its best day in more than a year, while oil plunges 8% on hopes for an end to the Iran war and AI infrastructure shares sell off
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
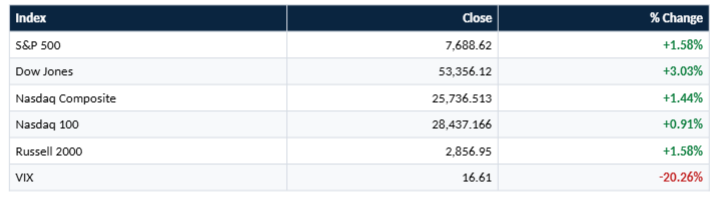
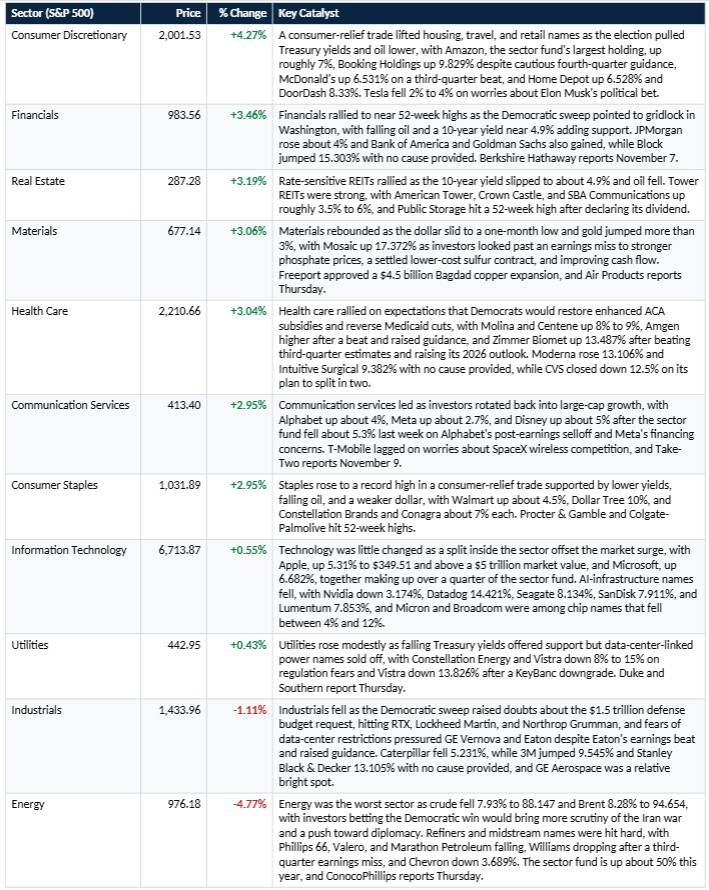
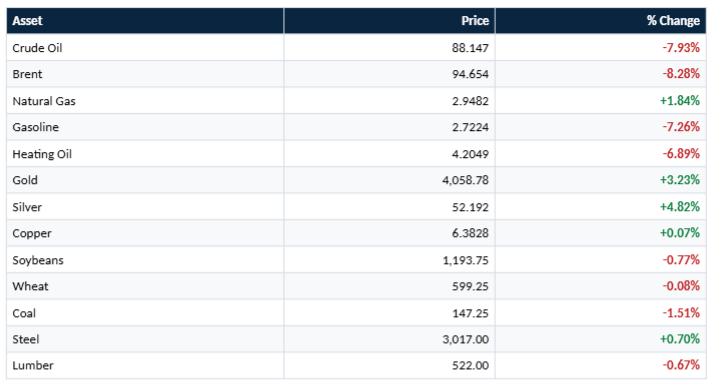
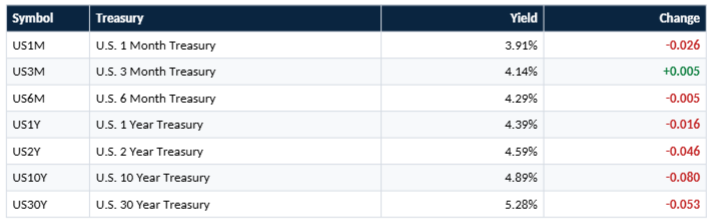
US stocks surged on Wednesday as Democratic wins in both chambers of Congress and President Donald Trump's acceptance of the results removed political uncertainty, with a plunge in oil prices adding to the rally while AI-infrastructure shares fell on fears of tighter data-center regulation. The Dow Jones Industrial Average jumped 3.03% to 53,356.12, its best day since April 9, 2025, and the S&P 500 rose 1.58% to 7,688.62. The Nasdaq Composite gained 1.44% to 25,736.513, the Nasdaq 100 rose 0.91% to 28,437.166, and the Russell 2000 gained 1.58% to 2,856.95, while the VIX fell 20.26% to 16.61. Nine of the 11 S&P 500 sectors rose, led by consumer discretionary at 4.27%, financials at 3.46%, and real estate at 3.19%, while energy fell 4.77% and industrials 1.11%. Mosaic rose 17.372% and Block 15.303%, while Fidelity National Information Services fell 23.673% and Trimble 17.314%. The 10-year Treasury yield eased to 4.89%, crude oil fell 7.93% to 88.147, and gold rose 3.23% to 4,058.78.
ANALYTICAL VIEW
Investors treated a divided Washington as good news. Democrats won the House and the Senate and took the Texas governorship, Trump told a newspaper he was "absolutely willing" to accept the results, and a strategist said gridlock has historically been good for the market. Stocks tied to the domestic economy led, with Home Depot up 6.528%, McDonald's 6.531%, 3M 9.545%, and Booking Holdings 9.829%, and the financial sector fund closed up 3.45% near its 52-week high. Crude fell 7.93% to 88.147 and Brent 8.28% to 94.654 after Vice President JD Vance blamed the Iran war for the Republican losses, dragging energy down 4.77%, and Treasury yields and the dollar fell, with the 10-year yield at 4.89%. Gold rose 3.23% to 4,058.78 and silver 4.82% to 52.192.
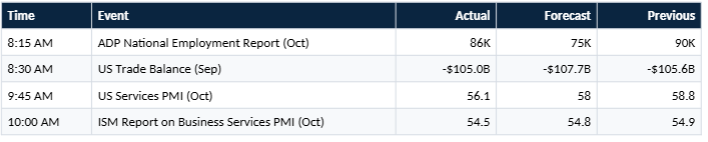
The AI trade split in two. Cash-rich heavyweights rose, with Microsoft up 6.682%, Apple up 5.31% to a record on a market value above $5 trillion, and Amazon up about 7%, because slower data-center construction could ease their spending demands. Shares of companies that depend on the buildout fell instead, with Datadog down 14.421%, Vistra 13.826%, CoreWeave 9.9%, Seagate 8.134%, SanDisk 7.911%, and Lumentum 7.853%, while Nvidia fell 3.174% and the Philadelphia semiconductor index hit a six-month low. Defense stocks also fell on doubts about Trump's $1.5 trillion budget request, and Caterpillar fell 5.231% and Chevron 3.689%. Data were mixed, as the trade deficit narrowed to $105.0 billion against $107.7 billion expected and private payrolls rose 86,000 against 75,000, while the ISM services index slowed to 54.5 against 54.8 expected.
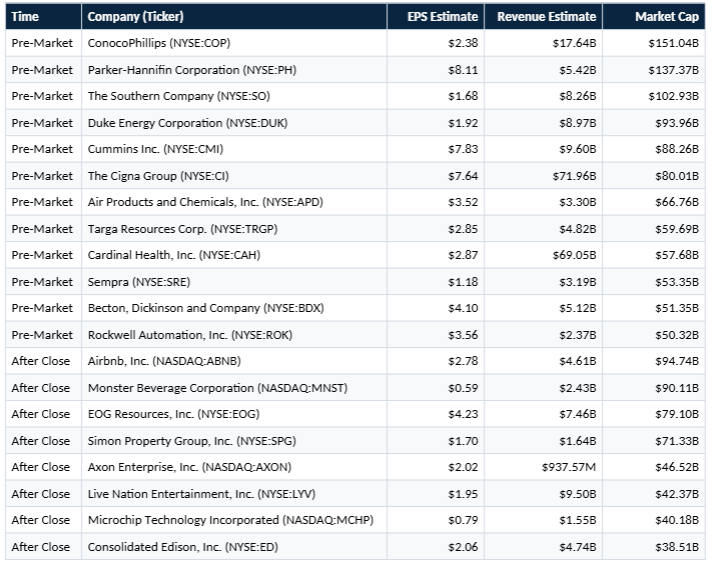
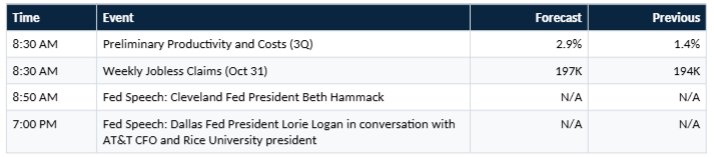
What could change the picture: Whether oil's slide proves overdone if US-Iran diplomacy stalls, whether AI-infrastructure shares stabilize as investors weigh the risk of data-center regulation ahead of Nvidia's November 17 earnings, and whether Thursday's results from ConocoPhillips, Airbnb, Cigna, and Monster Beverage and weekly jobless claims keep the rally going after the Dow's best day in more than a year.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- The Mosaic Company (NYSE:MOS): +17.372%
- Block, Inc. (NYSE:XYZ): +15.303%
- Zimmer Biomet Holdings, Inc. (NYSE:ZBH): +13.487%
- Moderna, Inc. (NASDAQ:MRNA): +13.106%
- Stanley Black & Decker, Inc. (NYSE:SWK): +13.105%
Top 5 Decliners:
- Fidelity National Information Services, Inc. (NYSE:FIS): -23.673%
- Trimble Inc. (NASDAQ:TRMB): -17.314%
- Comfort Systems USA, Inc. (NYSE:FIX): -15.082%
- Datadog, Inc. (NASDAQ:DDOG): -14.421%
- Vistra Corp. (NYSE:VST): -13.826%
Note: Mosaic rose after its third-quarter report as investors focused on stronger phosphate prices and cash flow over an earnings miss, Zimmer Biomet beat third-quarter estimates and raised its 2026 guidance, FIS fell after cutting its 2026 outlook, warning of declining 2027 earnings, and announcing its chief financial officer's departure, Trimble fell after cutting its full-year recurring revenue growth outlook to roughly 10% from 12% to 14%, and Vistra fell on fears of data-center regulation.
AFTER-HOURS MOVERS
Gainers:
- ADMA Biologics, Inc. (NASDAQ:ADMA), +25.81% after hours: Shares rose to $13.18 after third-quarter adjusted earnings of $0.23 a share beat the $0.20 consensus and revenue of $141.1 million topped the $138.2 million expected, up about 5% from a year earlier. The company indicated 2026 revenue of more than $530 million, a bit below the $535.4 million estimate. The stock had closed 5.67% lower at $10.48.
- Lyntris Inc. (NYSE:LYNX), +24.17% after hours: Shares rose to $11.66 after third-quarter revenue of $194.4 million, up 90% from a year earlier, far exceeded the $136.9 million estimate, with adjusted earnings of $0.15 a share against $0.08 expected. Backlog reached just over $1 billion, though the formal fiscal 2026 outlook had not yet been given. The stock had closed 19.81% lower at $9.39, a new low, as defense stocks fell on doubts about the Pentagon budget.
- AppLovin Corporation (NASDAQ:APP), +18.90% after hours: Shares rose to $323.11 after third-quarter revenue of about $2.19 billion, up 55%, topped the roughly $2.08 billion expected, with earnings of $4.30 a share against about $4.03 to $4.07. Fourth-quarter revenue guidance of $2.37 billion to $2.40 billion beat the roughly $2.25 billion consensus, and the board added $3.2 billion to buybacks, leaving $3.6 billion authorized. The stock had closed 10.69% higher at $271.75.
- Revolution Medicines, Inc. (NASDAQ:RVMD), +10.27% after hours: Shares rose to $220.20 after a third-quarter loss of $1.90 a share came in narrower than the $2.35 to $2.42 loss expected and revenue of about $197.6 million far exceeded the roughly $23 million to $27 million expected, though the composition of that revenue was not explained. It was the first full quarter after the August FDA approval of Rasonque for metastatic pancreatic cancer. The stock had closed 2.82% higher at $199.70.
- Coherent, Inc. (NYSE:COHR), +8.16% after hours: Shares rose to $211.00 after fiscal first-quarter revenue of a record $2.37 billion topped the $2.3 billion estimate, with adjusted earnings of $2.09 a share against $2.00 expected. Second-quarter guidance of $2.55 billion to $2.75 billion in revenue and $2.28 to $2.48 in earnings was slightly above the roughly $2.54 billion and $2.21 consensus. The stock had closed 5.98% lower at $195.09.
- Chime Financial, Inc. (NASDAQ:CHYM), +6.23% after hours: Shares rose to $31.73 after the company raised its 2026 revenue growth forecast to 28% from an expected 26.6% and guided fourth-quarter revenue to $757 million to $767 million, above the $745.6 million estimate. Third-quarter revenue of $718 million rose 32%, and active members grew 20% to 10.9 million. The stock had closed 5.92% higher at $29.87.
- e.l.f. Beauty, Inc. (NYSE:ELF), +2.53% after hours: Shares rose to $116.50 after fiscal second-quarter adjusted earnings of $1.21 a share beat the $0.62 estimate and revenue of $520.8 million, up 51%, topped the $473.5 million expected. Management raised its fiscal 2027 net sales growth outlook to 22% to 24% from 18% to 20% and its adjusted earnings guidance to $3.82 to $3.86 from $3.50 to $3.55. The stock had closed 1.91% higher at $113.63.
Decliners:
- LegalZoom.com, Inc. (NASDAQ:LZ), -15.22% after hours: Shares fell to $5.85 after third-quarter adjusted earnings of $0.19 a share missed the $0.21 estimate, even though revenue of $195.1 million, up 3%, topped the $193.8 million expected. The company lowered its adjusted EBITDA guidance to $180 million to $185 million, guided fourth-quarter revenue to $190 million to $196 million, and said transaction revenue is falling on weaker Google traffic. The stock had closed 3.14% higher at $6.90.
- Snap Inc. (NYSE:SNAP), -9.29% after hours: Shares fell to $5.37 after third-quarter revenue of $1.72 billion, up 14%, narrowly missed the $1.73 billion estimate and daily active users of 495 million trailed the 499 million expected, though adjusted EBITDA of $383 million beat the $337 million estimate. Fourth-quarter revenue guidance of $1.95 billion to $1.99 billion was in line, and the company said monthly active users will become its primary audience metric from the first quarter of 2027. The stock had closed 5.90% higher at $5.92.
- Expedia Group, Inc. (NASDAQ:EXPE), -7.24% after hours: Shares fell to $293.00 after fourth-quarter revenue guidance of $3.69 billion to $3.75 billion had a midpoint just below the $3.74 billion estimate, overshadowing third-quarter revenue of $4.94 billion against $4.74 billion expected and adjusted earnings of $9.39 a share against $8.89. The company raised its 2026 revenue outlook to $16.37 billion to $16.43 billion and its gross bookings outlook to $131.4 billion to $131.9 billion. The stock had closed 10.54% higher at $315.88.
- QUALCOMM Incorporated (NASDAQ:QCOM), -6.85% after hours: Shares fell to $161.32 after fiscal fourth-quarter adjusted earnings of $2.17 a share edged past the $2.16 estimate and revenue of $10.32 billion topped the $10.11 billion expected, but first-quarter earnings guidance of $2.15 to $2.35 had a midpoint just below the $2.27 consensus. Handset chip revenue fell 26% to $5.14 billion, while data-center revenue was about $650 million. The stock had closed 5.33% higher at $173.19.
- Arm Holdings plc (NASDAQ:ARM), -3.13% after hours: Shares fell to $185.80 even though fiscal second-quarter adjusted earnings of $0.52 a share beat the $0.47 to $0.48 expected and revenue of $1.443 billion, up 27%, topped the $1.376 billion estimate. The stock had closed 5.28% lower at $191.80, and options had priced in a move of roughly 12% to 13%.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Democrats sweep Congress and the Dow posts its best day in more than a year. Democrats won majorities in the House and the Senate and flipped key governorships including Texas, where Gina Hinojosa ousted Greg Abbott, giving the party a check on Trump's tariffs and the Iran war. The Dow rose 1,569.40 points, or 3.03%, to 53,356.12, moving back above 53,000 for the first time since September 8, while the S&P 500 gained 1.58% and the Nasdaq Composite 1.44%. Trump told The New York Times he was "absolutely willing" to accept the results and told The Wall Street Journal he would work with Democrats, and a market strategist said the rebound was "in part due to the president's initial tone and reaction to the results." Walmart rose about 3% and Bank of America about 4% as investors looked for stocks outside technology.
Crude oil falls about 8% to a one-month low as the election raises hopes for an end to the Iran war. West Texas Intermediate fell 7.93% to 88.147 a barrel and Brent 8.28% to 94.654, extending losses to a third straight session and leaving futures down more than 14% this week, after Vance wrote that "the reason we lost is the war." Trump told the Financial Times he has no immediate plans to strike Iran, diplomatic efforts led by Qatar and Pakistan continue, and an oil analyst said Democrats may try to restrict funding for the war. Renewed Gulf exports also pushed Middle Eastern supply above near-term demand for the first time since July, though US crude inventories fell by 865,000 barrels last week, and an energy trader at a bank warned that the selloff "could be getting a bit overdone."
The AI trade splits as data-center shares fall on regulation fears. Cash-rich AI heavyweights rose, with Microsoft up 6.682%, Amazon about 7%, and Alphabet about 4%, as investors bet a slower data-center buildout would ease their cash demands, while operators and suppliers fell after Democrats made gains in key data-center states including Texas and Georgia. Hut 8 fell 23%, IREN 11%, Core Scientific 10%, and Applied Digital 6.7%, CoreWeave fell 9.9% and Datadog 14.421%, Nvidia fell 3.174%, and the Philadelphia semiconductor index dropped 3.1% to a six-month low. Apple rose 5.31% to a record high above a $5 trillion market value, with one analyst calling it an anti-AI play, while SpaceX fell 3.9% and Tesla 3.3% after Musk spent nearly half a billion dollars backing Republican candidates. Defense stocks also fell as Trump's $1.5 trillion budget request faces a tougher road in Congress.
CVS falls 12.5% after announcing plans to split into two public companies. The company said it will separate its roughly 9,000 retail pharmacies, mail-order pharmacy, and MinuteClinic from Aetna, Caremark, specialty pharmacy, Oak Street Health, and Signify Health by the first half of 2028, with shareholders owning both companies. The shares closed down at $79.96, cutting nearly $15 billion in market value, even though third-quarter adjusted earnings of $2.09 a share easily beat the $1.65 expected, the company raised its 2026 forecast to at least $8.20, and it guided 2027 earnings to at least $8.65 against $8.53 expected. Analysts said the split came as a surprise, is seen as a defensive move against regulation of pharmacy benefit managers, and came with little financial detail, and the chief financial officer cited challenges next year from a federal drug discount program and a "less robust selling season."
The US trade deficit narrows as imports hit a record, and services growth cools. The September trade deficit narrowed 0.7% to $105.0 billion against $107.7 billion expected, with imports rising 1.2% to a record $426.6 billion on AI-related purchases of computers and accessories, and economists estimated computers, peripherals, and semiconductors made up roughly 61% of the deficit. The ISM services index slipped to 54.5 from 54.9, below the 54.8 expected, with new orders at 55.9 from 59.8 and supplier deliveries slowing to 56.7, and the ISM's chair said more pricing pressure is on the way if oil and tariff costs are not mitigated. ADP reported 86,000 private jobs added in October against 75,000 expected, and S&P Global's services PMI came in at 56.1 against 58.0 expected.
Also today: Helen of Troy rose 25.39% to $37.04 after confirming its board rejected Empower Brands' $37-a-share cash takeover proposal, which implies an enterprise value of about $1.6 billion; Apple has cut daily AI spending allowances for some engineers to $200 from $300 and is considering lower limits, Bloomberg reported; HP named former GSK chief Emma Walmsley as chief executive from January 4, and its shares rose 6.6% intraday; Goldman Sachs and Apollo Global Management are in talks with investors to sell portions of a roughly $40 billion financing deal for SpaceX's AI chips, Bloomberg reported; prediction markets accurately called most of Tuesday's races and often projected results before news outlets, with Hinojosa's odds on Polymarket jumping from 39% to 73% within five minutes of polls closing; bitcoin rebounded to about $80,000 after briefly touching $75,000, though Bitfinex said the recovery lacks new spot buyers.
TOP STORIES: GLOBAL
Euro zone inflation hits a three-year high of 4% as energy costs surge. The flash estimate for October rose from 3.8% in September and matched forecasts, with energy inflation climbing to 20.8% from 18.9%, and it was the first reading at or above 4% since September 2023. Lithuania recorded the highest rate at 6.1% and Malta the lowest at 2.3%, and all 21 euro zone economies were above the European Central Bank's 2% target. The bank held its rate at 2.5% last month after a September hike, markets now price a more than 72% chance of a December increase, and a risk analyst said turmoil in the French bond market is constraining policy.
Iran's leaders respond to the US election as Washington weighs next steps. Parliament Speaker Mohammad Bagher Ghalibaf said Americans "said NO TO WAR," and a post on Supreme Leader Ayatollah Mojtaba Khamenei's account said the process of the US's collapse has accelerated and that concessions to Washington would not bring an end to hostility. Reports from The Wall Street Journal and The New York Times indicate the US is preparing for possible renewed military action after the election, while Democrats could try to pass a War Powers Resolution directing Trump to end the conflict absent congressional authorization. Trump told the Journal that "Iran was a piece of it" in the Republican losses but that he would "have done it again."
Canada's TSX jumps 2.3% as a Democratic Congress raises hopes of easing trade tensions. The S&P/TSX Composite Index closed at 36,341, with auto exporters rising, Magna International up 3.9% and BRP up 7.7%, and miners rallying with gold, with Agnico Eagle up 9.4%, Barrick up 8%, and Wheaton Precious Metals up 11.7%. Canada's trade surplus widened to C$5.35 billion in September as higher energy and gold exports to the US offset tariffs, and Canada and China extended a deal reducing Beijing's agricultural tariffs through the end of 2028. Lower oil prices also supported banks, with RBC up 2.5%, TD Bank and CIBC up 2.4%, and BMO up 2.9%.
The European Union commits 525 million euros to chip startups. EU tech chief Henna Virkkunen said the European Commission and member states will provide 440 million euros in grants to help startups with the cost of developing chips for commercial use, while another 85 million euros will fund a European Chips Design Platform giving startups access to design tools, intellectual property blocks, and manufacturing capacity. European chip design companies account for less than 1% of global revenue in that segment, according to the Commission.
MANAGEMENT & FED SPEAK
David Joyner, Chief Executive Officer, CVS Health, on the split:
"We're doing it out of a position of strength."
Ariane Gorin, Chief Executive Officer, Expedia Group, on travel demand:
The US consumer was "strong both in domestic travel and in outbound to Europe and Asia."
Cristiano Amon, Chief Executive Officer, QUALCOMM, on supply:
"We don't have a demand issue; it's a supply issue."
JD Vance, Vice President of the United States, on the election:
"The reason we lost is the war."
Donald Trump, President of the United States, on the election results:
"Iran was a piece of it," but "I would have done it again."
CORPORATE ACTIONS & EARNINGS CALENDAR
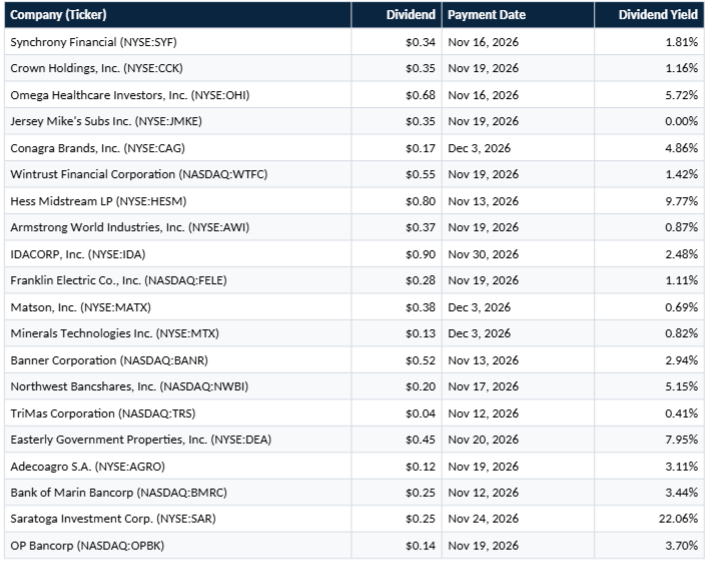
Top Ex-Dividend Companies for Thursday, November 5:
Upcoming Earnings (Thursday, November 5):
Economic Calendar (Wednesday, November 4):
Upcoming Economic Calendar (Thursday, November 5):
That's the wrap for today! Attention turns to Thursday's results from ConocoPhillips, Airbnb, Cigna, and Monster Beverage, weekly jobless claims, and whether oil's slide and the split in AI-related shares hold after the Democratic sweep.
Related post