ASX Pre-Market: Thursday, 24 September 2026
ASX SPI 200 futures point to a sharply weaker open, down 104 points, or 1.18%, to 8,706, after Wall Street fell overnight as a surge in Treasury yields to their highest level since 2007 rattled markets on hot US economic data and hawkish Fed commentary.
Welcome to your morning briefing on overnight Wall Street action and what's set to move the ASX 200 at the open.
ASX Futures
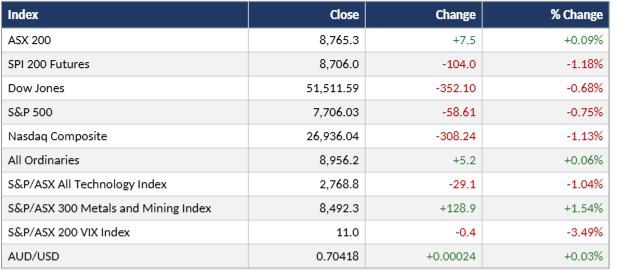
SPI 200 futures were down 104 points, or 1.18%, to 8,706, pointing to a sharply weaker open after Wednesday's local session finished essentially flat. The reversal follows Wednesday's close, where the ASX 200 edged up just 7.5 points, or 0.09%, to 8,765.3, and comes as Wall Street fell overnight after a surge in Treasury yields to their highest level since 2007 unsettled investors already weighing the prospect of further Federal Reserve tightening.
Overnight Leads + This Morning
Wednesday's local session was directionless, with the ASX 200 up just 7.5 points, or 0.09%, to 8,765.3, as gains in miners offset broad weakness elsewhere, with eight of eleven sectors closing red. Materials led, up 1.6%, as copper's rally continued, up 8% over six sessions despite easing 1.2% intraday to $6.83/lb; BHP rose 1.4% to $62.07 and Rio Tinto added 0.8% to $167.61. Gold miners also advanced, with the All Ords Gold Index up 2.5% and Northern Star, Evolution Mining and Newmont all higher. Real Estate extended a three-day win streak, up 1.3%, as the Australian 10-year yield slipped to a two-week low of 5.25%. Technology gave back much of Tuesday's rally, falling 0.6%, with Xero tumbling 4.7% to $58.20, its lowest since May 2019 and down 48% year to date, while Financials slipped 0.6% as CBA fell 0.8% to levels last seen in February. Energy was among the weakest sectors as Woodside and Santos both fell more than 1.5% on lower crude, while IDP Education plunged 13.2% after rejecting two unsolicited Blackstone approaches, the latest sweetened to $2.50 a share. Australia's flash September Composite PMI fell to 50.8 from 52.7, its weakest reading of the quarter, with manufacturing swinging to its first contraction since March and private-sector employment falling for the first time in four months.
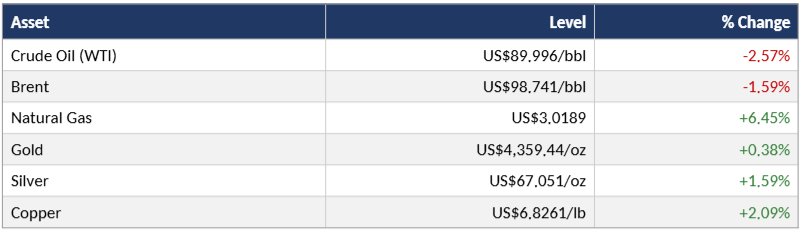
Overnight, Wall Street fell as Treasury yields surged on stronger-than-expected US data, hawkish Fed commentary and a weak Treasury auction. The S&P 500 dropped 0.75% to 7,706.03, the Dow fell 352.10 points, or 0.68%, to 51,511.59, and the Nasdaq Composite shed 1.13% to 26,936.04. The US ten-year Treasury yield settled at 5.110%, its highest since July 2007 and its biggest one-day jump in nearly eighteen months, after S&P Global's flash PMIs showed manufacturing and services expanding at their fastest pace in more than five years, with input costs rising at the steepest rate in four years. A weak five-year Treasury auction added further pressure, with Fed Governor Michael Barr telling a housing conference that "further policy adjustments are likely to be needed" to bring inflation to target. Markets pushed the probability of an October rate hike to 73%, according to CME's FedWatch tool, up sharply from 8.8% a month ago. Oil rose for the first time in six sessions, with Brent gaining 3.9% to $103.08 a barrel and WTI up 1.8% to $92.16, after Iranian President Masoud Pezeshkian told the UN General Assembly that Iran "cannot be made to surrender."
Close Levels
Analytical View
Wednesday's local session showed a market pausing rather than reversing, with a flat headline masking real dispersion beneath it. Materials and gold continued to work off their late-August pullback, with copper's rally over the past six sessions giving BHP and the broader mining complex genuine momentum, while Real Estate's bounce reflected the first meaningful pullback in the Australian 10-year yield in weeks. But Technology remains, in effect, a momentum graveyard: the sector has fallen around 17% since 25 August even as comparable global software benchmarks have gained, with Xero and WiseTech both trading well below their year-to-date lows from June and July. That divergence, a domestic tech sector being sold regardless of what offshore peers do, is now a persistent feature of the market rather than a one-off session.
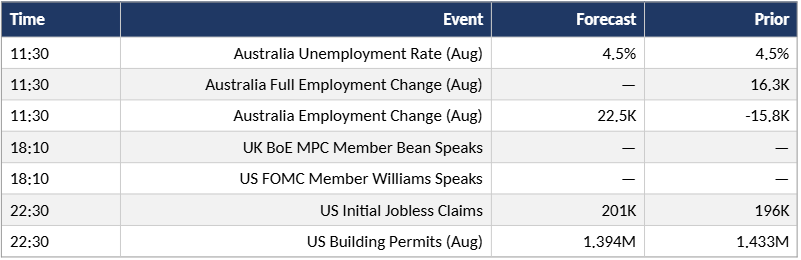
Overnight, Wall Street's reversal was driven entirely by the bond market. The S&P Global flash PMI data was unambiguously strong, the best reading in more than five years, but strength of that kind now reads as a hawkish signal rather than good news, since it raises the odds the Fed has more tightening still to do. The jump in the probability of an October hike to 73%, from under 9% a month ago, reflects how quickly that repricing has happened. For the ASX 200, a domestic market that had already spent Wednesday digesting a soft flash PMI print of its own now faces a genuinely more hawkish global backdrop overnight, with Thursday's local labour force data the next test of whether the RBA's own path higher accelerates further.
What could change the picture: Australia's August employment data, due Thursday, is the next domestic test ahead of the RBA's rate decision on 28-29 September, alongside a raft of flash PMI releases from Europe, the UK and the US that could further move the global rates narrative.
Commodities
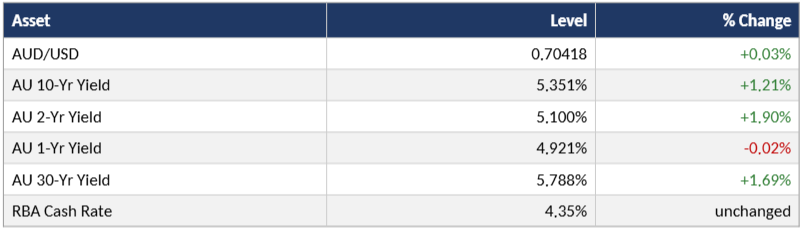
Rates
Home & Away
Names with a foot in both camps today, ASX movers with direct overseas read-through, and overseas news with a local echo.
US Treasury yields surging to 2007 highs is a direct headwind for the ASX's own rate-sensitive names. The US ten-year settling at 5.110% overnight, its highest since July 2007, has already pushed the Australian 10-year yield up 1.21% to 5.351% in early trade. That is a negative read-through for Real Estate names such as Goodman Group (ASX:GMG), Stockland (ASX:SGP) and Lifestyle Communities (ASX:LIC), which had only just begun to bounce on Wednesday's brief pullback in local yields, and for Technology names including Xero (ASX:XRO) and WiseTech Global (ASX:WTC), which remain among the market's most persistent underperformers this year.
Copper's rally gives BHP and Rio Tinto a genuine tailwind, even as Wednesday's session showed some fatigue. Copper rose a further 2.09% to $6.8261/lb overnight, extending a rally that has taken the metal up 8% over six sessions, though it had eased 1.2% intraday during Wednesday's Asian trade. BHP (ASX:BHP) rose 1.4% to $62.07 and Rio Tinto (ASX:RIO) added 0.8% to $167.61 on Wednesday, and the overnight gain should offer further support heading into Thursday, subject to the same US dollar strength that has recently weighed on metals priced in the currency.
Oil's rebound is a mixed signal for the ASX energy complex. Brent rose 3.9% to $103.08 and WTI gained 1.8% to $92.16 overnight after Iran's president struck a defiant tone at the UN, reversing a five-session decline. That is a positive read-through for producers Woodside Energy (ASX:WDS) and Santos (ASX:STO), both of which fell more than 1.5% on Wednesday as crude retreated, while the same move works against refiners Ampol (ASX:ALD) and Viva Energy (ASX:VEA), which had benefited from cheaper input costs.
Local Catalysts
Westpac overhauls SME banker pay as APRA scrutiny intensifies. Westpac (ASX:WBC) will change how pay and bonuses are structured for small business bankers from 1 October, after an internal audit found employees had breached loan authority limits and failed to properly assess fraud risks. The Australian Prudential Regulation Authority interviewed more than 20 Westpac bankers in May and issued the bank a confidential review demanding improvements, raising internal concern the regulator could impose a fresh capital penalty. National general manager Anthony Mathews outlined six changes to take effect from October 1, including a new compliance checklist that could reduce annual bonuses for bankers who breach risk parameters.
Goodman Group data centre plan hits fierce opposition at Senate inquiry. A Senate inquiry hearing in Sydney's Lane Cove heard fiery objections to Goodman Group's (ASX:GMG) proposed $1.2 billion data centre on Mars Road, which the company conceded would sit within 16 metres of homes and could reach 38 metres in height. Liberal Senator Sarah Henderson called the plan "completely unacceptable" and pressed Goodman's general manager of developments, Ben McGilp, to withdraw it; McGilp said the company would consider community feedback and decide whether to proceed by year end. Plans include storing 1 million litres of diesel and 198,000 kilograms of lithium batteries on site.
Tuas shares slump 17% despite FY26 results beating estimates. Tuas (ASX:TUA) reported revenue up 24% and underlying profit up more than fourfold for the year, ahead of Morgan Stanley's forecasts, but shares fell as much as 19% intraday after chairman David Teoh offered no update on an ongoing Singapore regulatory investigation into unauthorised spectrum usage that sank the company's proposed acquisition of M1 Limited. The company said it remains "fully cooperative" with Singapore's Infocomm Media Development Authority while awaiting a formal decision.
RBA says ASX still falling short on governance despite CHESS overhaul progress. The Reserve Bank's latest annual assessment found the ASX (ASX:ASX) continues to fall short of regulatory expectations in several areas, despite progress during the year. RBA assistant governor Brad Jones said the exchange operator faces "a period of substantial organisational change" following its troubled CHESS replacement project, for which it paid a $20.5 million penalty in June after admitting it misled the market. New ASX chief executive Anthony Attia this week unveiled a leadership shake-up including new CFO and COO appointments.
NYSE-listed Digital Realty circles Stack Infrastructure's $28 billion APAC auction. Digital Realty, a US$69.9 billion data centre operator, has been quietly involved in the auction for Blue Owl Capital's Stack Infrastructure Asia Pacific business, which includes data centre assets in Australia, Japan and Malaysia. The portfolio has been shopped with US$1.3 billion in contracted earnings and valuation estimates ranging from US$20 billion to US$30 billion including debt, with the AI Infrastructure Partnership and IFM Investors consortium currently seen as the lead bidder.
Global News
Trump and Xi meet in Washington as auto industry warns on Chinese carmakers. President Trump is set to host Chinese President Xi Jinping for a state visit beginning Thursday, with the US auto industry and more than two dozen Democratic lawmakers urging Trump to keep restrictions on Chinese automakers in place. Reports suggest BYD founder Wang Chuanfu and CATL founder Robin Zeng could be among the Chinese delegation, alongside US executives including GM's Mary Barra and Tesla's Elon Musk.
Trump weighs diesel export ban as industry warns of backfire. President Trump has indicated support for a temporary ban on US diesel exports to bring down domestic fuel prices, though Energy Secretary Chris Wright said the administration was considering restrictions rather than an outright ban. The American Petroleum Institute warned a ban would "compound the problem" and risk retaliation from trade partners, with diesel prices already at record highs of $6.52 a gallon nationally.
Zelenskyy calls for trilateral summit as Ukraine offers energy ceasefire. Ukrainian President Volodymyr Zelenskyy urged Trump to organise a trilateral meeting with Russian President Vladimir Putin, saying Ukraine is ready for an "energy ceasefire" if Russia stops striking its energy and water infrastructure. The Kremlin's Dmitry Peskov said a Putin-Zelenskyy meeting before expert-level talks would be premature.
OpenAI and Anthropic chiefs press UN for AI cooperation after Trump rebuffs "globalist scheme." OpenAI's Sam Altman and Anthropic's Dario Amodei addressed the UN Security Council, calling for international coordination on AI risks, a day after Trump told the UN General Assembly he would not "stifle growth" of the technology and criticised what he called a "globalist scheme" to control it. Amodei reiterated his call for the industry to "pace the frontier" of development.
McDonald's unveils $8.5 billion restaurant overhaul, shares fall 6%. McDonald's outlined plans to spend up to $8.5 billion through 2036 supporting franchisee restaurant upgrades, alongside a new advertising media network and an AI-powered restaurant operating system called ArchIQ, at its investor day. Shares fell 6% as CEO Chris Kempczinski said elevated inflation and flat customer traffic are likely to persist rather than ease.
Management & Fed / RBA Speak
Michael Barr, Governor, US Federal Reserve, on the case for further tightening:
Barr told a Chicago housing conference that "further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion," adding that price stability remains crucial to supporting durable economic growth.
Susan Collins, President, Federal Reserve Bank of Boston, on the inflation outlook:
Collins wrote that she now sees "an increased likelihood" that inflation will remain "notably" above the Fed's 2% target, explaining her support for last week's rate hike by noting that a somewhat more restrictive policy stance would help ensure inflation "durably returns to target."
Philip Lane, Executive Board Member, European Central Bank, on energy-driven inflation:
Lane told a Swiss newspaper that a "second wave of rising energy prices" is likely to keep eurozone inflation "higher for longer," saying the central bank expects "upward pressure on food, energy more broadly, including electricity, and goods in general" if the shock proves larger and more persistent this autumn.
Brad Jones, Assistant Governor, Reserve Bank of Australia, on the ASX's regulatory shortfalls:
Jones said the RBA's latest assessment "highlights that, despite progress during the year, ASX is still not meeting the RBA's expectations in several important areas," adding that the exchange operator's challenge is to deliver its transformation program "without compromising the safe and reliable operation of its critical infrastructure."
Corporate Actions & Earnings Calendar
Economic Calendar (Thursday, 24 September):
Ex-Dividend Today (Thursday, 24 September 2026):
That's the pre-market wrap for today. The ASX looks set for a sharply weaker open, with SPI 200 futures pointing to a 1.18% fall as surging US Treasury yields, now at their highest since 2007, unsettle markets ahead of Thursday's local employment data. That report, alongside the RBA's rate decision on 28-29 September, is the next test for a market already digesting a soft local flash PMI print and rising odds of further global central bank tightening.