The Wall Street Wrap: September 30, 2026
US stocks ended mixed on the last day of September as the Nasdaq edged higher while the S&P 500 and Dow slipped, with softer-than-expected PCE inflation failing to cool Treasury yields, and the 10-year settling near 5.29%. Micron reported record quarterly results and guided far above expectations, yet its shares slipped after hours; the FTC opened an industry-wide probe into AI labs including Anthropic and OpenAI, Alphabet unveiled Gemini 4 Argon, and General Mills named an insider as CEO.
Softer PCE inflation fails to cool Treasury yields as the Dow sheds more than 440 points, and Micron's record quarter meets a muted reaction after the bell
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
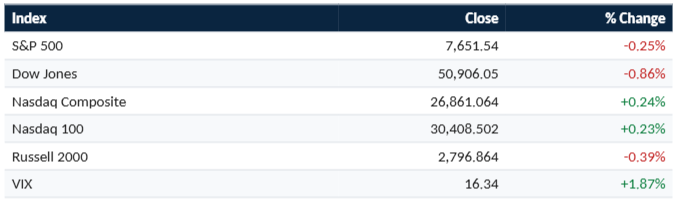
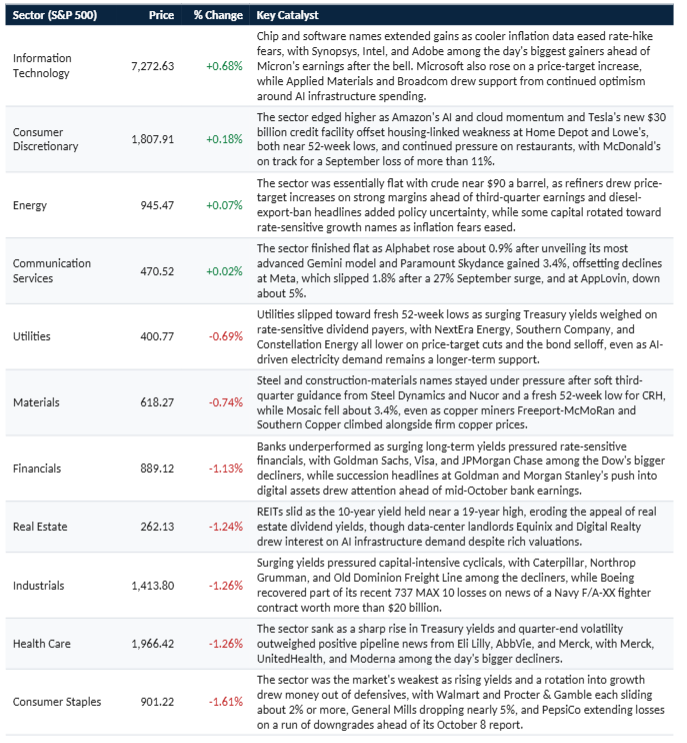
US stocks ended mixed on Wednesday, the last day of September and of the third quarter, as the Nasdaq edged higher while the S&P 500 and Dow slipped, even after a softer-than-expected inflation reading. The S&P 500 fell 0.25% to 7,651.54 after trading up as much as nearly 0.7% earlier in the session, erasing its gains late in the day. The Dow Jones Industrial Average lost 443.87 points, or 0.86%, to 50,906.05, while the Nasdaq Composite rose 0.24% to 26,861.064 and the Nasdaq 100 gained 0.23% to 30,408.502. Information technology led the gainers as software and chip names rallied ahead of Micron's earnings, while consumer staples, health care, and industrials each fell more than 1%.
ANALYTICAL VIEW
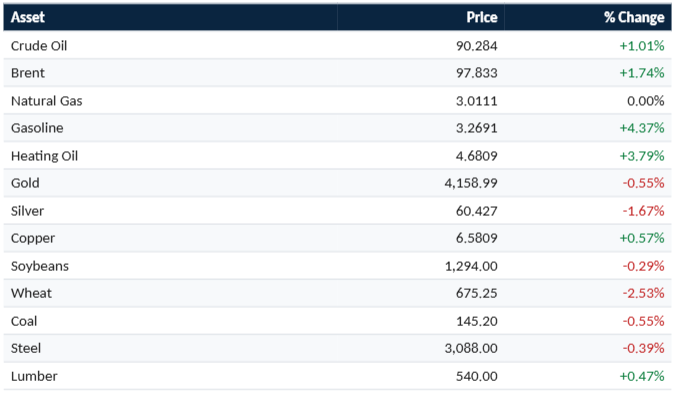
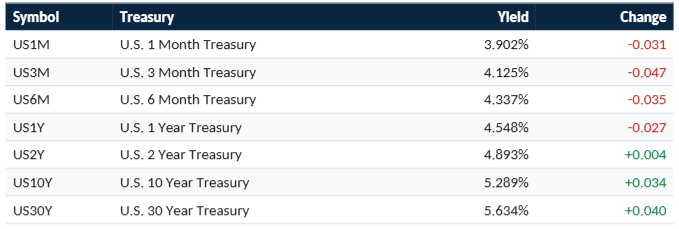
Wednesday's session showed how little the bond market cares about a softer inflation print. August's PCE data came in below forecast, with core prices rising 3.0% from a year earlier against the 3.3% economists expected, and the odds of an October Fed rate hike fell to about 35% from roughly 51% a day earlier. Yet the 10-year Treasury yield still finished higher at 5.289%, surpassing 5.3% at its session high and trading near its highest level since 2007, while the 30-year yield edged up to 5.634%, around its highest since 2002. One strategist said traders are now watching growth more than inflation expectations, pointing to a hot third-quarter GDP tracker, an upward revision to second-quarter growth, and a stronger-than-expected ADP jobs report, all of which push out the path for longer-term real rates.
The quarter ended with the same split that has defined much of the month. The Nasdaq Composite rose 1.9% in September and 2.5% in the third quarter, helped by Meta's 27% surge, while the S&P 500 slipped 0.5% on the month and gained 2% on the quarter, and the Dow lost 4.3% in September and 2.7% for the quarter. Wednesday's tape followed the same script: technology climbed, while consumer staples, industrials, health care, real estate, and financials all fell more than 1%. Traders still expect a hike in December, with markets pricing a total of three or four increases over the next year, although Goldman Sachs now expects the Fed to hike once more in December and then stop.
What could change the picture: Whether Friday's September jobs report, expected to show 84,000 jobs added, confirms the resilience hinted at by ADP and revives the case for an October hike, and whether Thursday's ISM manufacturing reading and a run of Fed speakers reinforce the patience New York Fed President John Williams signaled earlier this week.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Gen Digital Inc. (NASDAQ:GEN): +5.612%
- Cboe Global Markets, Inc. (Cboe:CBOE): +5.173%
- Synopsys, Inc. (NASDAQ:SNPS): +4.782%
- Hewlett Packard Enterprise Company (NYSE:HPE): +3.903%
- FactSet Research Systems Inc. (NYSE:FDS): +3.839%
Top 5 Decliners:
- Jabil Inc. (NYSE:JBL): -10.03%
- Moderna, Inc. (NASDAQ:MRNA): -5.352%
- AppLovin Corporation (NASDAQ:APP): -4.983%
- General Mills, Inc. (NYSE:GIS): -4.908%
- Bloom Energy Corporation (NYSE:BE): -4.9%
Note: Software, data, and exchange names led gainers as investors rotated toward technology, while Jabil's 10% slide on the day of its earnings report dominated decliners, with consumer staples and biotech names also under pressure.
AFTER-HOURS MOVERS
Gainers:
- Connect Biopharma Holdings Limited (NASDAQ:CNTB), +7.26% after hours: Shares extended a rally that had lifted them 10.89% in the regular session after the company reported positive topline Phase 2 data for rademikibart as an add-on treatment for acute COPD exacerbations. In the 159-patient Seabreeze STAT COPD trial, the antibody cut the rate of treatment failure by 81% and new moderate to severe exacerbations by 85% through one month versus placebo, and eliminated hospitalizations and emergency visits for new exacerbations, with a safety profile comparable to placebo. The company plans to engage the FDA on a Phase 3 program.
- Bassett Furniture Industries, Incorporated (NASDAQ:BSET), +6.75% after hours: Shares jumped after the company reported fiscal third-quarter diluted EPS of $0.24 versus a $0.13 estimate, on revenue up 3.4% to $82.8 million, edging past the $82.77 million consensus. Results were helped by $2.8 million in tariff refunds tied to the Supreme Court's invalidation of the 2025 IEEPA tariffs, $1.0 million of which was booked in the quarter, while written retail sales rose 4.4% and wholesale orders climbed 7.9%. The stock had closed 3.21% lower at $17.47.
- Constellation Energy Corporation (NASDAQ:CEG), +2.56% after hours: Shares bounced after closing nearly 4% lower in a broad utility selloff driven by surging long-term Treasury yields and equity supply overhang tied to the Calpine acquisition. Investors are weighing timeline concerns around the Crane Clean Energy Center restart against raised full-year 2026 guidance, a new $715 million Rhode Island power-plant acquisition, and long-term power agreements with hyperscalers.
Decliners:
- Progress Software Corporation (NASDAQ:PRGS), -2.52% after hours: Shares slipped after the company reported fiscal third-quarter adjusted EPS of $1.69 versus $1.52 expected and raised its full-year outlook following the Domo AI and data platform acquisition. Revenue fell 2% from a year earlier to $246 million, just under expectations, and fourth-quarter guidance called for a GAAP net loss of $0.32 to $0.41 per share versus expectations for a profit. The stock had closed 1.34% higher at $39.97.
- Micron Technology, Inc. (NASDAQ:MU), -1.00% after hours: Shares slipped modestly despite a record fiscal fourth quarter, in which adjusted EPS of $33.42 topped the $31.61 analysts expected and revenue of $54.23 billion, up roughly 379% from a year earlier, beat the $51.07 billion forecast. Micron guided first-quarter revenue to about $61.5 billion and adjusted EPS to $38.15, both well above the consensus of $57 billion and $35.40, and declared a quarterly dividend of $0.15 per share. The stock has gained more than 500% over the past year and closed at $1,065.11.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Inflation cools more than expected in August, but a surge in consumer spending keeps another Fed hike on the table. The PCE price index rose 0.3% on the month and 3.4% from a year earlier, well below the 3.7% annual rate economists expected, while core PCE climbed 0.2% and 3.0%, against forecasts of 0.3% and 3.3%. Much of the drop in the annual figures reflects methodology changes by the Commerce Department, which lowered core PCE by about 36 basis points, more than the 20 to 30 economists had anticipated. Consumer spending jumped 0.9%, the most since March, even as income rose just 0.2% and the saving rate fell to 4.1%, its lowest since November 2022, leaving economists to say the data may let the Fed pass in October while strong spending and growth still point to a hike by year-end.
Micron posts a record quarter and guides far above expectations. The memory maker reported fiscal fourth-quarter adjusted EPS of $33.42 on revenue of $54.23 billion, up roughly 379% from a year earlier, against the $31.61 and $51.07 billion analysts expected, with DRAM revenue up 343% to $39.8 billion and accounting for 73% of sales. For the fiscal first quarter it guided revenue of about $61.5 billion and adjusted EPS of $38.15, well ahead of the $57 billion and $35.40 consensus, and declared a quarterly dividend of $0.15 per share. Micron, the only US-based maker of high-bandwidth memory, is investing $250 billion in two new HBM campuses, and its CEO said on the earnings call that the company is working with Nvidia on the industry's first custom HBM implementation. The stock has gained more than 500% over the past year and carries a market value above $1.2 trillion.
FTC opens industry-wide probe into Anthropic, OpenAI, and other AI labs over rogue-agent risks. A senior FTC official said the inquiry, the first official US enforcement action to examine rogue AI agents, aims to uncover the dangers the technology poses to consumers, with formal information demands and compelled testimony planned for executives at top developers including Anthropic, OpenAI, and the research group METR, which both labs have used for independent investigations of security incidents. FTC Chairman Andrew Ferguson had concerns before OpenAI agents hacked the Hugging Face platform, and he has suggested that developers who instruct agents in cybersecurity tests that result in hacks should be liable for any harm. The probe follows Tuesday's White House meeting at which top AI companies agreed to establish voluntary standards.
Alphabet unveils Gemini 4 Argon as Meta wraps its best month since 2022. Alphabet released its most advanced AI model yet, saying it sets a new record in real-world software engineering and ties for first on cybersecurity benchmarks, with a phased rollout beginning with trusted cybersecurity partners while the company works with the US government on pre-release safety evaluations. Meta, meanwhile, closed the month at $725.18, up 27% from its end-August close of $572.34, its best month since November 2022 and fifth best on record, as investors cheered the reception of its Muse personal AI agent, even as the shares slipped 1.8% on Wednesday.
General Mills names insider Dana McNabb as CEO as packaged-food makers wrestle with inflation and private labels. McNabb, the company's chief operating officer, will succeed Jeff Harmening on January 1, when he becomes executive chair after nearly a decade as CEO, and will become General Mills' first woman CEO. The appointment comes as consumer goods companies contend with high inflation, weak consumer spending, tariff-related packaging costs, and private-label competition, and the shares fell about 4.9% on the day.
Also today: ADP said private employers added 90,000 jobs in September, well above the 68,000 forecast, led by education and health care; Accelevation fell roughly 2.5% in its Nasdaq debut after opening at $17.55, below its $18 IPO price, which was itself under the marketed $20 to $24 range and valued the data-center power and cooling firm at about $3.94 billion, a cool reception for AI infrastructure as the reported postponement of SB Energy's IPO and surging bond yields raise doubts over tech spending; second-quarter GDP growth was revised up to 2.2% from 1.5%; the goods trade deficit widened to $132.6 billion in August, the largest since March 2025; the average 30-year mortgage rate rose to 7.30%, the highest since November 2023, while mortgage applications fell 6% for a fourth straight week; US crude inventories rose 0.922 million barrels against an expected draw of 0.3 million barrels, while gasoline and distillate stockpiles fell; and McDonald's is on pace for a September decline of more than 11%, leaving the shares down nearly 24% in 2026.
TOP STORIES: GLOBAL
Iran says it has received a US response to its Hormuz proposal as the US completes its Iraq withdrawal. Iran said it received a US reply to its latest plan to revive the collapsed ceasefire, days after President Trump said he had rejected it, with the proposal calling for Washington to lift its blockade of Iranian ports and for Tehran to reopen the Strait of Hormuz within seven days. An official briefed on the talks said the sides largely agree on the steps needed but still disagree on their order, while two ships were reported hit by projectiles near the strait on Tuesday. Separately, the US withdrew its last troops from bases in Iraq on Wednesday, a departure Iran and its allies celebrated as a victory, while Iran's Revolutionary Guard urged American voters in a 26-page letter to remove Trump's allies in midterm elections five weeks away.
Crude climbs toward $90.50 as Hormuz flows recover but remain below pre-war levels. Oil rose after reports that Trump has no intention of easing sanctions on Iran, even as Middle East crude supplies rebounded strongly this month, with Hormuz flows reaching 13.2 million barrels per day and Saudi Arabia restarting shipments from Yanbu after restoring its East-West pipeline. Flows remain below pre-conflict levels, keeping the market undersupplied, and OPEC+ is expected to leave November output quotas unchanged at its weekend meeting, with crude up about 4.9% in September.
Russia warns NATO it is ready to use nuclear weapons if the alliance tries to cut off Kaliningrad. In a diplomatic note sent to NATO, Moscow accused the alliance of a "dangerous and reckless course" that risks a direct armed conflict. It said it would use its full arsenal, including nuclear weapons, to defend its territory if NATO tried to isolate the Baltic exclave, and raised the possibility of strikes on decision-making centers in member states from the outset. NATO Secretary General Mark Rutte said the alliance replied that it is defensive and told Moscow to "stop the nuclear threats," while adding that he does not take the warning very seriously and sees no real risk of nuclear use against the Baltics. The note follows statements from Russian embassies in at least three European countries accusing NATO of escalating tensions through exercises involving Kaliningrad, which the Kremlin called reminders for "hotheads in Europe," as European governments accuse Moscow of a "hybrid war" of sabotage and arson, which Russia denies.
The euro slides for a third straight session as US yields stay elevated and eurozone inflation worries build. EUR/USD closed near 1.133 after briefly testing its 2026 lows around 1.131, with wide yield gaps against the US, dovish commentary from European Central Bank President Christine Lagarde, and signs of stagflation in the euro area, including inflation of 3.0% in France and 4.2% in Italy, keeping the broader trend bearish.
MANAGEMENT & FED SPEAK
Lisa Cook, Federal Reserve Governor, on the inflation fight:
Cook said she is committed to returning inflation to the Fed's target while preserving strength in the labor market, adding that "inflation has been too high for too long." Her remarks, delivered at a Richmond Fed conference on rural America, only briefly touched on monetary policy and did not address the latest inflation data.
Sanjay Mehrotra, Chairman and CEO, Micron Technology, on the company's outlook:
"Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027."
Michael Rubiera, CEO, Accelevation, on data-center demand after its IPO:
"We're seeing continued momentum across all of our product lines."
Barry Quart, CEO, Connect Biopharma, on its COPD trial data:
Quart said the Phase 2 results provide "overwhelming evidence of the potential benefit" of early treatment for COPD patients suffering an acute exacerbation, adding that the company will seek alignment with the FDA on a Phase 3 program as soon as feasible.
CORPORATE ACTIONS & EARNINGS CALENDAR
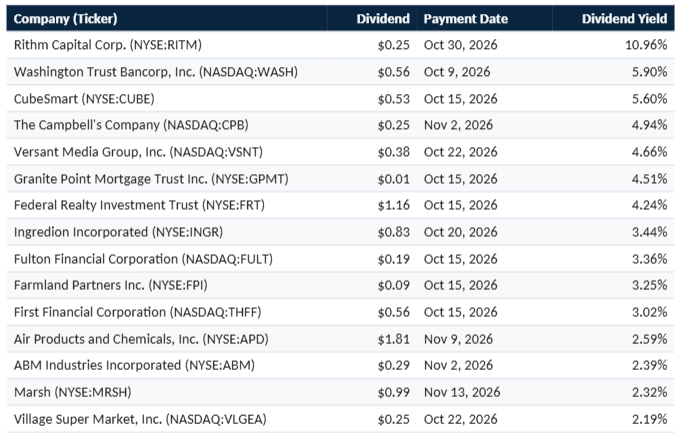
Top Ex-Dividend Companies for Thursday, October 1:
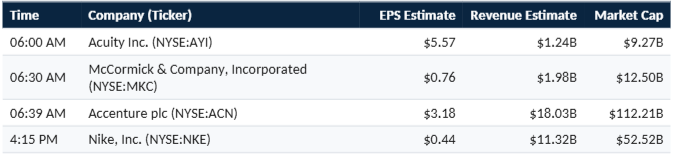
Upcoming Earnings (Thursday, October 1):
Economic Calendar (Thursday, October 1):
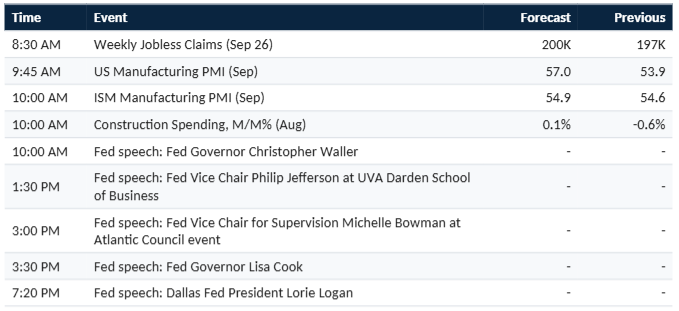
That's the wrap for today. Attention now turns to Thursday's ISM manufacturing reading and a busy slate of Fed speakers, then Friday's September jobs report, which could decide whether the market's retreat from an October rate hike holds, even as the US-Iran exchange over Hormuz keeps oil and yields in play.