ASX Post-Market Wrap: 16 September 2026
The ASX clawed back from an 11-week low as energy, gold and copper all caught a bid at once, but all eyes are now on tonight's Fed decision, with markets pricing in near-certain odds of the first rate hike in three years.
Miners Snap a Losing Streak as Bond Yields Steady Ahead of the Fed
Welcome to ASX Post-Market Wrap, your quick end-of-session rundown of what moved the Australian market today, plus what's shaping global sentiment into tonight's Wall Street open.
Markets Today
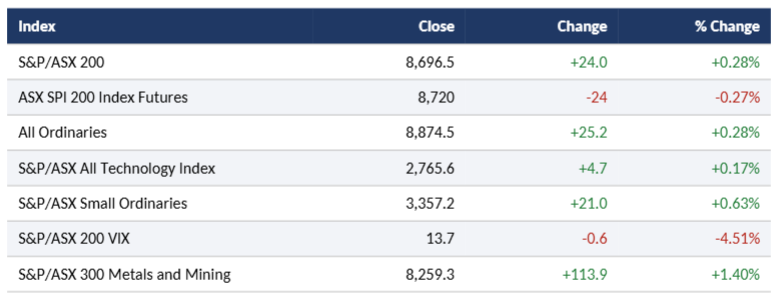
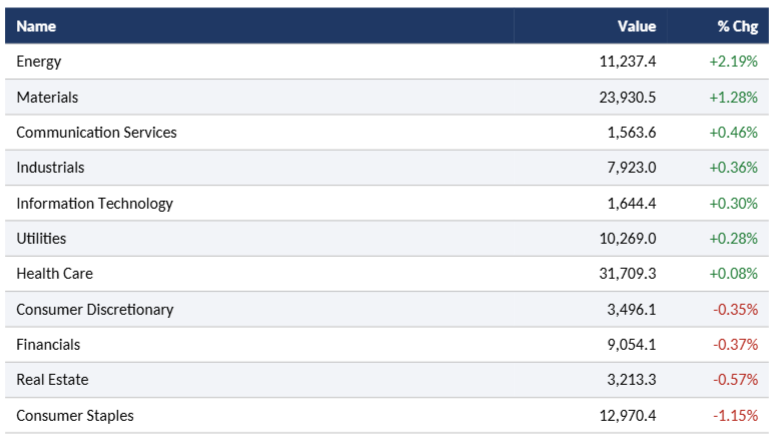
The ASX 200 rose for the first time in five sessions on Wednesday, adding 24.0 points, or 0.28%, to 8,696.5, reversing Tuesday's slide to an 11-week low. The All Ordinaries followed it up, gaining 25.2 points, or 0.28%, to 8,874.5. It was a narrow but broad-based advance: advancers edged out decliners 154 to 122 on the S&P/ASX 300, with seven of the eleven sectors finishing in the green. Energy led the charge, catching the tailwind from Monday's overnight crude surge even as oil itself eased through the session, while miners snapped a four-day losing streak as a softer US dollar helped copper and gold prices rebound. Consumer Staples and Real Estate lagged as money rotated back out of the defensive names that had led Tuesday's session.
Analytical View
Energy and miners did the heavy lifting. Energy jumped as much as 3% intraday, its largest single-day gain in more than a month, as refiners and producers alike treated Monday's crude spike as durable rather than a one-off: Viva Energy rose 3.3%, Ampol 2.5%, Beach Energy 3.4%, Woodside 2.8%, Santos 2.1% and Karoon Energy 2.2%. Miners snapped a four-day losing streak, up 1.4%, as a softer US dollar and steadying bond yields took pressure off copper and gold: BHP rose 1.6% to reclaim the $60 mark for the first time in a week, Rio Tinto added 1.1% and Fortescue gained around 2%. Gold stocks rose 1.5% as the twin forces that hammered the sector through September, surging yields and rising diesel costs, both eased at once, while silver's 2.3% jump lifted South32 3.1% as owner of Australia's largest silver mine. On the other side of the ledger, Consumer Staples fell 1.1% in a mirror image of Tuesday's defensive rotation, led down by Endeavour Group's 3.8% slide, while Real Estate slipped 0.5% as bond-proxy trusts stayed out of favour with risk-free yields still elevated. Financials fell 0.4% as insurers gave back some of Tuesday's gains ahead of the Fed, with Suncorp down 3.2% and Insurance Australia Group down 2.5%, though the big four banks were only mildly softer. Reliance Worldwide jumped as much as 4.3% after agreeing to a US$2.8 billion buyout from Brookfield.
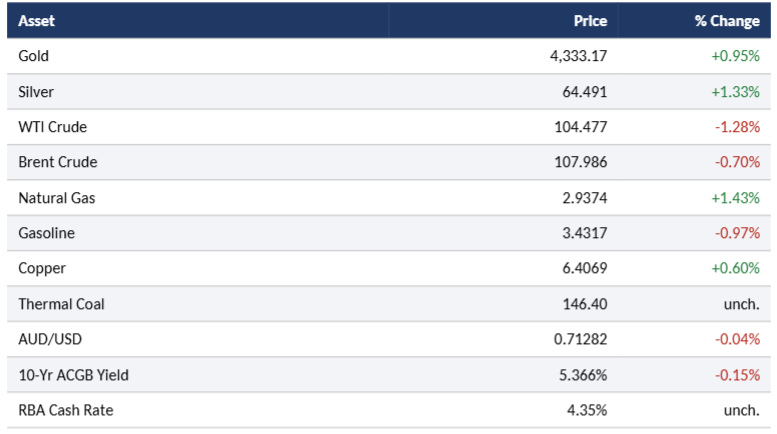
The bigger picture is a market pausing to reassess after a brutal run. The US 10-year Treasury yield eased slightly from Monday's high above 5%, but traders still assign a 92% probability to a quarter-point Fed hike at Thursday morning's decision (AEST), which would be the first US rate rise since 2023. Brent crude eased around 1% to a touch above US$107 a barrel as a reported build in US crude inventories offset lingering supply risk from Saudi Arabia's shuttered East-West pipeline and an intercepted Houthi drone near Mecca, the first strike to reach the holy city in this conflict. Wall Street fell overnight on the same yield pressure, with the S&P 500 down 0.4% to 0.45% and the Nasdaq off around 0.8% as consumer discretionary names bore the brunt, while Asian markets were mixed into Wednesday. Locally, attention is also turning to Governor Bullock's testimony before Parliament on Friday, and to a market debate over just how far the RBA still has to go: some strategists now see the cash rate reaching as high as 5% by mid-2027, a view others call unlikely given Australia's near-40-year run without a recession.
What could change the picture: the Fed's rate decision on Thursday morning (AEST), and RBA Governor Bullock's testimony before Parliament on Friday. (For Further Reading: Fed Decision Tomorrow: What the September Rate Hike Means for Stocks, Bonds, and Your Portfolio)
Sector Performance
Winners & Losers
Top 5 Gainers:
- EQR (EQ Resources Ltd): +11.69% to $0.43
- EIQ (Echoiq Ltd): +11.34% to $0.54
- 4DX (4DMedical Ltd): +8.72% to $3.74
- TLX (TELIX Pharmaceuticals Ltd): +8.63% to $17.75
- APX (Appen Ltd): +8.38% to $1.035
Top 5 Decliners:
- VYS (Vysarn Ltd): -9.09% to $0.75
- CXO (Core Lithium Ltd): -8.97% to $0.355
- CRN (Coronado Global Resources Inc): -8.16% to $0.225
- SMI (Santana Minerals Ltd): -8.04% to $0.515
- HCH (Hot Chili Ltd): -7.72% to $1.435
Volume Outliers
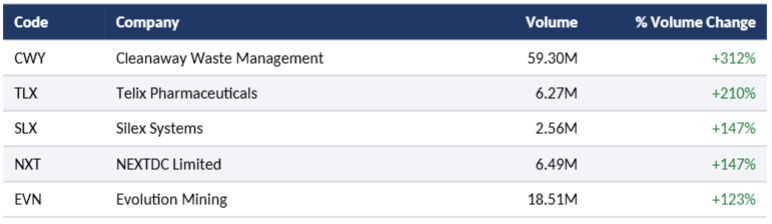
Stocks trading furthest above their 90-day average volume:
Broker Moves
52-Week Highs & Lows
Commodities & Rates
Top Stories: Australia
Reliance Worldwide agrees to a $3.9 billion Brookfield buyout. The Melbourne-based plumbing supplies group agreed to be acquired by Brookfield Asset Management for US$2.8 billion (A$3.9 billion), with shareholders offered US$3.38 (A$4.75) a share, a 43% premium to the six-month average price. Shares jumped as much as 4.3% to $4.52 before settling back to $4.50. The deal includes a "go shop" provision giving the board until October 15 to seek a higher offer, and Brookfield has the right to match any rival bid. Founded in Brisbane in 1949 and listed on the ASX in 2016, Reliance employs around 2,800 people across 58 locations and generates most of its revenue in North America.
Anthropic signs its first Australian data centre lease. The Claude developer has signed a long-term lease at Queensland's Western Downs Digital Park, a roughly $30 billion project being developed by Singapore's Zerra DC near Dalby, north-west of Toowoomba. The facility, due to start operating next year subject to approvals, will be used for inference rather than training, sidestepping an ongoing dispute with the federal government over copyright in AI training data. The 725-hectare site, currently a cattle feedlot, was chosen for its proximity to gas plants, a solar farm and transmission infrastructure, and could employ up to 1,500 workers at full build-out. Anthropic is separately preparing a Nasdaq listing at a reported valuation of around US$2 trillion.
Private credit investor Longwave Capital warns more property developers are "on the brink." The Pinnacle-backed fund manager, which oversees about $4 billion, sold its only private-credit exposure, Centuria Capital, after concluding the collapse of Sydney developer Bathla exposed problems that go well beyond a single company. Centuria has $278 million secured across six Bathla developments and has frozen redemptions in some funds, while other lenders including RMBL Investments and Ray White Capital have lodged claims of $319.5 million and $216.8 million respectively. Longwave's David Wanis said investors burned by Bathla are likely to grow reluctant to commit fresh capital to private credit more broadly, a dynamic that could compound the pressure facing other developers.
Humm Group freezes staff pay while directors' fees jump. The non-bank lender told staff there would be no merit-based pay rises this year citing the need to manage costs, even as its annual report showed base board fees rising from $100,000 to $130,000 and the chair's base pay from $150,000 to $250,000 in the first full year those increases took effect. Two directors who resigned only ten months into the financial year, ahead of an extraordinary general meeting where activist shareholders had planned to remove them, still saw substantial pay rises for the year. Shareholders delivered a first strike against Humm's prior remuneration report, and the increases will face a fresh vote at the next AGM.
Pantoro Gold reports high-grade extensions at Racetrack Discovery. Pantoro rose 9.3% on a combination of broader gold sector strength and what management called "significant" extensions to high-grade mineralisation at its Racetrack Discovery prospect, including intercepts of 11.12 metres at 5.48 grams per tonne gold and 2.0 metres at 24.11 grams per tonne gold.
Tungsten Mining confirms Watershed product specification, Nasdaq listing on track. Tungsten Mining rose 5.3% after completing metallurgical testwork confirming its Watershed project in Queensland can produce a plus-50% or plus-65% tungsten trioxide product, while separately flagging that preparations for a secondary Nasdaq listing are "progressing well" with a target of the fourth quarter of 2026.
Iron ore's rebound above US$100 fizzles as China's steel mills struggle. Iron ore futures fell nearly 5% over the past week to about US$96 a tonne as higher steel-making input costs squeezed Chinese producer margins, with only 8% of the country's steel mills profitable last week, down from 30% the week before. The price is expected to trade between US$90 and US$95 for the rest of the year, as softer Chinese demand is only partly offset by constrained supply from Australia and Brazil. BHP and Rio Tinto, among the world's lowest-cost producers, are expected to stay strongly cash generative even if prices fall toward US$80, while Fortescue's heavier reliance on iron ore makes its earnings more sensitive to further price falls.
Global Stories
Markets brace for the Fed's first hike since 2023. US futures edged higher ahead of Thursday morning's decision (AEST), with traders pricing a 92% probability of a quarter-point rise and smaller odds of further hikes in October (45%) and December (30%). White House economic adviser Christopher Phelan called a hike a "mistake," arguing inflation data has been heading in the right direction, after August CPI came in at 3.4% year-on-year, down from a May peak of 4.2%, though core inflation ran hotter than expected at 0.3% month-on-month. The 10-year Treasury yield touched as high as 5.04% this week before easing slightly, still its highest sustained level since before the 2007 financial crisis, and Wall Street fell overnight as consumer discretionary names led the retreat: Chipotle dropped 5.9%, Darden Restaurants 4.3% and Dollar Tree 5.4%. Crypto-linked stocks also fell after the US Senate blocked a bill creating a regulatory framework for the industry, with Bitcoin down 3% and Coinbase down more than 10%.
Fighting reaches Mecca for the first time as the Middle East conflict widens. Saudi Arabia said its air defences intercepted and destroyed a Houthi drone before it could enter the airspace over Mecca, Islam's holiest site, a claim the Iran-backed group rejected. The incident follows last week's attack on Saudi Arabia's East-West pipeline, which put around 4 million barrels a day of oil at risk, and comes as the seven-day average of oil transiting the Strait of Hormuz has recovered to nearly 12 million barrels a day, still less than 60% of pre-war levels.
UK inflation jumps to 3.1% as fuel costs surge. Britain's annual inflation rate rose to its highest reading since March, driven by a 23% year-on-year jump in motor fuel costs as the Iran war's energy shock continues to feed through to consumer prices. The print lands a day ahead of the Bank of England's own rate decision, with markets pricing an 80% chance the BoE holds steady this month before a hike in November.
China's fuel stockpiles shrink, raising the risk of fresh export curbs. Gasoline inventories at Chinese state-owned suppliers fell 2.9% last week to their lowest level since 2022, while diesel holdings dropped 2.4% to a 15-month low, according to JLC International. Beijing curbed fuel exports early in the US-Iran war before easing the restrictions, and analysts now see a growing chance authorities could again restrict clean product exports to around 1.2 million tonnes in the fourth quarter if the domestic market keeps tightening.
Zuckerberg breaks with Anthropic's Amodei on AI safety, backs Nvidia's Huang. Meta's chief executive took a more market-driven stance than Anthropic chief Dario Amodei, whose weekend essay calling for the industry to slow the pace of capability development has dominated debate at San Francisco's Dreamforce conference. Nvidia's Jensen Huang argued existing product-liability law makes new AI-specific regulation "completely unnecessary," while OpenAI's Sam Altman said he understood the appeal of industry coordination on safety but worried competitive pressure between companies and countries could undermine it.
Management & RBA Speak
Mark Zuckerberg, Chief Executive, Meta, on AI safety and why his company delayed a product launch:
Zuckerberg said AI labs that fail to focus on alignment "will fall behind," taking a market-driven view that trust and safety are becoming key differentiators between AI companies rather than something that needs new regulation. He said Meta had itself "delayed shipping" its Muse AI technologies on safety and security grounds, describing it as a decision the company made on its own initiative rather than in response to outside pressure.
Kevin Warsh, Chair, US Federal Reserve, on the case for tonight's decision:
In his Jackson Hole address last month, Warsh said price stability "is not self-executing," framing high inflation as the Fed's "predominant focus" and arguing he would be "hard pressed" to call current financial conditions restrictive, a signal markets have read as clearing the way for tonight's expected hike. Warsh has also said the Fed will stop offering forward guidance on future moves, preferring markets react to incoming data rather than anticipate the central bank's reaction to it.
Christopher Phelan, Chairman, White House Council of Economic Advisers, on why the Fed should hold:
Phelan said raising rates now "doesn't make sense," arguing inflation data has been moving in the right direction and that a hike would risk unwinding that progress just as the economy adjusts to elevated energy costs from the Middle East conflict.
That's the wrap for today's session. The Fed hands down its decision in the early hours of Thursday AEST, with Governor Bullock's testimony before Parliament on Friday the next domestic test before the RBA's own call on 28-29 September.