ASX Pre-Market: Wednesday, 16 September 2026
ASX 200 futures point to a firmer open ahead of Thursday's Federal Reserve decision, even as Wall Street fell overnight and the US 10-year Treasury yield touched its highest level since 2007.
Welcome to your morning briefing on overnight Wall Street action and what's set to move the ASX 200 at the open. (See yesterday's ASX Post-Market Wrap: 15 September 2026 & The Wall Street Wrap: September 15, 2026 for the full session recap.)
ASX Futures
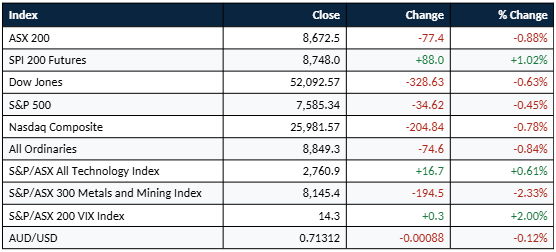
SPI 200 futures were up 88 points, or 1.02%, to 8,748, pointing to a firmer open after Tuesday's local session closed at an 11-week low. The stronger lead follows Tuesday's close, where the ASX 200 fell 77.4 points, or 0.88%, to 8,672.5, and comes despite a further leg down on Wall Street overnight, as oil extended its advance and the US 10-year Treasury yield touched its highest level since 2007 ahead of the Federal Reserve's rate decision, due at 4am AEST Thursday.
Overnight Leads + This Morning
Tuesday's local session was a broad retreat rather than a narrow one. The ASX 200 fell 77.4 points, or 0.88%, to 8,672.5, a fresh 11-week low and its worst level in three months, as decliners outnumbered advancers 664 to 403 on the broader market, with 393 stocks unchanged. Miners and financials did the damage: Materials fell 2.21% as copper came under pressure from AI-safety-guardrail concerns denting hopes for AI-driven metals demand, while gold stocks fell even harder as rising bond yields increased the opportunity cost of holding bullion. Financials fell 1.08% as bets narrowed further on a September RBA hike. Health Care bucked the trend, jumping 1.5% as money rotated into defensive earnings, led by 4DMedical, Telix Pharmaceuticals and Healius, with Consumer Staples adding 0.9% on the same logic, led by A2 Milk. EQ Resources jumped 11.7% on a binding tungsten-processing deal, while NEXTDC fell 4.0% on shareholder notices flagging securities-lending activity. The index has now lost 2.78% over the past five sessions, though it remains virtually flat for the year.
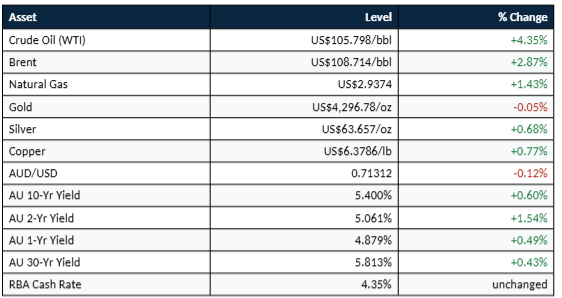
Overnight, Wall Street fell for a further session as Treasury yields surged to multiyear highs ahead of Wednesday's Federal Reserve decision. The Dow lost 328.63 points, or 0.63%, to 52,092.57, the S&P 500 fell 0.45% to 7,585.34, and the Nasdaq dropped 0.78% to 25,981.57. Losses were partly offset by gains in AI-related names that had been under pressure the prior session, with Coherent adding more than 1%, AMD up 2%, and Qualcomm advancing 5%. The US 10-year Treasury yield rose as high as 5.041% intraday, its highest since 2007, before easing slightly to trade around 5.012%. Oil extended its advance further, with Brent trading above $109 a barrel and WTI above $106, after Saudi Arabia reportedly cancelled some September crude cargoes to European customers following the East-West pipeline closure. Fed funds futures were pricing roughly a 90% to 94.5% probability of a quarter-point hike at Wednesday's meeting, according to various measures of the CME FedWatch Tool.
Close Levels
Analytical View
Tuesday's local session showed a market falling on genuinely broad grounds rather than being dragged down by one sector. The split between Materials and Financials on one side, and Health Care and Consumer Staples on the other, reflects a straightforward rotation into defensive earnings as rate-hike expectations firmed both locally and in the US. Miners took the additional hit of AI-safety concerns denting the metals-demand narrative that had underpinned copper, while gold's own decline despite the risk-off tone is a reminder that rising real yields can outweigh gold's traditional safe-haven appeal. The five-day decline of 2.78% shows the index has not meaningfully stabilised since last week's broader selloff, even though it remains close to flat for the year.
Overnight, Wall Street's session was dominated by the bond market rather than equities themselves. The 10-year Treasury yield's move to its highest level since 2007, a genuinely significant threshold last sustained around the turn of the millennium, reflects the market pricing in both a hawkish Fed and the inflationary pressure from oil prices that continue to climb on the Saudi pipeline closure. The partial rebound in AI-related names, a reversal from Monday's rout, suggests some of the AI-slowdown selloff may have been overdone, though the broader market's decline shows the yield story is now the dominant driver rather than any single sector narrative. For the ASX 200, that combination, a higher-for-longer rate environment globally alongside continued oil-driven inflation risk, keeps pressure on the same rate-sensitive banks and REITs that drove Tuesday's local weakness, even as the futures market points to a firmer open.
What could change the picture: The Federal Reserve's rate decision, due at 4am AEST Thursday, is the immediate catalyst, with markets pricing between 90% and 94.5% odds of a quarter-point hike depending on the measure, ahead of the RBA's own call on 29 September, now priced at a roughly 77% probability of a hike.
Commodities & Rates
Home & Away
Names with a foot in both camps today, ASX movers with direct overseas read-through, and overseas news with a local echo.
EQ Resources (ASX:EQR): rose 11.7% Tuesday after signing a binding agreement with The Elmet Group and Blue Moon Metals for a 10% stake in a Nevada tungsten processing restart, backed by US Department of War funding, with an eight-year offtake covering 4,000 tonnes of contained tungsten trioxide.
Coherent (NYSE:COHR), Advanced Micro Devices (NASDAQ:AMD) and Qualcomm (NASDAQ:QCOM): all rose overnight, up more than 1%, 2% and 5% respectively, partially reversing Monday's AI-related selloff even as the broader market fell on the Treasury yield surge. The rebound suggests some of Monday's AI-slowdown reaction may have been overdone, though the fact the broader indices kept falling regardless shows the bond market, not AI sentiment, is now the dominant force heading into Wednesday's Fed decision.
Bitcoin, Coinbase (NASDAQ:COIN) and Circle (NYSE:CRCL): fell overnight after the Senate blocked the Clarity Act crypto market-structure bill from advancing, with Bitcoin down 3-4%, Coinbase down 8%, and Circle down 10-11.6%. The bill needed 60 votes to clear a procedural hurdle and fell short after Republicans and Democrats couldn't resolve disagreements over ethics provisions tied to profits from crypto ventures, a failure that effectively ends market-structure legislative work in the Senate for 2026.
Copper remains relevant to Australian miners despite the overnight rebound. Copper rose 0.77% to US$6.3786/lb overnight after coming under pressure in the previous Australian session. That modest recovery provides some relief for copper-exposed ASX miners after the ASX 300 Metals and Mining Index fell 2.33% on Tuesday. The local market's recent weakness has partly reflected concerns that AI-related safety restrictions could reduce expectations for metals demand, so the overnight copper move may help sentiment at the margin without reversing the broader uncertainty around the demand outlook.
Local Catalysts
Mortgage applications drop sharply, first-home buyers hit hardest. Equifax data showed mortgage applications fell 14.1% year-on-year in August, with applications from 18-25 year-olds down 21.7% and first-time homebuyers down 20.1%, the largest annual decline the credit agency has recorded for first-time buyers since 2022. All big four banks reported double-digit declines in mortgage applications in August, with Commonwealth Bank noting home loan applications down 15% since May. National home prices have fallen 3.6% since a March peak, according to Cotality, with William Buck forecasting a 5% decline for 2026 and Sydney and Melbourne facing the steepest falls, at 11% and 10% respectively.
Cue Clothing collapses into voluntary administration. The Sydney-based fashion label, which also owns Veronika Maine, entered voluntary administration after more than six decades in business, with FTI Consulting appointed receivers and Duncan Clubb and Shaun Mckinnon of BDO appointed voluntary administrators, effective September 15. The collapse affects 51 stores across Australia and New Zealand. A Hilco Capital spokesperson said rising sales had not offset overhead costs, and a sale process seeking a buyer as a going concern has begun immediately.
Catalyst Funds Management's Deepan Pavendranathan triples assets to $2.5 billion. SEC disclosures show Catalyst's US shareholdings rose from $590 million at the end of the March quarter to $1.78 billion ($2.5 billion) by the end of June, with the increase reportedly driven by a rotation of capital into US equities rather than new inflows. The fund's largest position is a $72.3 million holding in Apple, up eight-fold across the two quarters, alongside a position in Bloom Energy. Pavendranathan, a former Regal Global Alpha Fund co-manager who left to found Catalyst in 2021, has also been linked to trading around SpaceX's June IPO.
Global News
Oil extends its advance as Saudi Arabia cancels European crude cargoes. WTI settled up 4.4% at $105.83 a barrel Tuesday, its highest close since May 19, while Brent rose 2.9% to $108.75, with prices up more than 20% this month. Trade sources told Reuters the Saudis have informed European customers that some September crude deliveries are cancelled following the East-West pipeline's closure. US Energy Secretary Chris Wright said he expects the pipeline to restart within days, calling the disruption "brief and temporary." Libya's national oil company separately suspended operations at two oilfields and a pumping station amid protests, and Houthi militants launched renewed drone and missile strikes on the Saudi cities of Khamis Mushait, Abha and Taif.
US Treasury yields hit their highest level since 2007 ahead of the Fed decision. The 10-year Treasury yield rose as high as 5.041% before easing to around 5.012%, extending a seventh straight monthly rise, the longest run since 2011. Fed funds futures are pricing between 90% and 94.5% odds of a quarter-point hike at Wednesday's meeting, which would be the central bank's first since 2023.
China's factory strength masks weakening consumer demand. Industrial output rose 5.2% in August, ahead of expectations and accelerating from July's 4.5%, on export growth tied to global AI electronics demand, but retail sales grew just 0.4% against forecasts for 0.8%, dragged down by an 18.5% slump in auto sales. Fixed-asset investment fell 7.2% over the first eight months, and new bank lending badly missed forecasts, expanding by just 60 billion yuan against a roughly 400 billion yuan forecast.
Senate blocks crypto market-structure bill in setback for the industry. A procedural vote on the Clarity Act failed 50-49, short of the 60 votes needed to advance, after Republican and Democratic negotiators could not resolve disagreements over ethics provisions related to profits from crypto ventures. The bill would have divided crypto oversight between the SEC and CFTC and established registration and anti-money-laundering requirements.
OpenAI, Google and Anthropic in talks on coordinated AI safety standards. OpenAI confirmed it has been engaging with Anthropic and Google about working together on safety concerns, discussions that have been ongoing since Google DeepMind chair Demis Hassabis proposed a US-led "Standards Body" in July. Separately, Elon Musk called for the leading AI labs, including several Chinese companies, to let rivals run a "test harness" on each other's models before public release, saying competitors would be more likely to catch safety issues than a company evaluating its own work.
Management & Fed / RBA Speak
Scott Bessent, US Treasury Secretary, on plans to meet China's Vice Premier:
Told a House Financial Services Committee hearing that he would meet Chinese Vice Premier He Lifeng this weekend, ahead of a planned meeting between President Trump and President Xi Jinping next week. "With China, we have had some very good private discussions, and I look forward to those continuing this weekend," Bessent said, adding that discussions with Beijing on countries supporting Iran are ongoing.
Abigail Bradshaw, Director-General, Australian Signals Directorate, on the need for an AI early warning system:
Said Australia has the equivalent of an early warning system for cyber threats but not yet for AI-specific risks, and that bringing together reports of individual incidents would help identify wider patterns. She said government access to leading AI companies' models had let her agency complete in hours work that would otherwise take weeks, while cautioning organisations to keep basic security measures in place rather than relying on AI alone.
Corporate Actions & Earnings Calendar
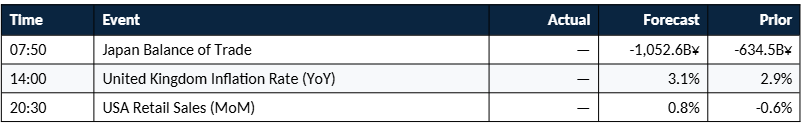
Economic Calendar (Wednesday, 16 September):
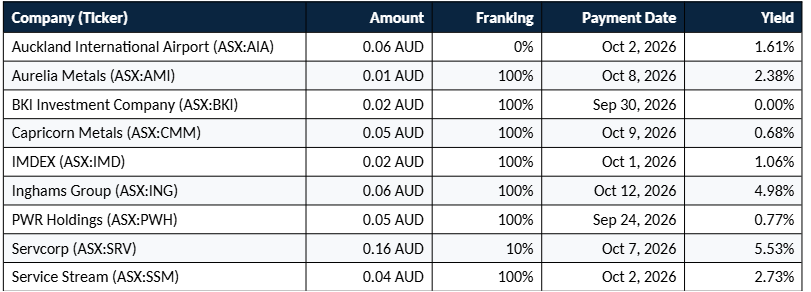
Ex-Dividend Today (Wednesday, 16 September 2026):
Closing Line
That's the pre-market wrap for today. The ASX looks set to shrug off overnight weakness on Wall Street, with SPI 200 futures pointing to a firmer 1.02% open even as the US 10-year Treasury yield touched its highest level since 2007 and oil continued to climb on the Saudi pipeline disruption. The Federal Reserve's rate decision, due at 4am AEST Thursday and now priced at up to 94.5% odds of a hike, is the immediate catalyst, ahead of the RBA's own call on 29 September.