ASX Post-Market Wrap: 17 September 2026
The ASX 200 climbed for a second straight session as banks posted their best day in over a month, with investors taking comfort from easing bond yields rather than reacting badly to the Fed's first rate hike since 2023. A Citi upgrade of NAB added extra fuel to the financials rally, while gold miners slid on hawkish signals from Fed Chair Kevin Warsh.
Welcome to ASX Post-Market Wrap, your quick end-of-session rundown of what moved the Australian market today, plus what's shaping global sentiment into tonight's Wall Street open.
Markets Today
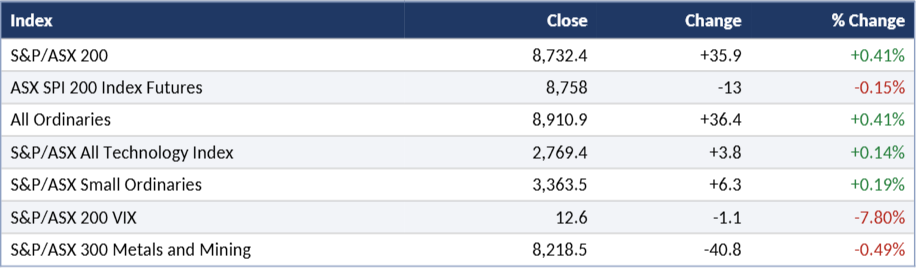
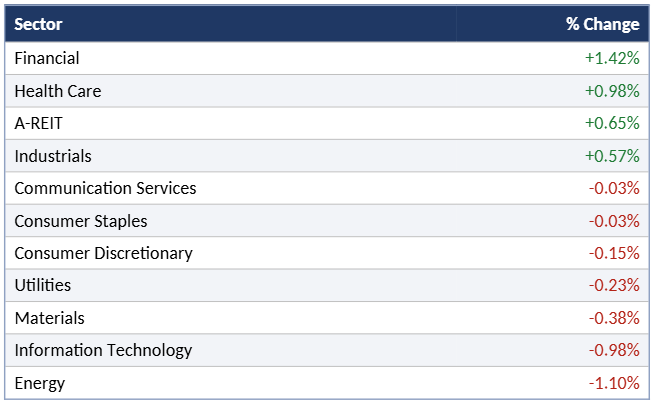
The ASX 200 rose for a second straight session on Thursday, adding 35.9 points, or 0.41%, to 8,732.4, having traded as much as 1% higher earlier in the day before paring gains. It was a session that looked stronger on the index than underneath it: in the broader S&P/ASX 300, advancers edged out decliners by a narrow 146 to 130, while at the sector level just four of eleven groups finished in the green. Financials did the heavy lifting, its best session in over a month, as the big four banks all rallied more than 1% and investors took comfort from US Treasury yields easing rather than reacting badly to the Fed's rate hike itself. Energy and Information Technology were the session's laggards, tracking a retreating oil price and a softer Nasdaq respectively.
Analytical View
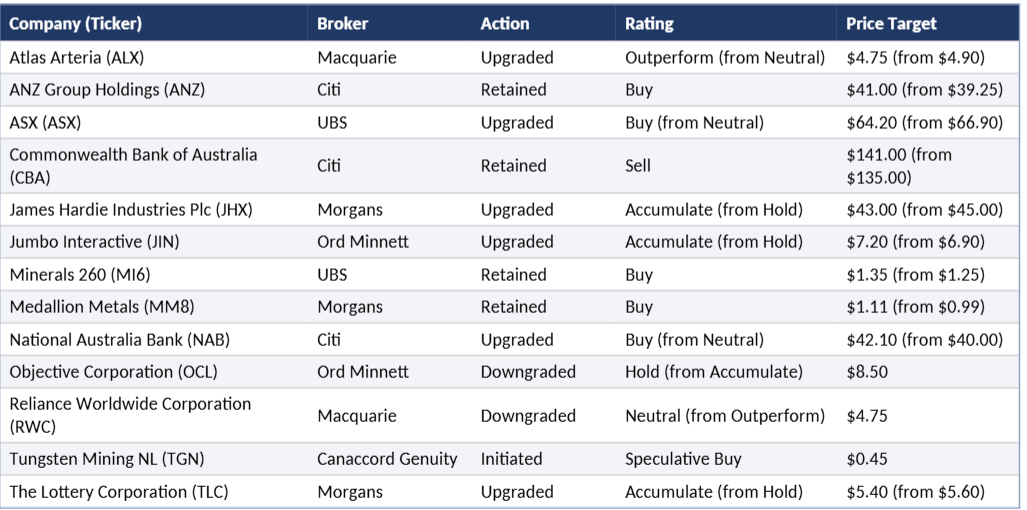
Financials led, up 1.42% for its best day in over a month, but the story behind the move had two layers. The bigger one was macro: the Fed's quarter-point hike to 3.75-4.00% was exactly what markets had priced in, and with that uncertainty removed, the US 10-year yield actually eased 2 basis points to around 5%, ending an eight-day run higher, while Australia's own 10-year slipped 2 basis points to 5.33%. That relief rally lifted banks broadly, with NAB, ANZ, CBA and Westpac all firmer, and insurers QBE and Insurance Australia Group up alongside them. Layered on top was a stock-specific catalyst: Citi upgraded National Australia Bank to Buy from Neutral and lifted its price target to $42.10 from $40, and NAB's 3.2% gain made it the best performer of the big four, giving Financials an extra kick beyond what the yield relief alone would have delivered. Health Care added 1.0%, continuing its run as investors keep rotating into defensive earnings regardless of which way the broader tape is moving, with Telix Pharmaceuticals, Cogstate, Pro Medicus, CSL and Ansell all higher.
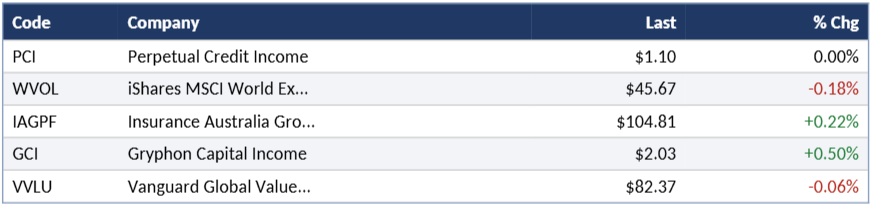
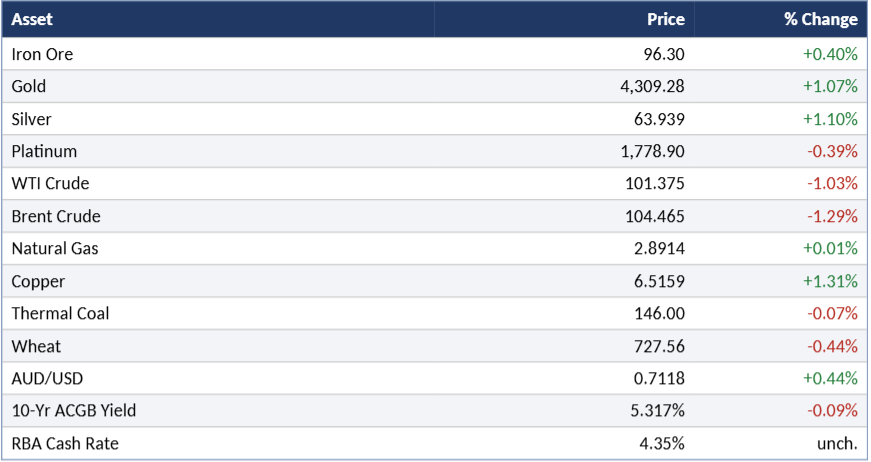
Materials was only modestly negative at the headline level, down 0.38%, but that number masked a three-way split. Gold miners were hit hardest as the Gold Sub-Index fell 2.0%: bullion had rallied into the Fed decision on classic buy-the-rumour positioning, then reversed once Fed Chair Kevin Warsh's press conference signalled the committee isn't done tightening, sending COMEX gold from an overnight gain of 1.3% to a 0.9% slide in Asian trade. Base metals names also softened as the hawkish signal dampened risk appetite for cyclicals, while small-cap copper stocks bucked the trend on firmer COMEX copper prices, and iron ore miners logged a second straight day of gains as SGX futures added another 0.4%. Energy fell 1.10% as Brent and WTI both retreated further in Asian trade, extending an overnight slide that came as Saudi Arabia arranged ship-to-ship crude transfers through Oman's Sohar port to offset its damaged East-West pipeline, easing supply fears. Technology fell 1.0% tracking a softer Nasdaq, the familiar dynamic of higher risk-free rates weighing on long-duration growth names.
The bigger picture is a market that took the Fed's first hike in three years about as well as it could have. Sixteen of eighteen Fed officials now see at least one more hike this year, and traders are pricing an 85% chance the RBA follows with its own 25-basis-point move on September 29, taking the cash rate to 4.6% with a further move to 4.85% seen as plausible by early 2027. The Australian dollar eased to the US70.9¢ level, down from a recent peak near US72¢ but still well above where it sat a year ago. Asian markets were mixed: Japan's Nikkei added 0.33%, Korea's Kospi was flat, while Hong Kong and mainland China both slipped. The Bank of England is expected to hold rates steady on Thursday despite UK inflation climbing to 3.1%, a divergence from the Fed, ECB and an expected Bank of Japan move this week.
What could change the picture: RBA Governor Bullock's testimony before Parliament on Friday, and the RBA's own rate decision on September 28-29.
Sector Performance
Winners & Losers
Top 5 Gainers:
- FTI (Fortifai Ltd): +15.86% to $0.84
- EIQ (Echoiq Ltd): +14.56% to $0.59
- CTD (Corporate Travel Management Ltd): +12.55% to $2.60
- AYA (ARTRYA Ltd): +10.98% to $3.64
- AMA (AMA Group Ltd): +9.43% to $0.58
Top 5 Decliners:
- LNW (Light & Wonder Inc): -8.17% to $113.57
- PNR (Pantoro Gold Ltd): -7.45% to $2.61
- WAF (West African Resources Ltd): -7.37% to $3.52
- BGP (Briscoe Group Australasia Ltd): -6.78% to $3.44
- DTR (Dateline Resources Ltd): -6.67% to $0.07
Volume Outliers
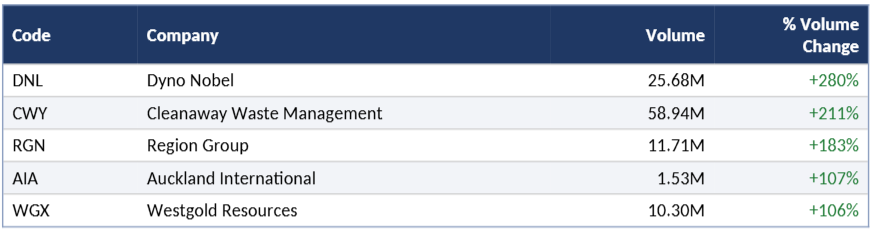
Stocks trading furthest above their 90-day average volume:
Broker Moves
52-Week Highs & Lows
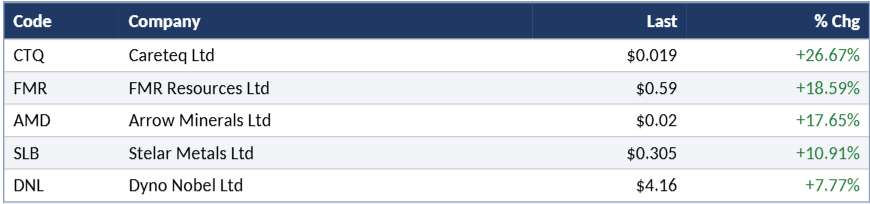
Highs:
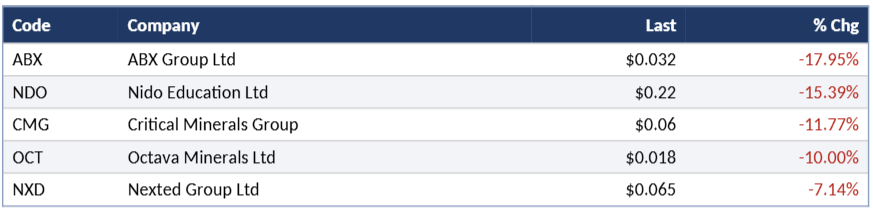
Lows:
Near Highs
Commodities & Rates
Top Stories: Australia
ASX set for almost $40 billion in dividends over the next two months. Investors are on track to receive close to $40 billion in dividends from ASX-listed companies over the next two months, with roughly $28 billion due this month and a further $10 billion in October, according to Bell Potter data. The windfall follows a bumper August reporting season in which two-thirds of listed companies lifted their payouts, taking total dividends for the past financial year to $105.9 billion, the third-highest on record and an end to three consecutive years of decline. Resources companies led the way: BHP lifted its dividend more than 50% on higher commodity prices, Rio Tinto raised its payout 34%, and Sandfire Resources reinstated a dividend after several fallow years. Lithium producers Mineral Resources, IGO and PLS all resumed distributions, while gold miners Genesis Minerals and Alkane Resources declared maiden dividends. Ampol's profit surged almost fivefold on the back of disrupted global fuel markets, funding an interim dividend of $1.85 a share, up from 40 cents a year earlier. Commonwealth Bank lifted its own payout to a record $2.70 a share even as its mortgage application volumes have fallen around 17% since May's federal budget and its shares trade near an eight-month low, prompting some caution that the dividend could come under pressure if lending conditions keep deteriorating. Buybacks added to the capital-return story, led by CSL's $1.1 billion program, Telstra's $1 billion buyback and Challenger's $300 million program.
Bathla collapse could spread "second-order stress" through construction, Morgan Stanley warns. The administration of property developer Bathla poses limited direct risk to the major banks but could add to broader stress across construction and property development, where credit quality can deteriorate quickly once a large developer fails. The warning follows Bathla's collapse into voluntary administration, which has already seen lenders move to recover losses through the sale of seized development sites.
Macquarie faces class action over Shield Master Fund collapse. Law firm Gordon Legal has launched a class action against Macquarie Group on behalf of roughly 2,800 investors who had exposure to the collapsed Shield Master Fund through Macquarie's investment platform. Macquarie has already agreed to refund the $321 million in capital losses suffered when the fund collapsed in 2024, but the claim alleges investors haven't been fully compensated for the lost opportunity for their retirement savings to grow while the money was tied up in the failed scheme.
MA Financial takes 50% stake in Melbourne's The Glen shopping centre. MA Financial Group has acquired a 50% stake in The Glen Shopping Centre, valued at $327.5 million, while simultaneously launching a new large-format retail fund. The centre, which underwent a substantial redevelopment completed in 2022, is running at 99% occupancy and is anchored by a largely non-discretionary retail mix; the deal implies a passing yield of approximately 7% and is expected to settle in the fourth quarter. The group has now transacted on $500 million of real assets in the second half of the year and is in advanced due diligence on two further acquisitions for the new fund.
Global Stories
Fed delivers first rate hike since 2023, signals more to come. The Federal Reserve unanimously lifted its federal funds rate a quarter point to 3.75-4.00%, its first increase in three years, citing persistently elevated inflation. Updated projections showed 16 of 18 officials expect at least one further hike before year-end. Rather than sparking a sell-off, the decision was broadly welcomed by markets: the 10-year Treasury yield actually eased slightly, ending an eight-day climb, as investors read the hike as confirmation the Fed remains serious about tackling above-target inflation without signalling anything more aggressive than already priced in. Weekly jobless claims and August housing starts data are due later Thursday for further clues on the economy's health.
Trump says US "hopefully" nearing end of war with Iran as Yemen fighting escalates. President Trump said the United States may be approaching the end of its roughly seven-month conflict with Iran, adding that Tehran wants to reach a deal and that he has held direct talks with Iranian officials. The comments came even as the wider conflict continues to expand into Yemen, with Iran-backed Houthi forces escalating attacks on Saudi Arabia and pushing for control of the Bab el-Mandeb Strait, a critical oil chokepoint linking the Red Sea to global markets. Trump is expected to meet Gulf Cooperation Council leaders on the sidelines of the UN General Assembly in New York next week to discuss a postwar strategy. Oil prices eased on the news, with Brent and WTI both extending Wednesday's declines as Saudi Arabia arranged ship-to-ship crude transfers through Oman to offset the damaged East-West pipeline.
Bank of England set to hold as Fed, ECB and Bank of Japan all tighten. The Bank of England is widely expected to leave its key rate unchanged on Thursday despite UK inflation rising to 3.1% in August, driven largely by a 23% year-on-year surge in motor fuel costs. A hold would mark a clear divergence from the rest of the developed world this week: the Fed hiked on Wednesday, the European Central Bank delivered its second hike of the year last week, and the Bank of Japan is expected to raise its own key rate when its meeting concludes Friday.
Trump threatens EU with tariffs over Canada associate-membership plan. President Trump threatened to impose tariffs on the European Union, or halt trade with the bloc entirely, if it proceeds with a proposal to make Canada the EU's first-ever "associate member." European Commission President Ursula von der Leyen had floated the idea as part of deepening ties between Brussels and Ottawa, including cooperation on manufacturing, defence and artificial intelligence. Canada has been seeking to diversify its trade relationships since ties with Washington deteriorated over tariffs earlier this year.
Management & RBA Speak
Chris Wright, US Secretary of Energy, on the Saudi pipeline outage:
Wright described the disruption to Saudi Arabia's East-West pipeline as a "brief and temporary interruption" that would be "measured in days," comments that helped ease supply concerns and contributed to oil's retreat through Thursday's Asian session.
Donald Trump, US President, on the state of the war with Iran:
Trump said the US is "hopefully" nearing the end of the conflict, telling reporters that Tehran wants to make a deal and that he has spoken with Iranian officials directly, though he offered no further detail on the substance of those talks.
Closing Line
That's the wrap for today's session. Governor Bullock's testimony before Parliament on Friday is the next domestic test, ahead of the RBA's own rate decision on September 28-29.