The Wall Street Wrap: September 16, 2026
The Fed raised rates for the first time since 2023, and Chair Warsh's hawkish tone on persistent inflation sent stocks lower into the close, with Treasury yields holding above 5%. SK Hynix and Intel discussed a landmark US chip manufacturing deal, Amazon extended its supplier-warrant strategy with an $8 billion Generac deal, and von der Leyen proposed Canada as the EU's first associate member.
Dow sheds 631 points as Fed delivers first hike since 2023, Warsh strikes hawkish tone
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
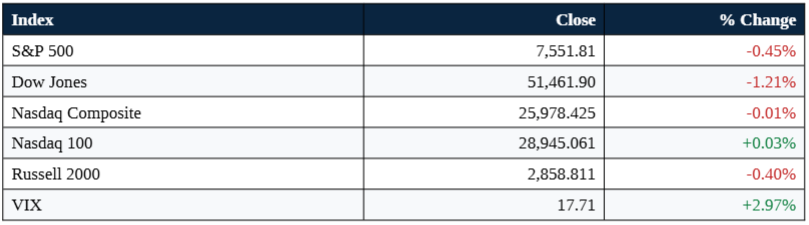
Stocks fell Wednesday after the Federal Reserve raised interest rates for the first time since July 2023 and Chair Kevin Warsh struck a firmly hawkish tone in his press conference. (For Further Reading: Fed Raises Rates to 4% as Growth Outlook Firms, Inflation Risk Persists). The Dow lost 631.21 points, or 1.21%, to close at 51,461.90, with Goldman Sachs (NYSE:GS) leading blue-chip decliners. The S&P 500 fell 0.45% to 7,551.81, while the Nasdaq Composite slipped just 0.01% to 25,978.42. All three indices were higher earlier in the session before the Fed's 2:00 p.m. announcement and Warsh's subsequent remarks. Banks had their worst day since February, with the SPDR S&P Bank ETF (NYSE:KBE) down 2% as Goldman Sachs, Wells Fargo (NYSE:WFC), Bank of America (NYSE:BAC), and Citigroup (NYSE:C) all fell roughly 3%.
ANALYTICAL VIEW
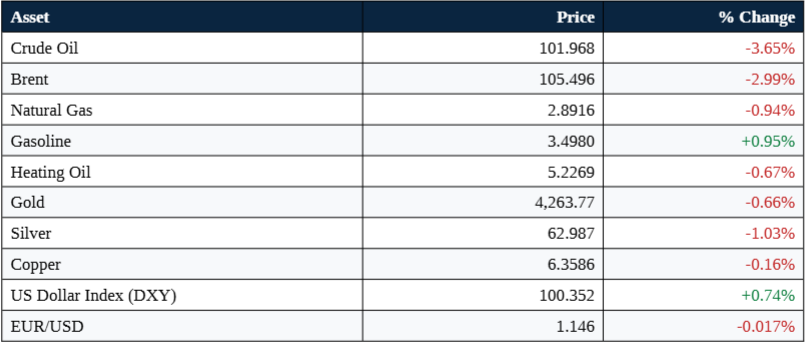
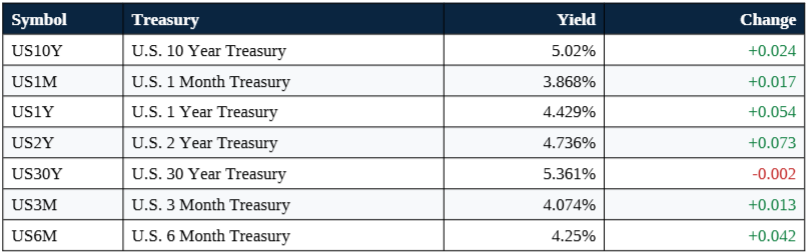
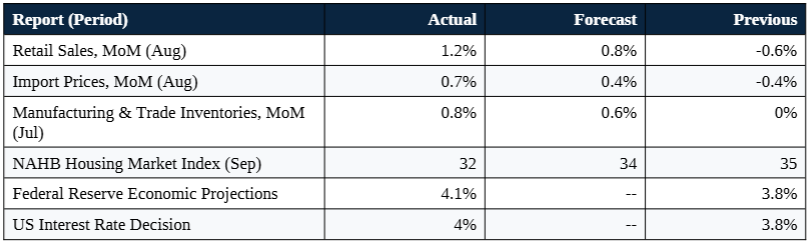
The Fed's quarter-point hike was widely expected, with futures pricing better than 90% odds heading into the decision, and the Federal Open Market Committee voted 12-0 to lift the target range to 3.75%-4%. What rattled markets was the tone rather than the substance: Warsh said "the plain fact is that inflation is too high, and has been for too long," and that "this summer's inflation readings do not tell me that underlying trends have meaningfully improved." Updated projections showed 16 of 18 officials expect at least one more hike this year, with headline PCE inflation forecasts revised up to 3.7% and core to 3.4%. The 10-year Treasury yield, which had already touched a 19-year high above 5% on Tuesday, traded back above that level again after the decision, and the dollar index jumped to its highest level since late July. Gold pared its early gains to trade little changed near $4,300 an ounce, as the higher-for-longer rate path increased the opportunity cost of holding the non-yielding metal.
The reaction underscored how much of the Fed's justification rested on factors well beyond its usual playbook. Warsh pointed to a strengthening labor market, still-elevated inflation, and geopolitical tension as the three factors behind the unanimous vote, while separately attributing the surge in Treasury yields to competition for capital from surging corporate debt issuance and AI-related capital expenditure rather than any loss of confidence in the Fed's inflation fight. Oil added to the inflation backdrop, with US diesel prices crossing $6 a gallon for the first time and crude holding above $100 a barrel, even as WTI eased and Brent fell on reports that Saudi Arabia's damaged East-West pipeline could resume flows within days. The White House pushed back sharply on the decision, with a spokesman calling it "not backed by a particularly compelling economic case" and arguing that current inflation is "entirely driven by an energy supply shock" rather than anything monetary policy addresses.
What could change the picture: upcoming inflation and employment data will shape whether the Fed's median projection of one more hike this year materializes, alongside the trajectory of oil prices and the Strait of Hormuz situation.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Lumentum Holdings (NASDAQ:LITE): +9.59%
- Coherent Corp (NYSE:COHR): +6.92%
- Astera Labs (NASDAQ:ALAB): +6.59%
- Axon Enterprise (NASDAQ:AXON): +5.96%
- Space Exploration Technologies (NASDAQ:SPCX): +5.15%
Top 5 Decliners:
- J.B. Hunt Transport Services (NASDAQ:JBHT): -13.30%
- ON Semiconductor (NASDAQ:ON): -9.02%
- Diamondback Energy (NASDAQ:FANG): -8.03%
- Occidental Petroleum (NYSE:OXY): -6.55%
- Texas Pacific Land (NYSE:TPL): -6.21%
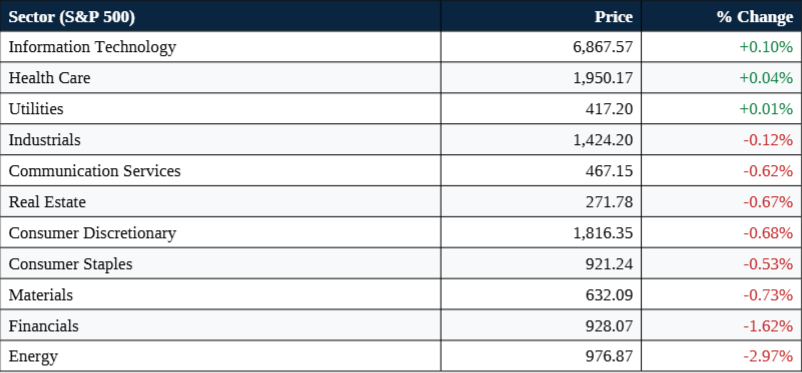
Note: optical and AI-infrastructure names led gainers even as the broader tape sold off, while transports, energy producers, and rate-sensitive names led decliners as the hawkish hike weighed on cyclicals.
AFTER-HOURS MOVERS
Gainers:
- Generac Holdings (NYSE:GNRC), +34.77% after hours: Shares surged after the company signed a long-term supply agreement with Amazon (NASDAQ:AMZN) for backup power generators supporting data centers, with initial deliveries valued at $2.4 billion in 2027-2028 as part of a broader deal that could reach up to $8 billion. Amazon also received a warrant to acquire roughly 1.69 million shares at an exercise price of $200.93, tied to future order volumes.
Decliners:
- Fluence Energy (NASDAQ:FLNC), -16.80% after hours: Shares plunged after the company cut its fiscal 2026 guidance for the second time this year, now expecting revenue of roughly $2.4 billion versus a prior midpoint of $3.0 billion and an adjusted EBITDA loss of about $200 million versus a prior midpoint loss of $10 million, citing continued delays ramping its Houston contract manufacturing facility.
- Lennar (NYSE:LEN), -2.64% after hours: Shares fell following a Q3 double miss, with adjusted EPS of $1.23 versus $1.32 expected and revenue of $8.05 billion versus $8.39 billion expected, both down sharply from a year ago as net earnings nearly halved to $284 million from $591 million. Gross margin on home sales compressed to 15.8% from 17.5%, and the company issued soft Q4 guidance.
- BCB Bancorp (NASDAQ:BCBP), -3.81% after hours: Shares fell after the company launched an underwritten common stock offering and disclosed it expects a net loss of $126.2 million to $136.1 million for the third quarter, tied to a planned sale of roughly $210 million in problem loans and a valuation allowance against its deferred tax assets.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Federal Reserve raises rates 25 bp for the first time since 2023, signals more to come. The FOMC lifted the federal funds target range to 3.75%-4.00% in a unanimous 12-0 vote, with Chair Kevin Warsh telling reporters "the plain fact is that inflation is too high, and has been for too long." Updated projections showed 16 of 18 officials expect at least one more hike this year, with four penciling in two, while inflation forecasts were revised higher and the unemployment outlook was revised down to 4.1%.
Retail sales beat expectations even as mortgage rates hit a 16-month high. US retail sales rose 1.2% in August, the strongest gain in five months and well above the 0.8% forecast, with gasoline stations, nonstore retailers, and electronics and appliance stores leading the increase. The strength in consumer spending came alongside a separate rise in borrowing costs: the average 30-year fixed mortgage rate climbed to 6.97% in the week ended September 11, its highest level since May 2025, as the run-up in Treasury yields ahead of today's Fed decision pushed total mortgage applications down 4.1% for the week. Trade prices added to the inflation picture, with import prices up 0.7% in August, well above forecasts and driven by nonfuel goods, while export prices rose 0.6% on higher prices for industrial supplies and capital goods.
SK Hynix in talks with Intel (NASDAQ:INTC) on US memory chip manufacturing. SK Hynix is discussing a deal that would see it manufacture memory chips on American soil for the first time, potentially by leasing part of Intel's long-planned Ohio facility or forming a venture with Intel and major cloud firms. Intel shares surged more than 5% on the report, while SK Hynix stock finished more than 4% higher in Seoul, though South Korean government approval remains a hurdle given the sensitivity of advanced memory technology.
Amazon (NASDAQ:AMZN) extends its supplier-warrant strategy with an up to $8 billion Generac (NYSE:GNRC) deal. The arrangement, covering backup power generators for Amazon's data centers, is the latest in a string of similar warrant deals following a comparable arrangement with Qualcomm (NASDAQ:QCOM) last week. Generac shares jumped in after-hours trading (see After-Hours Movers below).
Trump demands Fed cut rates to "1% or less" hours after the hike. President Trump wrote on Truth Social that the US is "carrying almost every country in the world" and called for rates to fall immediately, continuing his monthslong pressure campaign against the central bank. The White House said Trump still respects the Fed's independence but reserves the right to criticize its decisions.
Also today: Amazon (NASDAQ:AMZN) raised minimum pay for US operations workers to $20 an hour; Anthropic's head of public policy Sarah Heck said AI companies "can't be checking our own homework" on safety oversight; and the US removed Venezuela from its list of countries failing to combat drug trafficking for the first time in over 20 years, with Trump signaling Colombia could be next.
TOP STORIES: GLOBAL
Von der Leyen proposes Canada as EU's first associate member. In her annual State of the Union address, the European Commission president said the bloc wants to bring ties with Ottawa "to the highest level possible," with Canadian Prime Minister Mark Carney in attendance. The move would deepen the existing EU-Canada trade agreement into what von der Leyen called "an alliance for the future," though Carney has previously said Canada is not seeking full membership.
Bank of Japan set to raise rates this week as global tightening cycle broadens. The BOJ's decision follows the Fed's hike and the European Central Bank's move last week, while the Bank of England is expected to hold rates steady. The synchronized moves reflect a broader global response to persistent inflation pressures tied to energy costs and geopolitical tension.
US-China AI rivalry set to shadow Trump-Xi meeting next week. The upcoming summit between President Trump and Chinese President Xi Jinping in Washington is expected to be shaped by competing claims over AI development, following recent debate among US industry leaders over whether to slow the pace of model development.
Saudi Arabia works to restore East-West pipeline within days. US Energy Secretary Chris Wright said the pipeline, damaged in drone attacks and shut since last week, should resume flows soon, with Saudi Arabia using supertankers to shuttle oil through the Strait of Hormuz with US military assistance in the meantime. Independent analysts have cautioned the outage could last longer based on satellite imagery of the damage.
MANAGEMENT & FED SPEAK
Kevin Warsh, Chair, Federal Reserve, on inflation:
"The plain fact is that inflation is too high, and has been for too long."
Kevin Warsh, Chair, Federal Reserve, on the Fed's role:
"We cannot affect any individual price... don't have second and third order effects on the economy."
Kush Desai, White House Spokesman, on the rate hike:
"It's entirely driven by an energy supply shock... These are things that have nothing to do with interest rates."
CORPORATE ACTIONS & EARNINGS CALENDAR
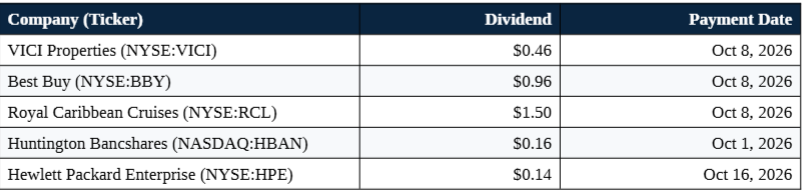
Top Ex-Dividend Companies for Thursday, September 17:
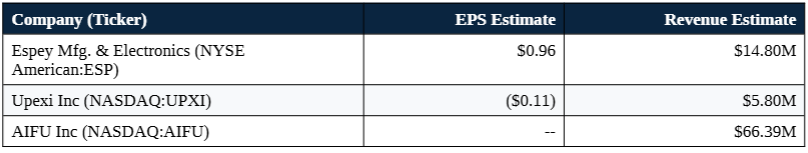
Upcoming Earnings (Thursday, Sept 17):
MACRO DATA RECAP
Wednesday, September 16 (today):
Thursday, September 17:
That's the wrap for today. Attention now turns to the Bank of Japan's rate decision, the Fed's next inflation and employment data, and whether Saudi Arabia's pipeline repairs ease the oil-driven pressure that shaped today's hawkish hike.