The Wall Street Wrap: October 2, 2026
US stocks rallied on Friday as a surprisingly weak September jobs report, with just 29,000 jobs added, raised hopes that the Fed will hold rates in October, even as Treasury yields reversed higher after an initial drop. Tesla beat delivery expectations, the G7 agreed to release 100 million barrels of emergency oil reserves, and Paramount Skydance said its combined company with Warner Bros. Discovery will be called Skydance.
Stocks rally as a 29,000-job September gain eases Fed hike fears, though bonds sell again; Tesla beats on deliveries and the G7 taps 100 million barrels of reserves
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
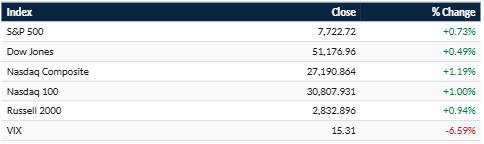
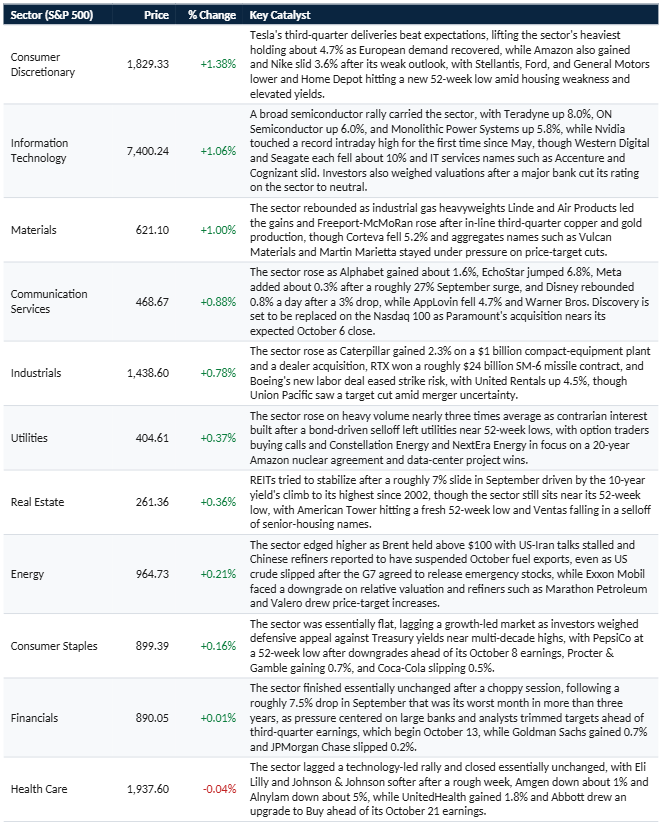
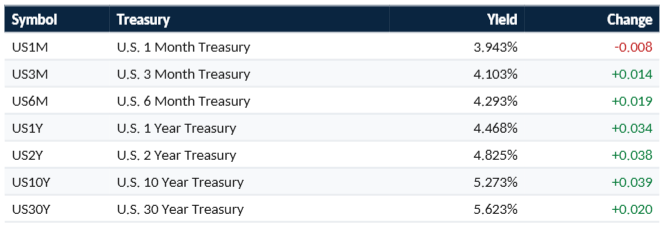
US stocks rallied on Friday after a surprisingly weak September jobs report raised hopes that the Federal Reserve will hold rates steady in October. The Dow Jones Industrial Average gained 250.4 points, or 0.49%, to 51,176.96, the S&P 500 rose 0.73% to 7,722.72, and the Nasdaq Composite climbed 1.19% to 27,190.864 after hitting an all-time high earlier in the session, while the Nasdaq 100 added 1.00% to 30,807.931. For the week, the Dow fell about 1.3% and the S&P 500 slipped 0.3%, while the Nasdaq gained about 0.6% for a third straight weekly advance. Consumer discretionary, technology, and materials led the sectors as Tesla's deliveries beat expectations and chip stocks rallied, while Treasury yields, which initially fell on the jobs data, reversed higher to leave the 10-year at 5.273%.
ANALYTICAL VIEW
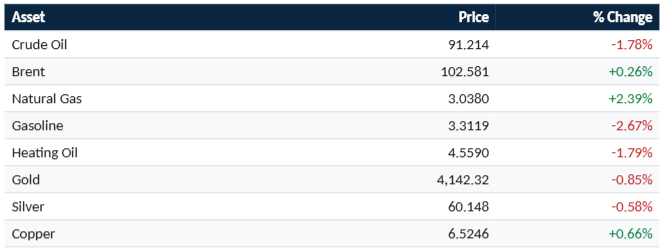
A weak jobs report did what softer inflation data could not: it gave stocks a clear green light, even as the bond market refused to follow. September payrolls rose just 29,000, about a third of what economists expected, and traders cut the odds of an October Fed hike to about 23%, with a hold priced at roughly 77%, down from about 35% on Wednesday. Yields fell at first but reversed through the session, with the 10-year finishing at 5.273% and the 30-year at 5.623%, as oil-driven inflation worries, heavy corporate debt issuance to fund AI buildouts, and swelling government deficits kept pressure on the long end. One strategist called the print exactly what the market wanted, not too hot and not too cold, while another cautioned that it does not change the Fed's trajectory of higher for longer.
Growth led the way as risk appetite returned. Nvidia, CrowdStrike, Palo Alto Networks, and AMD all touched record highs at some point in the session, semiconductors extended their rally with Teradyne up 8%, and the VIX dropped 6.6% to 15.31, while the transportation index gained 2.07% and small caps rose 0.94%, a sign that cyclicals joined the rally. Even so, the week left the Dow with its fourth negative week in five, and the Nasdaq's early record high faded as yields turned back up, a reminder that the bond market still sets the ceiling for stocks.
What could change the picture: Whether Wednesday's FOMC minutes and the September inflation reports due later this month confirm that the Fed can stay on hold in October, and whether the US-Iran standoff and the G7's reserve release keep oil, and the long end of the bond market, from pushing yields back toward their highs.
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Teradyne, Inc. (NASDAQ:TER): +7.997%
- Hewlett Packard Enterprise Company (NYSE:HPE): +7.355%
- Space Exploration Technologies Corp. (NASDAQ:SPCX): +7.355%
- EchoStar Corporation (NASDAQ:ECHO): +6.799%
- ON Semiconductor Corporation (NASDAQ:ON): +6.007%
Top 5 Decliners:
- Western Digital Corporation (NASDAQ:WDC): -10.219%
- Seagate Technology Holdings plc (NASDAQ:STX): -10.214%
- Accenture plc (NYSE:ACN): -6.312%
- Corteva, Inc. (NYSE:CTVA): -5.171%
- Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY): -4.957%
Note: A broad chip and hardware rally drove the gainers, while Western Digital and Seagate each fell more than 10% and Accenture gave back part of Thursday's surge.
AFTER-HOURS MOVERS
Gainers:
- Foghorn Therapeutics Inc. (NASDAQ:FHTX), +3.47% after hours: Shares bounced modestly after plunging 30.82% in the regular session to $2.02, extending a two-day sell-off that began when the company and Eli Lilly said they would not advance FHD-909 into dose expansion because Phase 1 data showed the SMARCA2/4 biology did not translate into the clinical efficacy required. The two companies also dropped a separate SMARCA2 degrader program, ending their collaboration, and Foghorn is cutting about 40% of its workforce to extend its cash runway into the second half of 2029, though its pipeline is now entirely preclinical and analysts issued a wave of downgrades and price-target cuts.
- Vistra Corp. (NYSE:VST), +1.22% after hours: Shares edged higher after Bloomberg reported that the Trump administration may offer a roughly $4 billion loan package to upgrade three of the company's nuclear plants, with Energy Secretary Chris Wright possibly announcing it Monday at the Perry complex, though the report is unconfirmed. The stock had closed 0.19% higher at $140.02 after swinging between about $134.79 and $143.00 on heavy volume, near its 52-week low of $132.66.
Decliners:
- NeuroSense Therapeutics Ltd. (NASDAQ:NRSN), -6.75% after hours: Shares fell after the biotech said Nasdaq staff determined it has not regained compliance with the $35 million minimum market value of listed securities requirement, and that it intends to request a hearing before a Nasdaq panel to seek more time. A timely request stays any suspension, so the shares are expected to keep trading, and the company, which has a market value of about $7 million, did regain compliance with the $1.00 minimum bid price after a 1-for-20 reverse split. The stock had closed 1.23% lower at $4.00.
- State Street Corporation (NYSE:STT), -3.82% after hours: Shares slid in extended trading after closing 0.77% higher at $175.96, on a day when analysts refreshed their targets ahead of the custodian bank's third-quarter report, due October 14.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
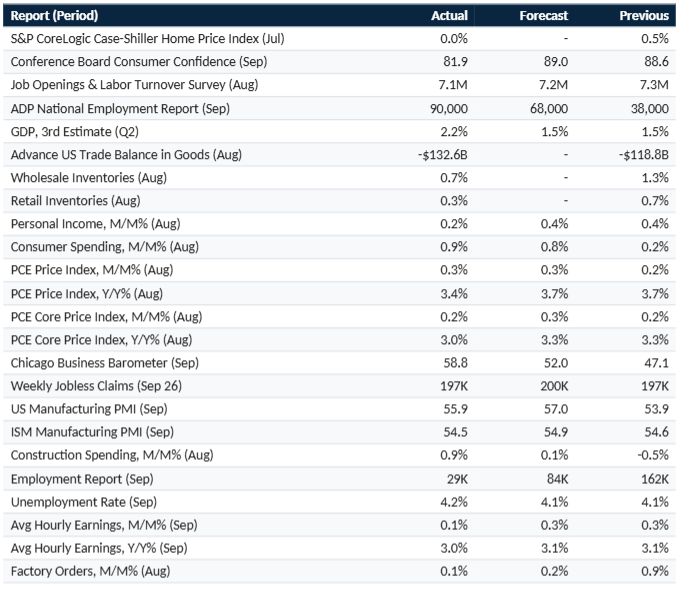
Payrolls rise just 29,000 in September, far below forecasts, as unemployment ticks up to 4.2% and wage growth slows. US employers added 29,000 jobs, well below the 84,000 economists expected, and the August gain was revised down to 133,000 while July swung to a 10,000 loss, leaving the two months combined 60,000 lower than previously reported. The unemployment rate rose to 4.2% from 4.1%, though the increase reflected people entering the labor force, with participation rising to 61.8%, and average hourly earnings rose just 0.1% on the month and 3.0% from a year earlier, the slowest annual pace since May 2021. Health care added 17,000 jobs, construction 11,000, and manufacturing 9,000, while financial activities lost 7,000, and the report was the last broad read on the labor market before the November midterm elections.
Tesla beats third-quarter delivery expectations as European demand recovers. The electric-car maker delivered 486,532 vehicles, topping the 461,100 analysts expected, after producing 464,391 vehicles, and deployed 13.7 gigawatt-hours of energy storage. Deliveries eased from 497,099 a year earlier but rose from 480,126 in the second quarter, and the shares gained about 4.7%, with Tesla due to report third-quarter financial results after the close on October 21.
Paramount Skydance says the combined company with Warner Bros. Discovery will be called Skydance. CEO David Ellison said the name is meant to preserve the separate identities of the Paramount and Warner Bros. studios, with the company set to change its legal name to Skydance Corporation on October 6, when its Class B shares are expected to move from Nasdaq to the New York Stock Exchange under the ticker SKYD in place of PSKY. A US judge on Wednesday allowed the $110 billion acquisition to close after approving a settlement with a California-led group of 12 states that had sued to block it, and Ellison has named Mattel CEO Ynon Kreiz co-CEO to run day-to-day operations and lead the integration. The combined company faces a target of $6 billion in cost savings while managing about $80 billion in debt, and Bloomberg reported that Paramount's film chiefs will take over operational oversight of Warner Bros. Pictures, with the studio's current leaders not joining the merged company.
onsemi gains 6% after revising its Synaptics deal to all cash. The revised agreement, announced after Thursday's close, values Synaptics at $123 per share, or about $5.7 billion, versus roughly $7 billion under the original June deal, and followed an unsolicited rival bid. onsemi said the transaction should be immediately accretive to non-GAAP earnings and that it sees additional revenue and production synergies beyond the $200 million of annual run-rate savings previously announced, with fully committed debt financing and no financing condition to closing. The deal has been approved by the US Federal Trade Commission, with other regulators still reviewing and a close still expected by mid-2027.
Nike slides to a 12-year low as investors question the pace of Elliott Hill's turnaround. The shares fell as much as 8% to $32.22 in early trading before closing 3.6% lower at $33.87, far below a 2021 peak of about $175, with the company's market value and earnings more than halved in the two years since Hill returned as CEO. Most of the savings from the restructuring announced Thursday will not be realized until fiscal 2029 and 2030, and sportswear, China, and the Jordan brand, which together account for more than half of sales, remain problem areas, with Hill acknowledging that stabilizing China will take "multiple seasons." Investors now look to the company's investor day on November 16 and 17 for a clearer roadmap to restoring growth and profitability.
Also today: Factory orders edged up 0.1% in August after a downwardly revised 0.8% gain in July, with a 4.3% drop in civilian aircraft orders offsetting strength in electrical equipment and machinery; US-listed ETFs have taken in more than $1.54 trillion this year through September, already topping the full-year record of $1.52 trillion set in 2025; gold fell about 0.8% to roughly $4,145 an ounce and is on track for a weekly loss of more than 3% as the bond rout and a stronger dollar weighed; and the Grayscale Zcash ETF is up more than 60% in the past month and about 253% this year.
TOP STORIES: GLOBAL
G7 agrees to release 100 million barrels of emergency reserves to cool surging diesel prices. The leaders said the release will begin immediately and run over four months, with a "frontloaded substantial diesel release" in the first 20 days, coordinated through the International Energy Agency, and pledged to refrain from export restrictions on energy products among the group. The announcement followed pressure from the Trump administration on Europe to deploy its stocks as an alternative to a US diesel export ban, which would have hit a bloc that relied on the US for about half of its diesel imports in August. US diesel averaged $6.37 a gallon on Friday after hitting record highs in September, and oil initially fell on the news before paring losses, leaving Brent down about 1.5% on the week.
Saudi Arabia is preparing an offensive against Houthi militants in Yemen, officials say. Options include a coastal push to secure the Red Sea shipping route or an assault on multiple fronts, according to six people with knowledge of the preparations, with the operation expected in the coming weeks and led by Yemeni forces overseen by Riyadh with Saudi air support. It aims to reverse the Houthis' gains last month, when they advanced down the coast and seized the Bab el-Mandeb strait, a route that has gained importance as an alternative to the Strait of Hormuz. More than 100,000 Yemeni troops could be mobilized, the United States is providing intelligence and advisers, and Pakistan and Turkey have supplied equipment, while timing estimates range from within a week to after the US midterm elections in early November.
Russia strikes a Kyiv bridge for a second straight day as its air campaign on infrastructure intensifies. An evening drone strike hit the closed Southern Bridge, the latest in a series of attacks since Thursday that forced the full or partial suspension of traffic across it and two other bridges over the Dnipro River, which an estimated 500,000 commuters cross each day. A senior Ukrainian official linked the attacks to an order by President Vladimir Putin last month to scrap constraints on Russia's air campaign, while a separate drone strike killed one person in Kyiv and a guided-bomb attack killed two and wounded 32 in Kharkiv. Ukraine, which says it needs at least 300 Patriot interceptor missiles for the winter, has kept up its own drone attacks on Russian oil facilities, including the Lukoil refinery in Volgograd.
MANAGEMENT & FED SPEAK
Austan Goolsbee, President, Federal Reserve Bank of Chicago, on whether to hike in October:
Goolsbee said there is "plenty of room for anything to be on the table," adding that the jobs data show a steady labor market and that inflation remains the Fed's bigger problem.
Scott Bessent, US Treasury Secretary, on diesel supplies (Thursday):
Bessent said European partners "should accelerate delivery on their existing commitments" and make additional supplies available immediately.
David Ellison, CEO, Paramount Skydance, on the new name:
Ellison said the name gives the combined company "an identity of its own" while letting the Paramount and Warner Bros. brands stay in the spotlight.
Elliott Hill, CEO, Nike, on the Jordan brand (Thursday):
Hill said Nike has been "oversupplying our iconic retro product," and admitted that a "lack of energy in the lifestyle space" is hurting traffic.
CORPORATE ACTIONS & EARNINGS CALENDAR
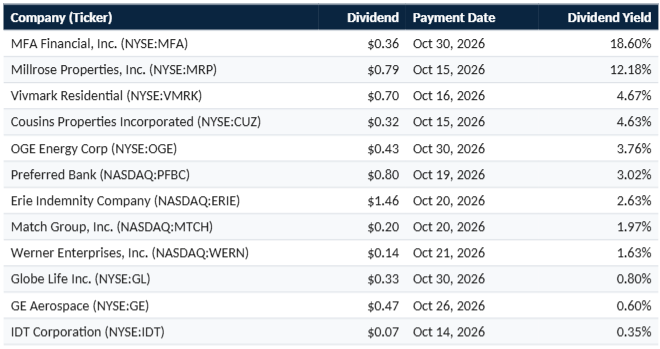
Top Ex-Dividend Companies for Monday, October 5:
Upcoming Earnings (Monday, October 5):
No earnings reports are scheduled for Monday.
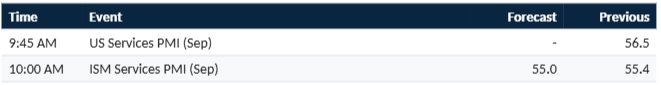
Economic Calendar (Monday, October 5):
MACRO DATA RECAP
That's the wrap for today. Attention now turns to Monday's ISM services reading, Wednesday's FOMC minutes, and the September inflation reports later this month, which will test whether the market's growing belief in an October Fed hold survives stubborn oil prices, soaring long-term yields, and an unresolved US-Iran standoff.
Before You Trade: What Prediction Markets Actually Risk
Related post