The Wall Street Wrap: September 17, 2026
US stocks rebounded sharply Thursday as Treasury yields and oil prices retreated, with tech leading a bounce back from Wednesday's Fed-driven selloff. Nvidia's Jensen Huang forecast doubling chip sales next year, the SEC unveiled a tokenized-stock exemption, and the Bank of England held rates steady, diverging from the Fed's hike.
Stocks rebound as yields and oil retreat, tech leads the bounce back from Fed-day selloff
Welcome to Wall Street Wrap, your quick end-of-day rundown of what moved US markets today, plus what's shaping global sentiment overnight.
MARKETS TODAY
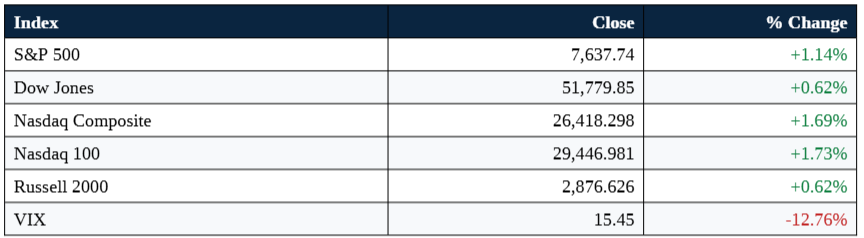
US equities climbed Thursday, clawing back Wednesday's Fed-day losses as Treasury yields and oil prices retreated and technology stocks led the advance. The Dow rose 317.95 points, or 0.62%, to 51,779.85. The S&P 500 gained 1.14% to 7,637.74, while the Nasdaq Composite jumped 1.69% to 26,418.298. "Magnificent Seven" names Nvidia (NASDAQ:NVDA) and Amazon (NASDAQ:AMZN) each rose about 2%, Microsoft (NASDAQ:MSFT) gained 1.5%, and Intel (NASDAQ:INTC) advanced roughly 7% on continued optimism around US chip manufacturing. The VIX fell sharply, down 12.76% to 15.45, reflecting the sharp reversal in risk sentiment from a day earlier.
ANALYTICAL VIEW
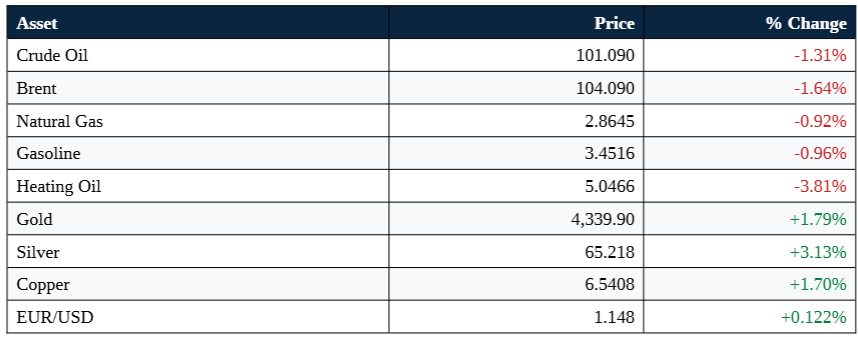
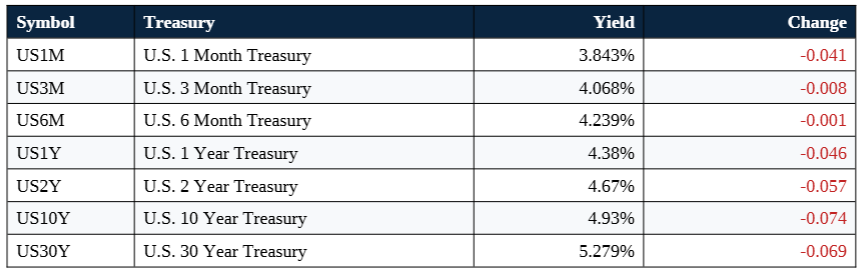
Thursday's rally was a straightforward reversal of Wednesday's Fed-driven selloff, powered by a pullback in the two forces that had weighed on stocks a day earlier: yields and oil. The 10-year Treasury yield fell back below 5%, dropping to 4.93%, as bond markets found some relief now that the Fed's decision is behind them. Oil added to the risk-on tone, with WTI easing toward $101 a barrel and Brent near $104, as supply concerns eased after reports that Saudi Arabia would route more crude to Asian refiners via ship-to-ship transfers near Oman's Sohar port, easing fears tied to the Strait of Hormuz. Market strategists summed up the day's mood as one of relief, framing the bounce as recognition that the Fed is at least addressing a sticky inflation problem.
Still, the relief comes with a caveat that investors are unlikely to ignore for long. Strategists cautioned that the market still faces the possibility of "extreme" volatility depending on how the Middle East conflict evolves, warning that persistently elevated oil prices could get passed through to consumers and make inflation progressively harder to tame. That risk sits alongside a still-hawkish Fed: Chair Kevin Warsh reiterated Wednesday that "this standard has not been satisfied" on inflation, and projections point to at least one more hike this year. Thursday's calmer tape looks less like an all-clear and more like markets exhaling after a well-flagged decision, with the same oil-and-inflation tension from Wednesday still very much intact.
What could change the picture: whether Saudi Arabia's rerouted crude flows durably ease Strait of Hormuz supply fears, and how the Fed's rate path evolves into its next meeting.
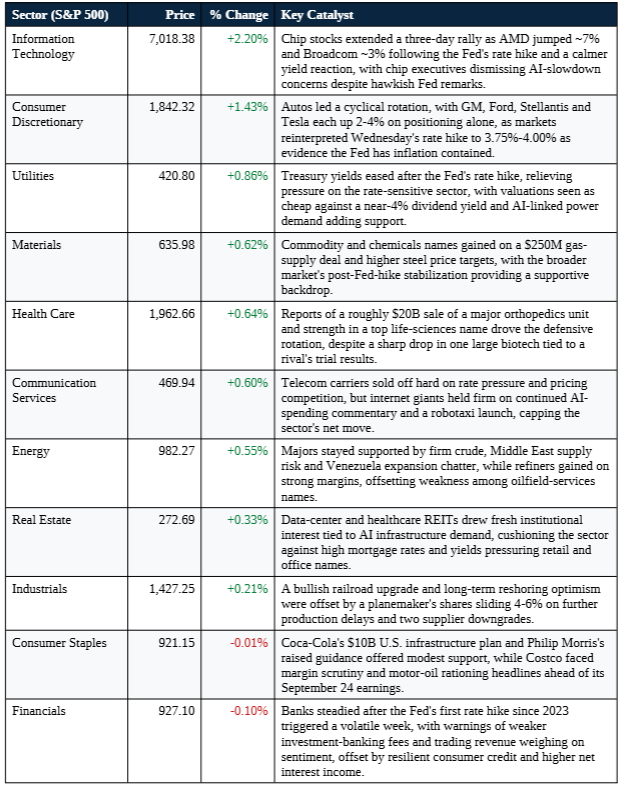
SECTOR PERFORMANCE
WINNERS & LOSERS
Top 5 Gainers (across S&P, Nasdaq, Dow):
- Generac Holdings (NYSE:GNRC): +18.34%
- Astera Labs (NASDAQ:ALAB): +9.06%
- Super Micro Computer (NASDAQ:SMCI): +9.50%
- ARM Holdings (NASDAQ:ARM): +8.58%
- Moderna (NASDAQ:MRNA): +8.55%
Top 5 Decliners:
- T-Mobile US (NASDAQ:TMUS): -5.57%
- DaVita (NYSE:DVA): -5.57%
- Paramount Skydance Corp (NASDAQ:PSKY): -4.63%
- Copart (NASDAQ:CPRT): -3.76%
- CoStar Group (NASDAQ:CSGP): -3.51%
Note: yesterday's biggest after-hours mover, Generac, extended its gains into the regular session, while AI-infrastructure and semiconductor names broadly led the advance; telecom, healthcare services, and a few media/data names lagged even as the broader tape rallied.
AFTER-HOURS MOVERS
Gainers:
- Ultragenyx Pharmaceutical (NASDAQ:RARE), +2.48% after hours: Shares extended their regular-session surge after the FDA granted full approval of FAYUVI (UX111), a one-time gene therapy for Sanfilippo syndrome Type A, the company's second gene therapy approval and sixth FDA approval overall. The approval also carries a Priority Review Voucher, and the news marks a reversal for a stock that had hit fresh 52-week lows earlier this month.
- Intapp (NASDAQ:INTA), +3.73% after hours: Shares rose after the company announced its Celeste plug-in is now live inside ChatGPT Enterprise, extending its OpenAI collaboration and giving law firms governed, entitlement-controlled access to proprietary firm knowledge within daily AI workflows.
Decliners:
- Xenon Pharmaceuticals (NASDAQ:XENE), -24.32% after hours: Shares plunged after the company disclosed a voluntary pause on new patient enrollment in its ongoing azetukalner studies for major depressive disorder and bipolar depression, following an analysis of neuropsychiatric adverse events not previously observed in the earlier Phase 2 X-NOVA trial. The safety concern overshadowed otherwise positive news that Xenon submitted an NDA to the FDA for azetukalner in focal seizures.
- Steel Dynamics (NASDAQ:STLD), -3.5% after hours: Shares gave back gains after rallying nearly 3% during the regular session on strong Q3 2026 earnings guidance of $5.34-$5.38 per diluted share, well above consensus of $3.69, as investors digested the guidance alongside Nucor's own stronger Q3 outlook and broader market caution following the Fed's rate hike this week.
COMMODITIES & RATES
US TREASURY YIELDS
TOP STORIES: US
Nvidia (NASDAQ:NVDA) CEO Jensen Huang says chip sales will double next year. Speaking at a summit with the UK's King Charles III, Huang said "I expect Nvidia to sell twice as many chips as this next year as we do this year," citing AI investment demand across nearly every country the company operates in. The forecast follows Nvidia's recent guidance for 70% revenue growth in the fiscal year ending January 2028.
SEC unveils long-awaited "Innovation Exemption" for tokenized stocks. The five-year exemption lets trading platforms and liquidity providers offer blockchain-based versions of public company shares, provided token holders retain the same voting and dividend rights as traditional shareholders and issuers can object to being tokenized. SEC Chair Paul Atkins said the move is designed to "resolve challenges that have prevented responsible innovation from taking root in the United States," and comes two days after crypto's Clarity Act failed to advance in the Senate.
Nike's (NYSE:NKE) grip on its Dow seat looks increasingly tenuous. Shares have fallen more than 43% this year to 12-year lows, and S&P Dow Jones Indices will remove Nike from the S&P 100 before trading begins September 21. Nike now holds the smallest weight among the Dow's 30 components at 0.4%, a position that has preceded removal in at least half of the index's last 10 changes since 2013.
CoreWeave (NASDAQ:CRWV) plans to raise $3 billion in convertible debt to fund AI infrastructure buildout. The Nvidia-backed cloud company also launched an at-the-market stock sale program for up to 35 million shares, part of an effort to move toward an investment-grade credit profile. Shares fell more than 3% in early trading despite gaining over 16% year-to-date.
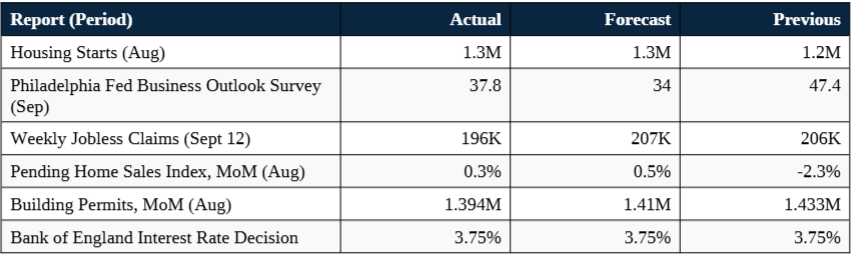
Also today: Applied Materials (NASDAQ:AMAT) said it will invest $5 billion in India over the next decade to expand research and supply chain capacity; jobless claims fell to 196,000 for the week ended September 12, below the 207,000 forecast; and August housing starts and building permits both came in below expectations amid rising mortgage rates.
TOP STORIES: GLOBAL
Bank of England holds rates at 3.75%, diverging from the Fed. The MPC voted 6-3 to hold, with three members preferring a 25-basis-point hike. Governor Andrew Bailey said "the longer this volatility persists, the bigger the impact it will have on inflation, and the more likely it is we will need to raise Bank Rate," as UK inflation rose to 3.1% in August on surging motor fuel costs. A hike is widely expected at the BoE's November meeting.
EU proposes banning under-13s from social media. European Commission President Ursula von der Leyen unveiled the "EU Kids Act," which would also place 13-to-15-year-olds' accounts under parental control and ban addictive features like infinite scroll and profiling-based recommender feeds for minors. The proposal follows similar moves in Australia, Britain, and several other countries, though tech lobby group CCIA Europe warned of privacy risks from the required age-verification data collection.
Central banks diverge sharply across the G10 as tightening cycle broadens. The Fed's hike this week joins recent moves from the European Central Bank and an expected Bank of Japan hike, while the Bank of England held steady and Canada and Sweden remain in wait-and-see mode. Australia and Norway sit at the higher end of the G10 policy-rate spectrum, with Australia's central bank seen as likely to hike again this month.
World Bank says it attracted $112 billion in private capital in the year to June, more than triple fiscal 2022's level. President Ajay Banga said the bank aims to more than double that figure to over $200 billion within two to three years by packaging loans to appeal to institutional investors such as pension funds and asset managers.
MANAGEMENT & FED SPEAK
Kevin Warsh, Chair, Federal Reserve, on inflation:
"We must be confident that underlying inflation is moving to our objective clearly and at sufficient speed... this standard has not been satisfied."
Donald Trump, President, on the Fed:
"Interest rates in the United States should be 1 per cent, or less, because we are the best credit in the world — by far."
Jensen Huang, CEO, Nvidia, on chip demand:
"I expect Nvidia to sell twice as many chips as this next year as we do this year."
Andrew Bailey, Governor, Bank of England, on rate policy:
"So far, higher global energy costs have had a limited effect on price and wage setting in the U.K. But the longer this volatility persists, the bigger the impact it will have on inflation, and the more likely it is we will need to raise Bank Rate to ensure that inflation falls back to our 2% target."
CORPORATE ACTIONS & EARNINGS CALENDAR
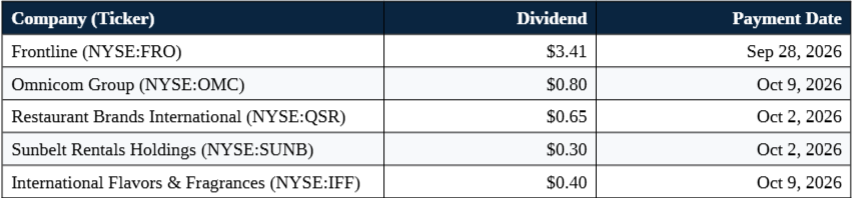
Top Ex-Dividend Companies for Friday, September 18:
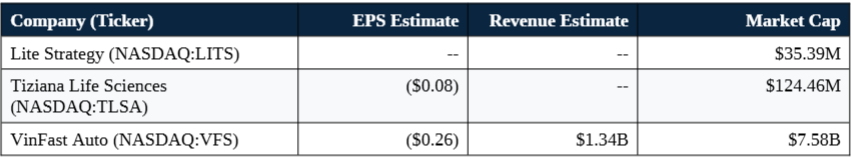
Upcoming Earnings (Friday, September 18):
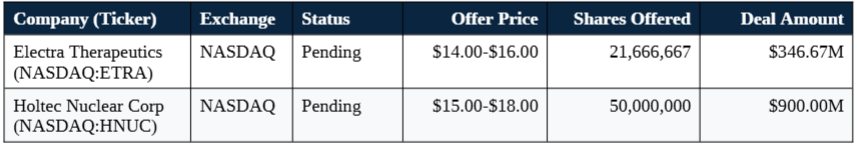
IPO Calendar (Friday, September 18):
MACRO DATA RECAP
Thursday, September 17 (today):
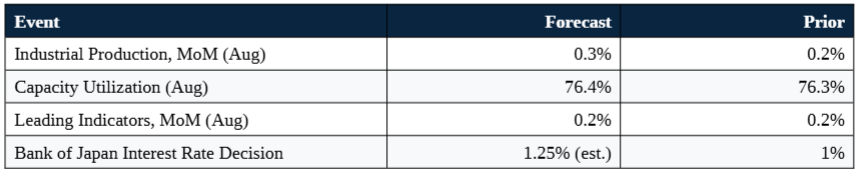
That's the wrap for today. Attention now turns to Friday's Bank of Japan rate decision and US industrial production data, along with whether Saudi Arabia's rerouted crude flows continue to ease the oil-driven pressure that has weighed on the inflation outlook all week.